Caterer insurance
One application, multiple quotes.
All in one place.
Essential Protection
From
$25
/month*
Could help cover claims against your business for property damage and injuries to others.
What’s included:
General Liability
Coverage limits: $100K to $2M†

Get multiple quotes in less than 10 mins
Essential Protection
From
$25
/month*
Could help cover claims against your business for property damage and injuries to others.
What’s included:
General Liability
Coverage limits: $100K to $2M†
Get multiple quotes in less than 10 mins
Would you rather pick and choose your coverage? Explore all options
Over 1 million customers worldwide.

Buy instantly online.

Written by
Why Do I Need a Catering Insurance Policy?
Crafting unforgettable events with mouthwatering dishes and impeccable service is your specialty. But even the most artfully orchestrated events can sometimes hit a sour note. A spilled tray can ruin a guest’s outfit, a kitchen mishap could spark a fire, or a client may claim the food left them sick. The right insurance policies can help safeguard your catering business, keeping you protected when the unexpected disrupts your carefully curated plans.
Below are some of the most common types of insurance policies that caterers carry to stay protected.
What Type of Caterer Insurance Do I Need?

General Liability
A foundational insurance coverage to help handle costs from third-party accidents, property damage, and bodily injury.
From
$25
/month*

Equipment and Business Property
Also known as inland marine insurance, this coverage can financially protect equipment and inventory that’s in transport or stored offsite.
From
$20.83
/month‡

Workers’ Comp
Coverage to help take care of employees who get sick or injured on the job. Most states require this coverage for small businesses with full- or part-time employees. It also can benefit business owners who don’t have employees.
From
$38.91
/month*

From
$25.83
/month*
Business insurance —
a quick explainer
Learn more about policies for small businesses, what they cover, why you might need them, and how we can help – all in just 60 seconds.
Business insurance is often made up of different types of policies to cover different things, similar to how your health insurance can be made up of medical dental and vision coverage. Here are some of the ones small business owners need. General liability is kind of the Swiss army knife of insurance. It can do a lot, like help handle costs from third party accidents, property damage, bodily injury, and more. Nobody’s perfect, right? That’s what professional liability is for. It could come in handy in the event of honest mistakes or claims of negligence. Workers’ comp can protect your business and help take care of employees who get sick or injured on the job. Small businesses are big targets for cyber criminals. Cyber Insurance can help cover costs associated with stolen customer data, cyber attacks, breaches, and fraud. BOP or a business owners policy combines different types of coverages like general liability and commercial property insurance. Putting them together for you is where we come in. You tell us a bit about your business online or on the phone, and we customize the coverage options for what you do and what you need. It’s your business, it should be your insurance as well. That’s why we’re here.
What Does Caterer Insurance Cover?
From whipping up memorable menus to managing bustling events, catering is as rewarding as it is demanding — and it comes with its share of hazards. We can help you choose the right coverages and policies to protect you from some of the most common ones:
A guest trips over a catering tray left in the wrong spot, spraining their ankle. Now you’re looking at medical bills and potential legal fees. A general liability policy could help pay for those types of third-party claims, keeping your business out of hot water.
During a high-end wedding reception, a server accidentally spills red wine on the bride’s custom gown. The furious client demands compensation for cleaning. General liability insurance could help cover the cost.
Your line-cook cuts their hand badly while rushing to plate the main course. Workers’ compensation insurance can help cover medical bills and lost wages as the line-cook recovers.
This coverage is often legally required and protects your business from costly claims, while ensuring your crew gets the care they need. Even if you work solo, workers’ comp is worth considering since some health insurance policies won’t cover work-related injuries.
You lock your portable ovens and warming trays in your vehicle while you take a short break. When you return, you discover that someone broke into your vehicle and stole your equipment. An equipment and business property policy could help cover the cost to replace or repair the equipment.

What Does Caterer Insurance Cost
Try our insurance calculator.
Get a quick estimate in just 3 steps.
Answers to More Caterer Insurance Coverage Questions
Most states require you to carry workers’ compensation insurance if you have employees. There also may be licensing requirements that require certain liability coverages. We recommend checking with your state and local governments.
The cost for your insurance coverage is determined largely by the type of work you do, the types of risks you’re exposed to, the square footage of your office, and the number of employees you have.
Some other factors can include where your office is located, how many years of experience you have, and your annual revenue.
If you’re thinking of buying caterer insurance, we recommend having the following information on hand when using our caterer insurance calculator:
- State where you do business
- Your type of business or trade
- Annual revenue estimates
This information can make it easier to get a quote from one of our insurers.
Small business insurance is what we do. Whether it’s covering you for accidents and mistakes, meeting workers’ comp requirements, or protecting your office and your tools and equipment, we can help find the coverage you need for your catering business.
We provide customized coverage options and quotes from top-rated small business insurers — all in just 10 minutes. More than 1 million small business owners worldwide trust us with their insurance, and we consistently earn high customer ratings and reviews.

Why Small Businesses Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

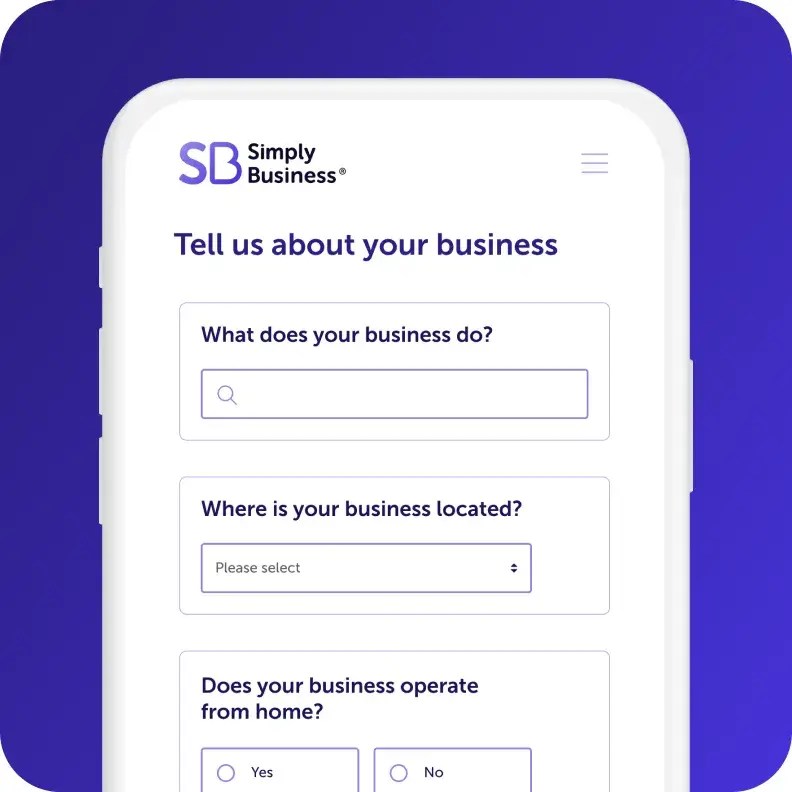
Start your quote
Answer a few questions about
your business in one form.

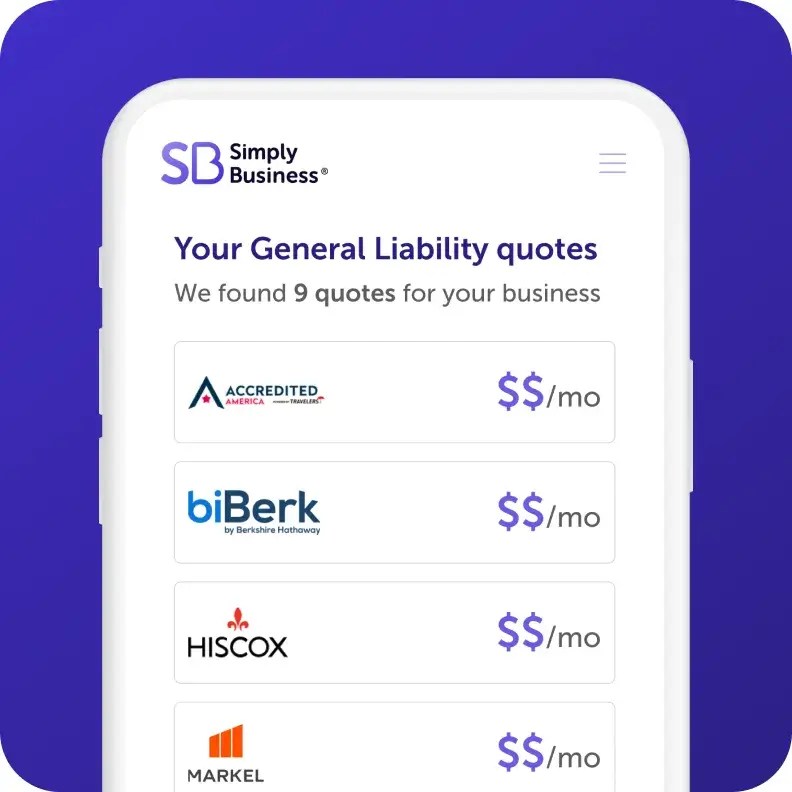
Review quotes
Compare quotes side by side from top-rated insurers and customize your coverage.

Get protected in minutes
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.

Written by
Our +1 million customers worldwide are big fans. And you will be too.
I went online, looked around, and found Simply Business. The process was so seamless. I got my certificate within minutes. It was just phenomenal.
Karen
Owner of Tangaza Bath & Body Studio LLC
With Simply Business I know I can look at different carriers, but also see all my stuff in the same place… a lot of [insurance] providers don’t offer a variety of coverage, all in one place.
Jef
Owner of Bunker83 LLC
It wasn’t overwhelming to figure out what was covered and what wasn’t covered. And the cost was competitive.

Kim
Owner of Room to Breathe Professional Organizing
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information
9-minute read
A General Liability Insurance Guide for Small Business
13-minute read
The Real Costs of Not Having Business Insurance
7-minute read
Here’s How to Get Customers During Your Off-Season
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.
† Limits may vary by state and nature of your business.
‡ Displayed price is based on the lowest available coverage limit for Equipment and Small Tools policies.
Page last updated: