Freelancer Insurance
Find out what freelancer insurance coverage you need. Compare policies from leading national insurers. Get a quote in minutes.

Over 1 million customers worldwide.

Buy instantly online.

Written by
Why Do I Need Freelancer Insurance?
As a freelancer, you’ve worked hard to build your own business. You enjoy juggling multiple projects and working a flexible schedule. You know what it takes to grow your business — and you put 100% into succeeding as a solo entrepreneur.
But what would happen if you were sued or one of your clients got injured in your office?
Without business insurance, you may be at financial risk. It’s fairly easy for an angry client to sue you for negligence or for an injury that happens if a client visits you onsite. And even freelancers can experience costly third-party property damage.
What Freelancer Insurance Do I Need?

General Liability
A foundational insurance coverage to help handle costs from third-party accidents, property damage, and bodily injury.
From
$20.75
/month*

Professional Liability Insurance
Coverage for damages and legal costs for mistakes or negligence claims. This policy is often recommended for businesses that provide advice and guidance to their clients. It also can cover errors that result in unsatisfactory service.
From
$25.83
/month*
Business insurance —
a quick explainer
Learn more about policies for small businesses, what they cover, why you might need them, and how we can help – all in just 60 seconds.
Business insurance is often made up of different types of policies to cover different things, similar to how your health insurance can be made up of medical dental and vision coverage. Here are some of the ones small business owners need. General liability is kind of the Swiss army knife of insurance. It can do a lot, like help handle costs from third party accidents, property damage, bodily injury, and more. Nobody’s perfect, right? That’s what professional liability is for. It could come in handy in the event of honest mistakes or claims of negligence. Workers’ comp can protect your business and help take care of employees who get sick or injured on the job. Small businesses are big targets for cyber criminals. Cyber Insurance can help cover costs associated with stolen customer data, cyber attacks, breaches, and fraud. BOP or a business owners policy combines different types of coverages like general liability and commercial property insurance. Putting them together for you is where we come in. You tell us a bit about your business online or on the phone, and we customize the coverage options for what you do and what you need. It’s your business, it should be your insurance as well. That’s why we’re here.
What Type of Freelance Business Insurance Should I Consider?
It depends on the type of work you do, how much property you have, and how likely you are to get injured on the job. If you’re unsure of anything, you can talk to one of our licensed insurance agents, who are happy to help you find and compare the best policies for your business.
Freelancers who want comprehensive coverage may want to get both general liability and professional liability insurance. Together, these two policies can help protect you from all angles. Anything can happen, and just one incident can make getting a policy worthwhile.
Take a look at how general liability and professional liability insurance can work for freelancers:
General Liability (GL) Insurance
Many freelance business owners can benefit greatly from general liability insurance, as it can help cover the costs associated with third-party accidents, injuries, and property damage. In fact, it’s one of the first policies many small business owners get.
Let’s take a look at how GL insurance usually works. Let’s say you’re a freelance designer and animator who works with several large advertising agencies. One day, you invite a client into your home to discuss a project. During the visit, you accidentally spill hot coffee on your client’s expensive laptop.
Not only is the computer unsalvageable, but your client also loses hundreds of electronic files. Later, you realize it will cost thousands of dollars to replace the equipment, software, and damage done by the client losing all those files.
If you have general liability insurance, your policy can typically help cover these costs, up to your policy’s limit, so you don’t have to pay out-of-pocket for all of your client’s losses and expenses.
General liability insurance can usually cover:
- Bodily injury to another person (like a client)
- Third-party property damage
- Personal and advertising injury
- Medical expenses
- And more
Here’s what general liability insurance usually doesn’t cover:
- Damage to your own property
- Professional services
- Damage to your work
- Motor vehicles while in business use
- Expected or intentional injury or damage
- And more
Professional Liability Insurance
Most freelancers need professional liability insurance too, especially if your company offers services such as design, writing, data entry, or photography. Professional liability insurance is designed to help cover costs associated with claims of negligence, libel, slander, or copyright infringement (up to your policy limit).
Here’s how it works. Let’s say you’re a successful freelance writer who juggles multiple clients. While on a deadline, you inadvertently misrepresent one of your clients in an article. The article is published without an editorial review and causes the client to lose significant revenue. Later, your client sues you for negligence, costing you thousands of dollars in damages and legal fees.
If you had professional liability insurance, it could cover you up to your policy limit. It also could help cover legal fees along the way. Think you’ll never get sued? Think again. Unfortunately, 43% of small business owners polled say they’ve been involved in or threatened by a civil lawsuit, according to the US Chamber Institute of Legal Reform.
If you’re a freelancer, get professional liability insurance now before it’s too late. Your policy can typically cover:
- Negligence or alleged negligence
- Legal defense costs
- Omissions or alleged omissions
- Copyright infringement
- Claims and damages
- And more
Professional liability insurance usually doesn’t cover:
- Intentional acts and omissions
- Property damage
- Medical expenses
- Bodily injury
- False advertising
- Employment matters
- Patents and trade secrets
- And more
Why Should I Get Freelance Liability Insurance?
As a freelancer, you may think you’ll never get sued. After all, you’re not a large company with a lot of assets — why would someone bother going after you?
But the reality is, you’re still at risk. And even as a team of one, you still can be on the hook if a client or vendor gets injured while working on your property.
Be aware that an unexpected incident can happen at any time. That’s why it’s so important to get business insurance early on, before something bad happens. Just one costly injury or claim is enough to put a freelancer out of business.
Answers to More Freelance Insurance Coverage Questions
It depends on where you live and work — and the type of work you do. Every state operates a little differently. For example, if you offer freelance architecture services to contractors, you may need a general liability insurance policy, depending on where you live.
Whether it’s required or not, it’s still a good idea to get business insurance. Financial protection can never hurt, especially because we live in such a litigious society where lawsuits are commonplace.
Good news! In general, business insurance is a tax-deductible expense for freelancers. It can help lower your taxable income, which is great for your wallet. If you have questions about deducting your specific insurance premiums, we recommend you talk to an accountant or tax specialist.
The cost can vary greatly, depending on your freelance business. In general, we help freelancers find affordable policies based on:
- The size of their business
- Their location
- Their annual revenue
- The services they provide
- And more
When you complete our online quote form, we ask you questions to better understand your business, which helps determine the amount of coverage you may need. We offer affordable quotes from top insurers across the nation so you can compare prices to find the best policy for your business.
If you have questions, we’re here to help. Just call one of our licensed insurance agents, and they’ll point you in the right direction.
As a freelancer, we know you’re busy, so we designed our quote form to work in just 10 minutes. To help speed up the process, we ask that you have the following information at hand:
- Annual revenue estimates
- Information on any previous claims
Yes, in general, insurance requirements can differ across states, as well as industries. Fortunately, you don’t necessarily need to know the details. Our online quote form can help suggest policy options based on where you live and your line of work.
Comprehensive coverage for a freelance business owner usually includes both general liability and professional liability insurance. Together, these two policies can help cover you during common incidents, including:
- Bodily injury
- Accidents and damages
- Unintentional mistakes
- And more
We know every freelance business is different, and we encourage you to work with our licensed insurance agents to design coverage options that meet your business’s needs. Call our team or start by filling out our online quote form.
The cost of insurance can vary greatly. Our online quote form and licensed agents can help you find affordable coverage based on:
- Your business’s location
- The services you provide
- Your estimated annual revenue
- And more
Do you want to know how much business insurance may cost you? Just answer a few quick questions about your freelance business, then we’ll show you free quotes from top insurers nationwide!
As a freelancer, you probably do a little bit of everything. We understand. Let us know exactly what work you do and how often. Then we’ll suggest coverage options to protect your business.

Why Small Businesses Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

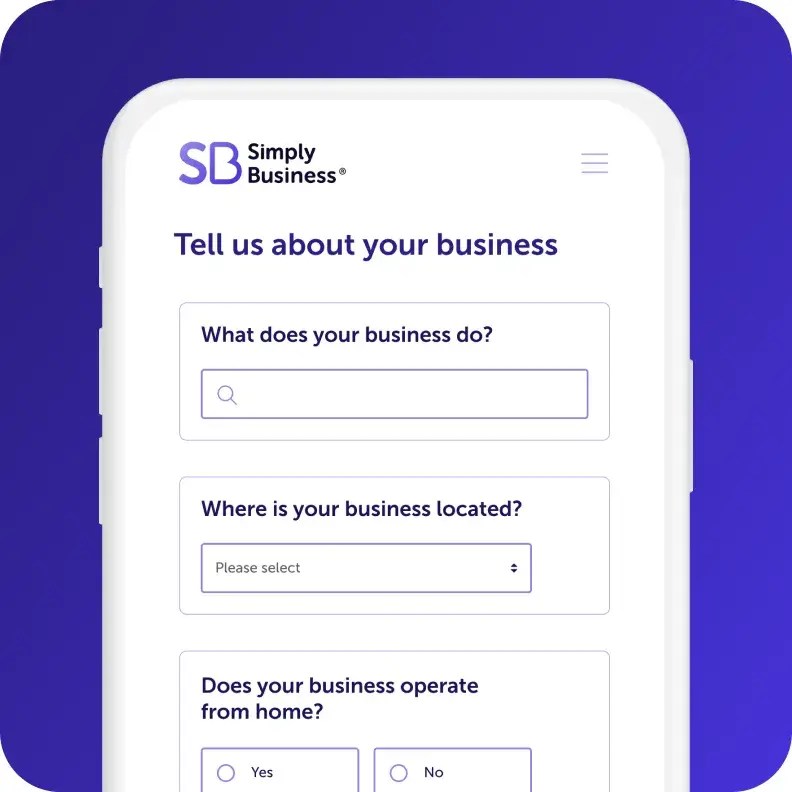
Start your quote
Answer a few questions about
your business in one form.

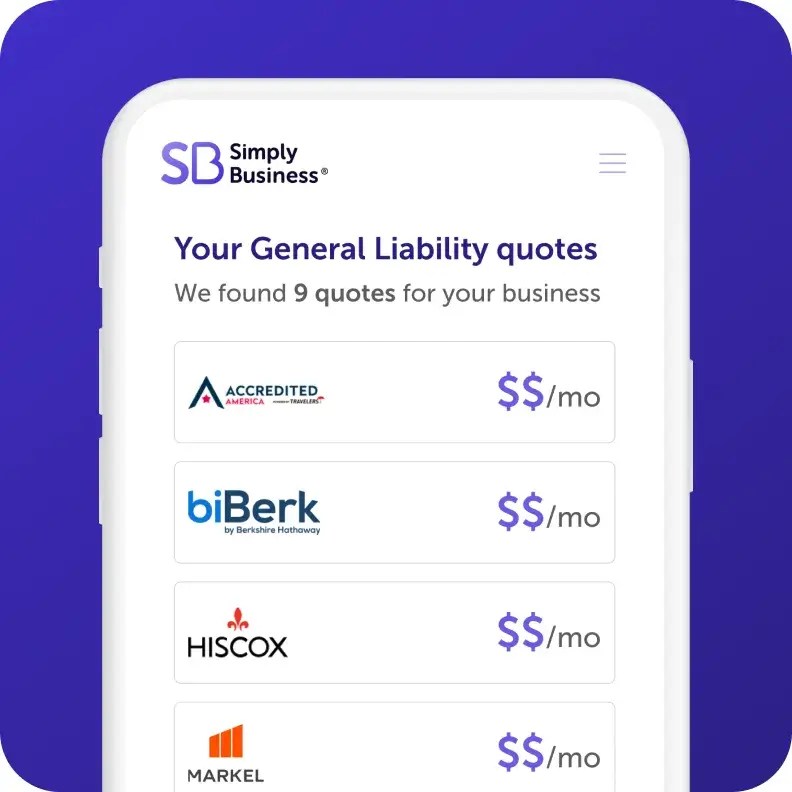
Review quotes
Compare quotes side by side from top-rated insurers and customize your coverage.

Get protected in minutes
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.

Written by
Our +1 million customers are big fans. And you will be too.

I went online, looked around, and found Simply Business. The process was so seamless. I got my certificate within minutes. It was just phenomenal.
Karen
Owner of Tangaza Bath & Body Studio LLC
With Simply Business I know I can look at different carriers, but also see all my stuff in the same place… a lot of [insurance] providers don’t offer a variety of coverage, all in one place.
Jef
Owner of Bunker83 LLC
It wasn’t overwhelming to figure out what was covered and what wasn’t covered. And the cost was competitive.

Kim
Owner of Room to Breathe Professional Organizing
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.
Page last updated: