Digital agency insurance
One application, multiple quotes.
All in one place.
Essential Protection
From
$25.83
/month*
Can provide coverage if a client claims there was a mistake in the professional services you provided.
What’s included:
Errors & Omissions / Professional Liability
Coverage limits: $100K to $3M†

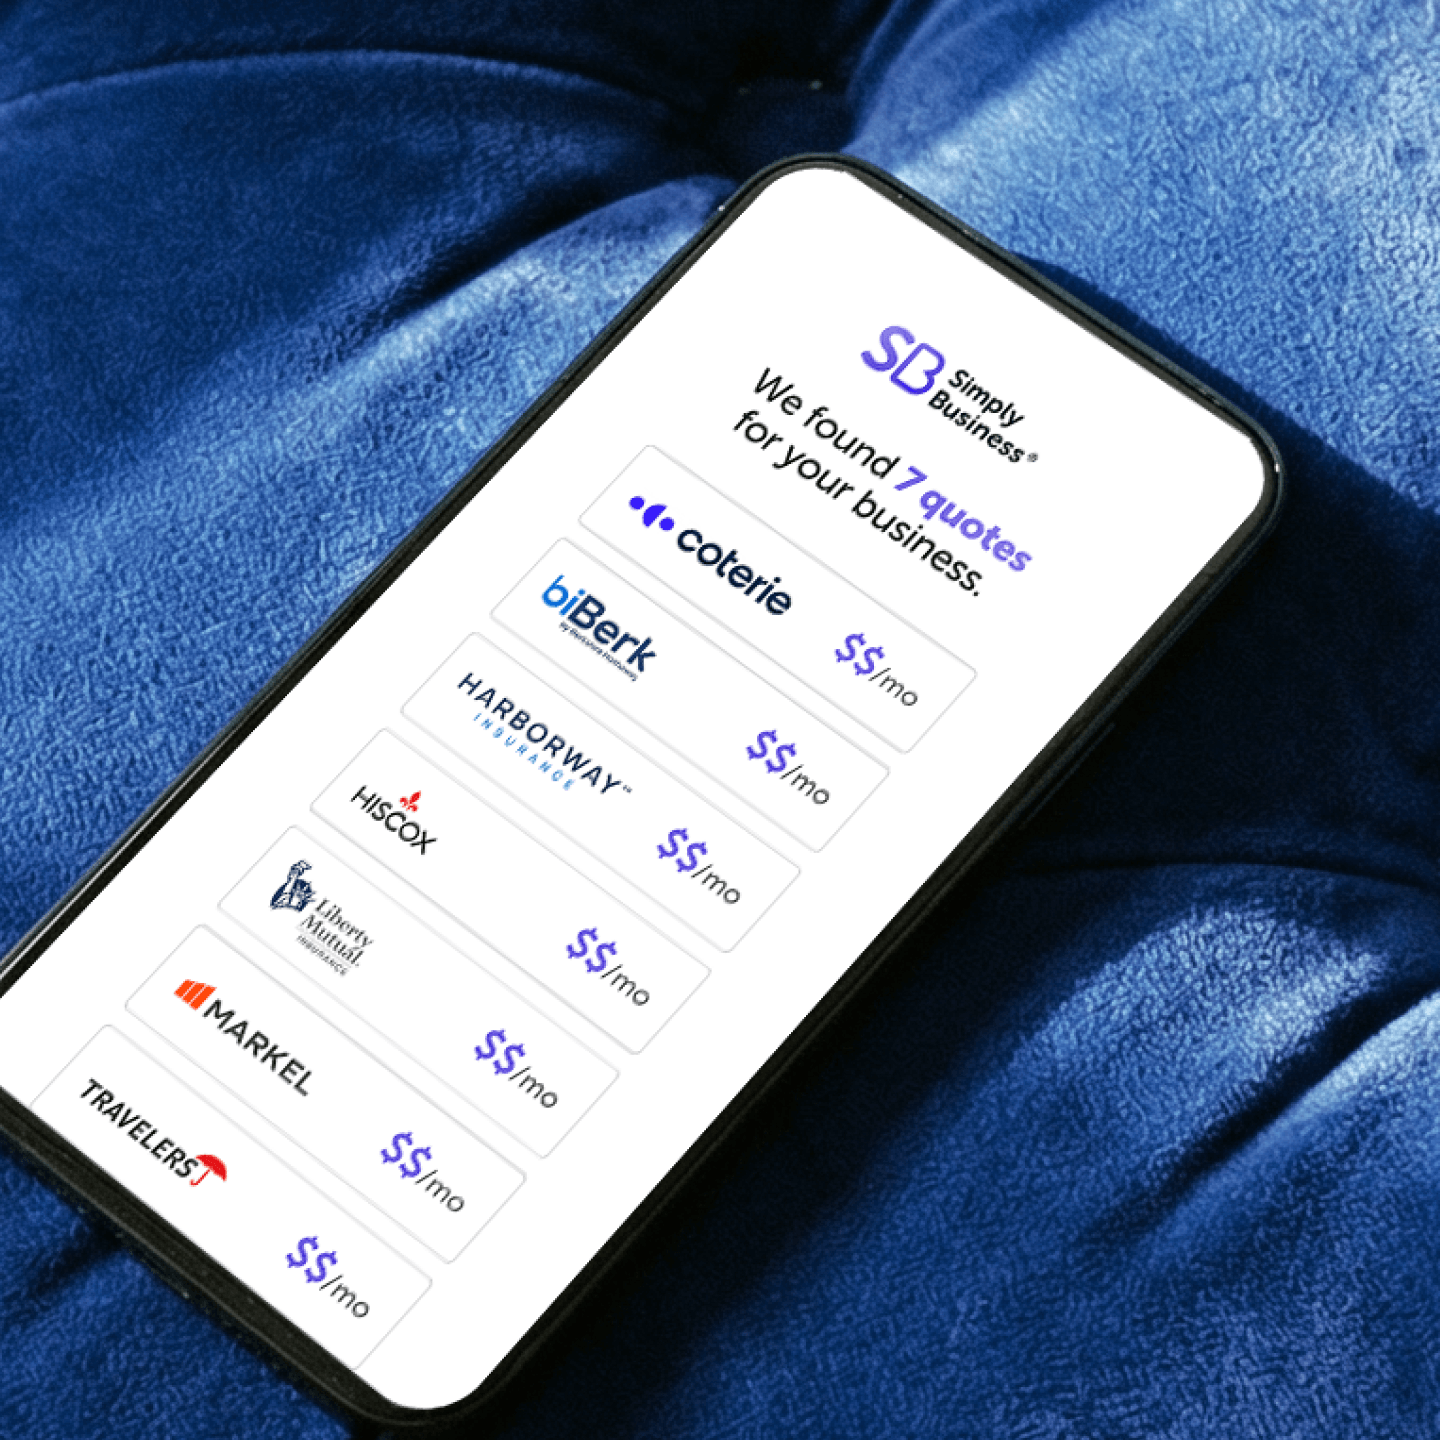
Get multiple quotes in less than 10 mins
Essential Protection
From
$25.83
/month*
Can provide coverage if a client claims there was a mistake in the professional services you provided.
What’s included:
Errors & Omissions / Professional Liability
Coverage limits: $100K to $3M†
Get multiple quotes in less than 10 mins
Would you rather pick and choose your coverage? Explore all options
Over 1 million customers worldwide.

Buy instantly online.

Written by
Why Do I Need Digital Agency Insurance?
On your best business days, you help your clients efficiently grow their business and connect with their audience. But do you have someone in your corner that can look out for you on your bad days? We can help with that.
Below are some of the most common types of insurance policies that digital agencies carry to stay protected.
What Type of Digital Agency Insurance Do I Need?

From
$25.83
/month*

General Liability
A foundational insurance coverage to help handle costs from third-party accidents, property damage, and bodily injury.
From
$20.75
/month*

Workers’ Comp
Coverage to help take care of employees who get sick or injured on the job. Most states require this coverage for small businesses with full- or part-time employees. It also can benefit business owners who don’t have employees.
From
$38.91
/month*

Business Owner’s Policy (BOP)
General liability, property insurance, and more all in one convenient package.
From
$33.75
/month*
Business insurance —
a quick explainer
Learn more about policies for small businesses, what they cover, why you might need them, and how we can help – all in just 60 seconds.
Business insurance is often made up of different types of policies to cover different things, similar to how your health insurance can be made up of medical dental and vision coverage. Here are some of the ones small business owners need. General liability is kind of the Swiss army knife of insurance. It can do a lot, like help handle costs from third party accidents, property damage, bodily injury, and more. Nobody’s perfect, right? That’s what professional liability is for. It could come in handy in the event of honest mistakes or claims of negligence. Workers’ comp can protect your business and help take care of employees who get sick or injured on the job. Small businesses are big targets for cyber criminals. Cyber Insurance can help cover costs associated with stolen customer data, cyber attacks, breaches, and fraud. BOP or a business owners policy combines different types of coverages like general liability and commercial property insurance. Putting them together for you is where we come in. You tell us a bit about your business online or on the phone, and we customize the coverage options for what you do and what you need. It’s your business, it should be your insurance as well. That’s why we’re here.
What Does Digital Agency Insurance Cover?
You have enough of those marketing acronyms, campaign goals, and strategy ideas swirling around in your head — we won’t weigh you down with unnecessary insurance information. For digital marketers looking to understand the basics of business insurance, here’s your brief on the what and how of digital agency insurance.
Professional Liability Insurance for Marketing Agencies
We don’t have to remind you that messaging is important — you’ve seen the results in real life. Since your agency has such an influence on your clients’ reputation and success, you take on extra responsibilities.
When you perform a professional service or give advice, you open yourself up to claims of negligence. That’s where professional liability insurance comes in. This type of policy covers you if a client claims that you, your employees, or your business were negligent.
As an example, imagine you’ve just hired a new intern. They help with the development of a digital marketing plan, which ends up being a bit harsh on your client’s competitors. In the shuffle of everything, the project gets approved and moves forward to production. The marketing is seen as talking badly about competition, and your client gets sued. In turn, your client sues you for negligence.
You could try to argue in court that you aren’t to blame for this, but even if you win, you’ll likely accrue legal costs. However, professional liability insurance could step in to save the day in this scenario. Your policy could potentially help offset damages so that your business could continue without having to pay the lawyer’s bill.
Let’s review the scenarios that professional liability insurance typically covers:
- Legal defense costs
- Omissions or alleged omissions
- Negligence or alleged negligence
- Claims and damages
- And more
Having professional liability insurance usually does not protect you from:
- Property damage
- Intentional acts and omissions
- Bodily injury
- Medical expenses
- And more
General Liability Insurance for Marketing Agencies
If professional liability insurance is like a specialist for your business, general liability insurance is more of a generalist. This jack-of-all-trades policy covers bodily injury, property damage, and third-party accidents. “Third parties” refer to your clients or vendors. You also may be able to add content coverage to your policy, which could offset costs if your equipment (e.g., your laptop!) is lost or stolen.
It doesn’t take much to find yourself facing an accident that could set you back thousands of dollars, even as a digital marketer. The average claim for property damage or accidents in small businesses is $30,000, which you’d likely be responsible for without insurance.
How would a calm, safe digital agency end up with such a big bill? Say a client comes to visit your office, trips over a rug, and breaks their hand trying to brace their fall. Ouch! They’re going to have medical bills, and they may sue you to get them paid.
Fortunately, you chose to get business insurance before the hypothetical scenario occurred. In this case, your policy could help pay those medical bills.
To recap, here’s what general liability insurance usually can cover:
- Bodily injury to another person
- Third-party property damage
- Personal and advertising injury
- Medical expenses
- And more
Now check out what general liability insurance usually doesn’t cover:
- Damage to your own property
- Professional services
- Workers compensation or injury to your employees
- Damage to your work
- Motor vehicles while in business use
- Expected or intentional injury or damage
- And more
Workers Compensation Insurance for Marketing Agencies
You started on your own, and now you’re here! Adding employees to your company is an exciting time, but you’ll have a few extra administrative tasks to consider. Mainly, the fact that most states require you to carry workers compensation insurance if you have part-time or full-time employees.
You can check your state laws here, or simply get your free quote to find out what coverage laws apply to you.
So what does workers comp cover? It can help cover the costs if your employees get sick or injured while working for you. Considering that the average work injury cost is $41,000, you’ll be grateful you have the coverage if you ever need it.
In general, workers compensation insurance for digital agencies can cover:
- Medical payments
- Lost wages
- Rehabilitation expenses
- Death benefits
Why Should I Get Digital Agency Business Insurance?
You’re here because you want to learn about business insurance, which means you’ve already taken the first step in protecting what you’ve built. Even though your workplace doesn’t feel risky, and you don’t think you’re doing life-altering work, every business has risks. Perhaps you aren’t sure you really need coverage or what coverage is best.
The scary fact is that 43% of small business owners polled reported being threatened with or involved in a civil lawsuit. That was across all industries, from marketers and bakers to builders and manufacturers. You’re no stranger to stats, so you might be willing to take a chance that you will never face a lawsuit.
If you want to go that route, you’ll need to be prepared to pay for any accidents that may come your way. Take a look at the most common incidents that business owners can face, including how much they cost on average:
- Reputational Harm — $50,000
- Client Injury or Damage — $30,000
- Client Slip and Fall — $20,000
As a digital marketing agency, you have another variable to consider — negligence claims. You could be the most dedicated digital marketer in town, but a disgruntled client could sue you for harming their business. No matter how careful you are, there’s a chance you’ll need to pay the thousands of dollars often associated with damages and negligence.
You also can think of getting business insurance as a strategic competitive advantage. By having a certificate of insurance (COI), you may be able to build trust with potential clients and employees. Having proof of insurance is sometimes required by landlords to rent office space too.
If you’re curious, checking out business insurance is simpler than you may think. Answer a few questions about your business, and you can compare free quotes from the country’s top insurers.

What Does Digital Agency Insurance Cost
Try our insurance calculator.
Get a quick estimate in just 3 steps.

Answers to More Digital Agency Insurance Coverage Questions
Laws about what type of insurance policies digital agencies need are set on the state level. For example, your state may require you to carry workers comp insurance if you have employees, but won’t require business insurance. Keep in mind that some landlords require GL insurance with a lease agreement.
Generally, business owners can deduct insurance premiums from their business income taxes. We always recommend talking to an accountant about your state’s laws and your specific business, though.
Your ideal level of coverage typically depends on:
- The size of your business
- Your business’s location
- Your annual revenue and payroll
- And more
You can leave the calculations up to us, though. Our quote process is designed to suggest insurance plan options based on the answers you provide.
If you have additional questions, our licensed insurance agents are available and are happy to assist you!
Getting and comparing quotes is free, so you’ll be able to weigh all of your options. If you’re ready to get your free quote, having the following materials makes the process even faster:
- Annual revenue estimates
- Payroll estimates
- Information on any previous claims
Yes, each state sets its business insurance laws. We want to save you time, so instead of digging through state websites to learn the laws, our quote process recommends options for you.
If you choose a comprehensive package that includes general liability, professional liability, and workers comp, your policy can cover:
- Bodily injury
- Accidents and damages
- Employee injuries
- Negligence or alleged negligence
- And more
Each policy is customized to a business’s needs, but generally, your premiums depend on:
- Payroll and revenue estimates
- The location of your business
- The specific services you offer
- And more
Want to see how much your digital agency insurance may cost? Just click here and get free quotes from some of the top insurers in the country.

Why Small Businesses Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

Start your quote
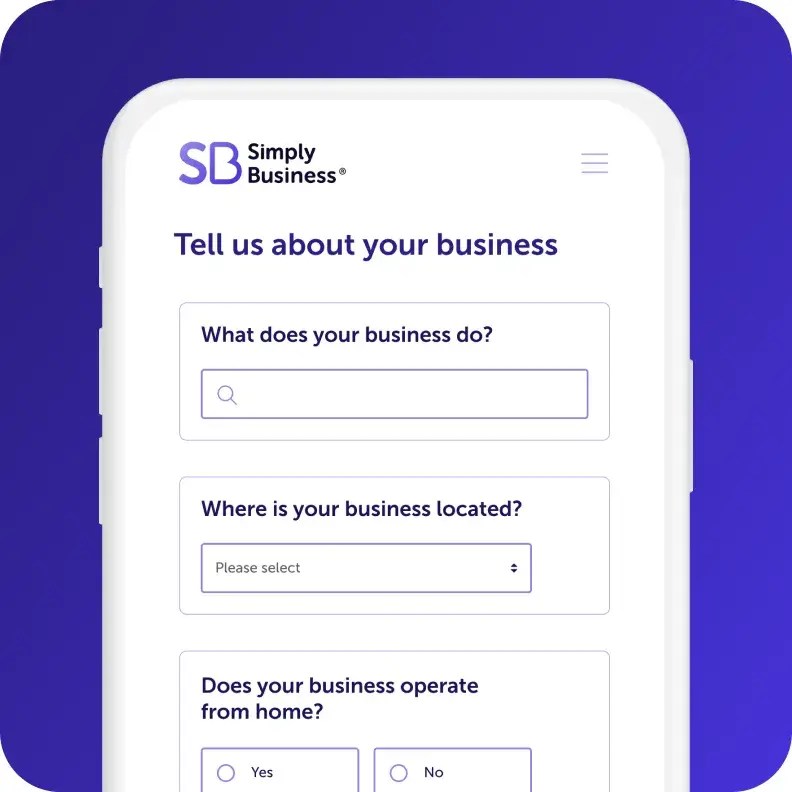
Answer a few questions about
your business in one form.

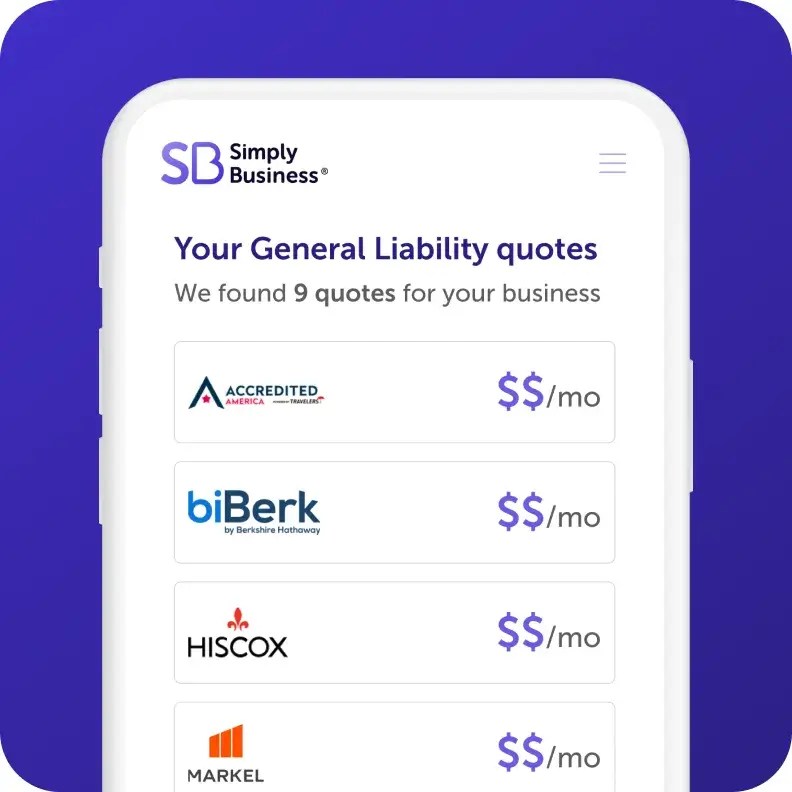
Review quotes
Compare quotes side by side from top-rated insurers and customize your coverage.

Get protected in minutes
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.

Written by
Our +1 million customers are big fans. And you will be too.

I went online, looked around, and found Simply Business. The process was so seamless. I got my certificate within minutes. It was just phenomenal.
Karen
Owner of Tangaza Bath & Body Studio LLC
With Simply Business I know I can look at different carriers, but also see all my stuff in the same place… a lot of [insurance] providers don’t offer a variety of coverage, all in one place.
Jef
Owner of Bunker83 LLC
It wasn’t overwhelming to figure out what was covered and what wasn’t covered. And the cost was competitive.

Kim
Owner of Room to Breathe Professional Organizing
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.
† Limits may vary by state and nature of your business.
Page last updated: