Electrician insurance
One application, multiple quotes.
All in one place.
Essential Protection
From
$31.25
/month*
Could help cover claims against your business for property damage and injuries to others.
What’s included:
General Liability
Coverage limits: $1M to $2M†

Get multiple quotes in less than 10 mins
Essential Protection
From
$31.25
/month*
Could help cover claims against your business for property damage and injuries to others.
What’s included:
General Liability
Coverage limits: $1M to $2M†
Get multiple quotes in less than 10 mins
Would you rather pick and choose your coverage? Explore all options
Over 1 million customers worldwide.

Buy instantly online.

Written by
Electrician Business Insurance
Electrician business insurance is a group of commercial policies, including general liability, professional liability, workers’ compensation, and tools and equipment coverage, that protects electrical contractors from the financial risks of jobsite accidents, property damage, equipment loss, and lawsuits. Simply Business lets electricians compare real quotes from multiple top-rated insurance carriers side by side, rather than purchasing from a single provider, so they can find the right coverage at a competitive price in minutes.
Whether you are a solo electrician wiring residential homes or you run a crew handling commercial installations, the coverage you need depends on your specific risks: the tools you carry, the jobsites you work on, and whether you employ staff. This guide breaks down the types of insurance electricians typically need, what they cost, and how to get a policy started today.
What Insurance Does an Electrician Need?
Most electricians need a combination of general liability insurance, tools and equipment coverage, and workers’ compensation insurance if they employ staff. Many also add a professional liability policy as their operations grow.

General Liability
A foundational insurance coverage to help handle costs from third-party accidents, property damage, and bodily injury.
From
$31.25
/month*

Contractor’s Equipment and Small Tools Insurance
Also known as inland marine insurance, this coverage can financially protect equipment and inventory that’s in transport or stored offsite.
From
$20.83
/month‡

Workers’ Comp
Coverage to help take care of employees who get sick or injured on the job. Most states require this coverage for small businesses with full- or part-time employees. It also can benefit business owners who don’t have employees.
From
$38.91
/month*
What Does Electrician Insurance Cover?
When you’re dealing with live wires, tight spaces, and demanding projects, even the smallest slip could short-circuit your business. We’re here to help you find coverage to protect against some of the common risks you may face:
While installing a new outlet, you drill into a wall and accidentally puncture a large hole in the drywall. The homeowner asks you to pay for the repairs. A general liability policy could help cover those types of third-party claims.
You’ve landed a large commercial electrical wiring project, but the customer requires proof that the work will be completed on time and up to code. That’s where a surety bond can come in. It’s a financial guarantee that protects your client if you can’t meet your contractual obligations. If the job isn’t finished on time or doesn’t meet agreed-upon standards, the bond can compensate the customer for their losses.
Even the most experienced electricians can make mistakes. After installing a new circuit breaker, a loose connection causes a power surge that damages the client’s brand-new appliances. Adding a contractor’s errors and omissions endorsement to your general liability insurance could help cover the cost of repairs for completed work and help protect you in the event of a negligence claim.
Your crew is tackling a tricky exterior job when one of your electricians slips off a scaffold and injures his back. Workers’ compensation insurance can help cover their medical bills and provide wage replacement as they recover.
Workers’ comp is often legally required and can protect your business from costly claims, as well as taking care of your crew if they get sick or injured on the job. Even if you operate solo, we recommend workers’ comp, since many health insurance policies may not cover work-related injuries.
After finishing a long day on the job, you find your truck has been broken into — your cordless drills, multimeter, and fish tape set are missing. Contractor’s equipment and small tools insurance, also known as inland marine insurance, can help pay to replace or repair your stolen or damaged equipment — whether it’s on the move or at a jobsite.
How Much Does Electrician Insurance Cost?
Most electrician businesses pay a median price of $41 per month for small business insurance coverage. Your final premium will depend on factors like your location, number of employees, specific work you do, and your claims history.
Here’s a look at the median costs1 for the most common policies electrician businesses purchase from Simply Business:
| Insurance Type | Estimated Median Monthly Price |
| General liability | $36 |
| Business owner’s policy (BOP) | $47 |
| Workers’ compensation | $108 |
| Inland marine | $27 |
| Professional liability | $41 |
1Data from Simply Business customers specializing as a “electrician” who purchased at least one or a combination of general liability, BOP, tools and equipment, workers’ compensation, or professional liability policies from July 1, 2025 to December 31, 2025. Reflected price tiers may not include purchase of all available policies under plumber insurance.
Because Simply Business works with eighteen leading carriers, including Hiscox, Markel, and Liberty Mutual, electricians can compare pricing and coverage options side by side instead of accepting the first quote they receive.

Get Electrician Insurance Quotes
Try our Electrician insurance Calculator
Get a quick estimate in just 3 steps.
Answers to More Electrician Insurance Coverage Questions
Most states require you to carry workers’ compensation insurance if you have employees. There also may be licensing requirements that require certain liability coverages. We recommend checking with your state and local governments regarding the required coverages.
General liability insurance for electricians covers third-party bodily injury, property damage, and the associated legal costs that arise from your business operations. For example, if a client slips on a cord you left on their floor, or your work accidentally starts an electrical fire that damages their property, general liability is typically the policy that helps cover the resulting claim.
General liability does not cover your own tools, equipment, or vehicles, and it generally does not cover claims that your electrical work itself was faulty. Those risks are addressed separately through tools and equipment coverage and professional liability insurance, respectively.
Standard general liability insurance does not cover your tools and equipment; you need a separate tools and equipment policy, often called inland marine insurance, for that protection. This coverage reimburses you if your tools are stolen from your van, damaged on a jobsite, or lost in transit between job sites.
Given how dependent electricians are on specialized tools, many business owners add this coverage alongside general liability from the start rather than waiting until after a loss occurs.
Yes. Simply Business allows electricians to compare and purchase coverage entirely online without requiring a broker, and you can get instant proof of coverage once your policy is active.
Professional liability insurance, not general liability, typically covers claims that your electrical work was faulty or caused a loss due to an error in your services. If a client later alleges your wiring work caused damage due to a mistake on your part, this is the policy most likely to respond.
Most electricians can receive instant proof of coverage online as soon as their policy is purchased, which means you can meet a jobsite or client requirement the same day rather than waiting on a broker.

Why Small Businesses Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

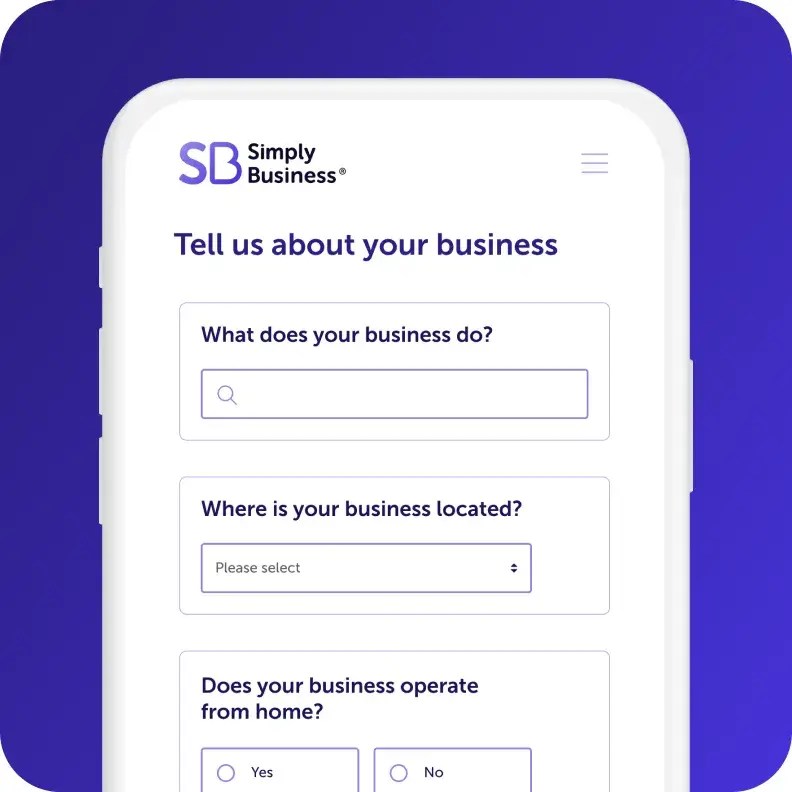
Start your quote
Answer a few questions about
your business in one form.

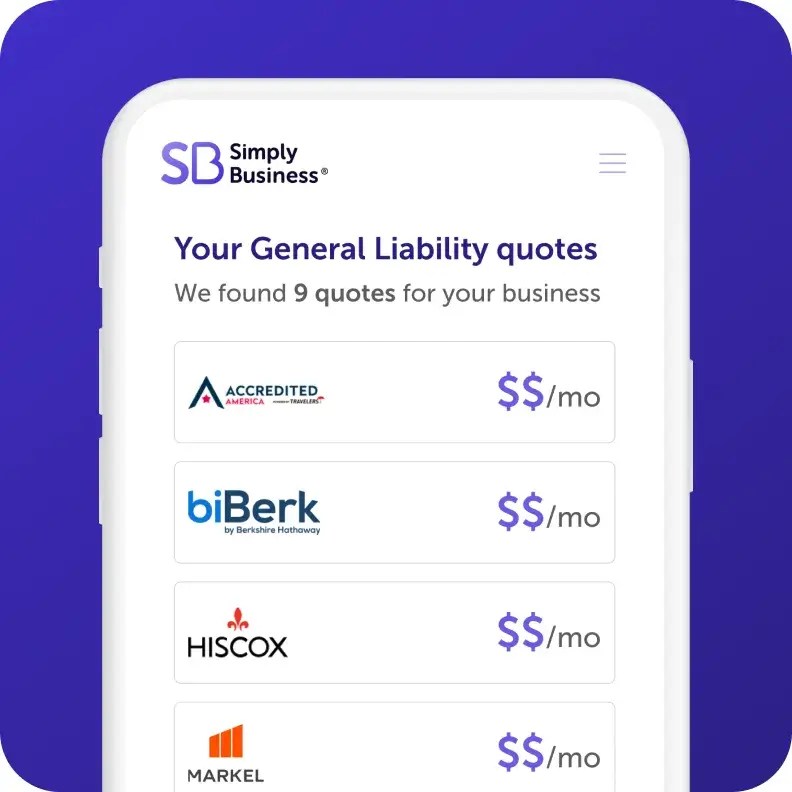
Review quotes
Compare quotes side by side from top-rated insurers and customize your coverage.

Get protected in minutes
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.

Written by
Our +1 million customers worldwide are big fans. And you will be too.
I went online, looked around, and found Simply Business. The process was so seamless. I got my certificate within minutes. It was just phenomenal.
Karen
Owner of Tangaza Bath & Body Studio LLC
With Simply Business I know I can look at different carriers, but also see all my stuff in the same place… a lot of [insurance] providers don’t offer a variety of coverage, all in one place.
Jef
Owner of Bunker83 LLC
It wasn’t overwhelming to figure out what was covered and what wasn’t covered. And the cost was competitive.

Kim
Owner of Room to Breathe Professional Organizing
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.
† Limits may vary by state and nature of your business.
‡ Displayed price is based on the lowest available coverage limit for Equipment and Small Tools policies.
Page last updated: