
Professional Services Insurance
Compare quotes for consultants, freelancers, and professional service providers.

Trusted by +1M small business owners worldwide
No junk mail. No spam calls. Free quotes.
Buy instantly online
Find your trade
If clients pay you for your advice, skills, or specialized services, this page can help you find coverage built for the work you do. Select your profession below for tailored guidance or start with the coverage types most professional service businesses consider: professional liability (E&O), general liability, a business owner’s policy (BOP), cyber liability, and workers’ compensation.
Financial & Legal


Creative & Digital


Advisory & Consulting


Events & Lifestyle


Other Professions We Cover


Written by
What Insurance Do Professional Service Businesses Need?
Professional service businesses generally face are claims about the work itself — a mistake, a missed deadline, advice that didn’t pan out — and everyday accidents such as a client slipping and falling in your office. Different policies address each different types of risk, which is why many professionals carry more than one insurance coverage.
More than four out of five U.S. small businesses are businesses of one — freelancers, independent consultants, and home-based professionals. So if it’s just you, you’re not the exception — you’re the market. And running small doesn’t mean insuring small: You can compare coverage from the same top-rated insurers that protects far larger companies, and buy it in minutes. Your personal homeowner’s insurance policy typically excludes business-related claims, and many clients ask for proof of insurance before signing a contract — so having appropriate coverage for the services you provide can help you win work, not just protect it.
And here’s the part nobody tells you: Even professionals have a bad day now and then. The point of coverage isn’t perfection — it’s making certain a bad day stays just a bad day.
Professional liability insurance — also named errors and omissions insurance (E&O) — can help cover the cost of defending and resolving claims that your work or advice caused a client financial harm (or, for certain hands-on professions, physical harm). For businesses built on expertise, it’s usually the foundational policy, and the one client contracts most often require.
Best for: Consultants, accountants, designers, IT professionals, and anyone paid for advice, analysis, or professional services.
Professional liability insurance can help with claims involving:
- Errors made by your employees or subcontractors
- Negligence or alleged mistakes regarding in your work
- Missed deadlines or failure to deliver promised results
- Inaccurate advice or analysis that costs a client money
General liability insurance addresses the physical risks of doing business. Even a desk-based operation meets clients, visits their offices, and advertises its services — general liability coverage lets you do all of it with confidence that an every-day accident won’t derail the business you’ve built.
Best for: Any professional who meets clients in person, works on-site, rents an office, or wants baseline protection most commercial leases and contracts expect.
General liability insurance typically covers claims involving:
- Third-party bodily injury, such as a client slipping and falling in your office
- Damage to someone else’s property, such as accidentally damaging a client’s office furniture
- Personal and advertising injury, such as alleged libel or slander
A detail worth knowing:
Most general liability policies also include a small medical payments coverage that can pay a minor injury bill, regardless of who was at fault — a quiet piece of the policy designed to keep small accidents small.
A business owner’s policy bundles general liability with commercial property coverage, often at a lower combined price than buying each separately. If your laptop is your office and your equipment is your livelihood, a BOP can help protect both your gear and your liability exposure in one policy. A simple rule of thumb: if you’d buy general liability insurance anyway and you own more than a laptop, price the BOP first — it’s often the more economical path to both of them.
Best for: Professionals with an office, studio, or valuable business equipment who want liability and property protection together.
A BOP can help with claims and losses involving:
- Lost income if a covered event interrupts your operations
- Third-party bodily injury or property damage
- Damage to or loss of your business property and equipment
If you store client records, process payments, or access clients’ systems, cyber liability insurance can help you respond to a data breach, ransomware attack, or other covered cyber incident — and keep the client trust you’ve earned.
Best for: IT consultants, accountants, financial planners, marketers, and any professional who handles sensitive client data or digital systems.
Cyber liability insurance may help pay for:
- Liability claims from clients whose data was compromised
- Data breach response, including client notification and credit monitoring
- Ransomware and cyber extortion losses
Most states require workers’ compensation insurance by law when you hire employees — in many, starting with your first hire, even part-time. Requirements vary by state, so check the rules where you operate. Sole proprietors generally aren’t required to carry it for themselves, (though certain states may mandate it regardless of employee count for specific higher-risk trades).
For businesses with employees, this is the coverage that takes care of both you and your team — supporting an employee’s recovery while helping protect the business along the way.
Best for: Professional service businesses with employees, and sole proprietors whose client contracts require coverage.
Workers’ compensation insurance typically covers:
- Employer liability if an injured employee sues your business
- Medical expenses for work-related employee injuries or illnesses
- Partial coverage for lost wages while an employee recovers
If you use AI in your client work
More professional service businesses are using AI tools in the work they deliver — drafting analyses, writing code, automating research. The insurance industry is still working out how to handle claims involving AI-assisted work. Some insurers have started adding AI-specific exclusions to standard policies, while others are building coverage designed for AI-related risks. Whether a policy would respond to that kind of claim often comes down to its exact wording.
If you want to know whether your policy will cover the work you do through AI tools, you’ll need to ask your agent about what exactly is in your policy. If AI plays a role in what you deliver to clients, ask how a policy treats AI-assisted work when you compare quotes, and revisit the question at each renewal — wording in this area is changing quickly. Keeping a documented human review step in your process is good practice too.
General Liability vs. Professional Liability: What’s the Difference?
The simplest way to remember it: general liability responds to accidents; professional liability responds to your work.
- General liability applies when your business is blamed for physical harm – a client trips over your laptop bag or you damage property at a client’s office.
- Professional liability (E&O) applies when a client says your work or advice caused them financial harm – a calculation error, a missed deadline, a recommendation that backfired. Professional liability generally won’t respond to third-party bodily injury or property damage claims.
Because the two policies address entirely different risks, many professional service businesses carry both – and client contracts often require both, each with specified minimum limits.
How Much Does Professional Services Insurance Cost?
Here’s a look at the median monthly cost1 for professional services business insurance:
| Policy | Median Monthly Cost1 |
|---|---|
| General Liability | $29 |
| Workers’ Compensation | $102 |
| Tools and Equipment | $27 |
1Data from Simply Business customers who identified as a “professional services” business and purchased either a professional liability or general liability policy from July 1, 2025 to December 31, 2025. Median costs shown are for illustrative purposes only; actual premiums vary by state, coverage limits, and individual business risk.
A few factors drive your rate more than others: the type of advice or services you provide, your revenue and team size, where you operate, the policy limits you select, and your claims history, among other factors. Higher limits typically cost more in annual premium but provide more protection — a $1 million limit is a common choice for small professional service businesses and often the minimum client contracts specify. General liability and BOP pricing follows the same logic; see our general liability cost guide for those figures. The most reliable way to know your cost is to compare quotes for your specific business.
Frequently Asked Questions
General liability typically covers physical risks — bodily injury and property damage — while professional liability covers the financial harm a client blames on your work or advice. Many businesses carry both, because these policies are designed to cover distinct types of claims.
While it’s generally rare that a statute or local regulation require that someone carry a general or professional liability policy, many freelancers and independent consultants choose coverage to protect their work and meet client requirements. Even a solo business can face a claim, and legal defense costs can be significant, even when a claim lacks merit. Clients also may ask for proof of insurance before signing a contract, so coverage can be the difference between winning work and losing it.
Errors and omissions (E&O) insurance is another name for professional liability insurance — the terms are used interchangeably, with E&O more common in some professions. It can help cover legal defense costs, adjudicated damages, and settlements when a client claims your work, advice, or oversight caused them financial or physical harm.
Working from home doesn’t necessarily mean your homeowner’s policy covers business-related claims — many policies exclude them. It’s worth reviewing your policy and considering business coverage if clients visit your home office, you work at client locations, or your services could lead to a claim. Home-based professionals often begin with professional liability and general liability, then add other coverage as they grow.
Check the contract’s insurance clause for the required coverage types and minimum limits — $1 million per occurrence is a common ask — then compare quotes that meet or exceed those numbers. Once you purchase a policy through Simply Business, you can typically download a Certificate of Insurance the same day to send your client the proof of coverage.
If your business stores client records, processes payments, or connects to clients’ systems, cyber insurance is worth serious consideration. Businesses that hold sensitive client data face real cyber exposure, and breach response costs — notification, recovery, potential legal claims — can add up quickly. Some clients in regulated industries may also ask for it before you begin work.
Simply Business customers typically pay a median of $42 per month for professional liability insurance, with rates varying by profession, location, coverage limits, and claims history.² Lower-risk work such as bookkeeping or coaching often costs less; higher-stakes advisory work can cost more. See our professional liability cost guide for detailed figures, or get a quote for a price specific to your business.
Why Small Businesses Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

Start your quote
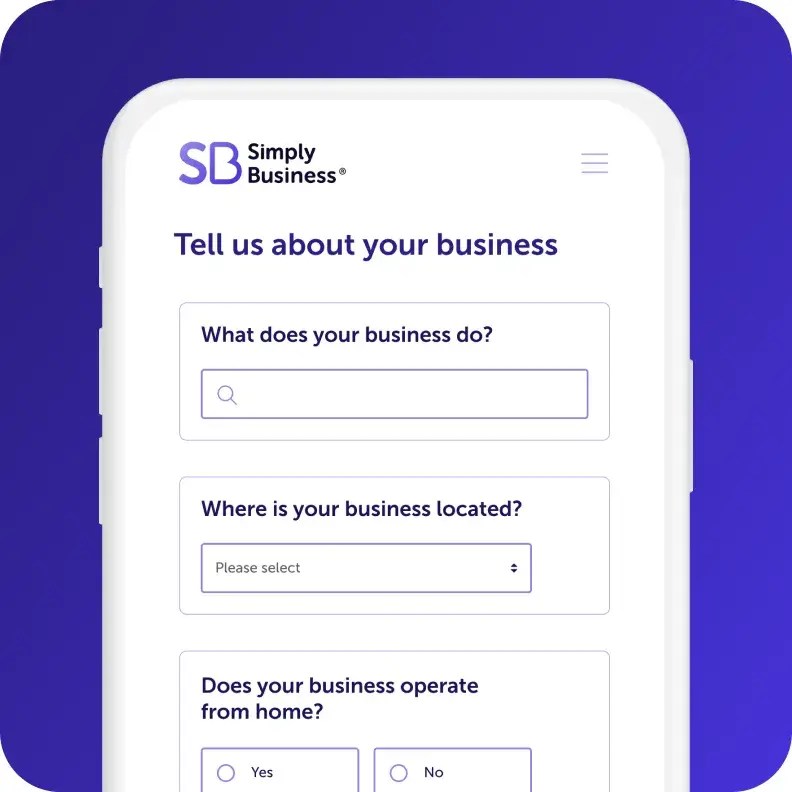
Answer a few questions about
your business in one form.

Review quotes
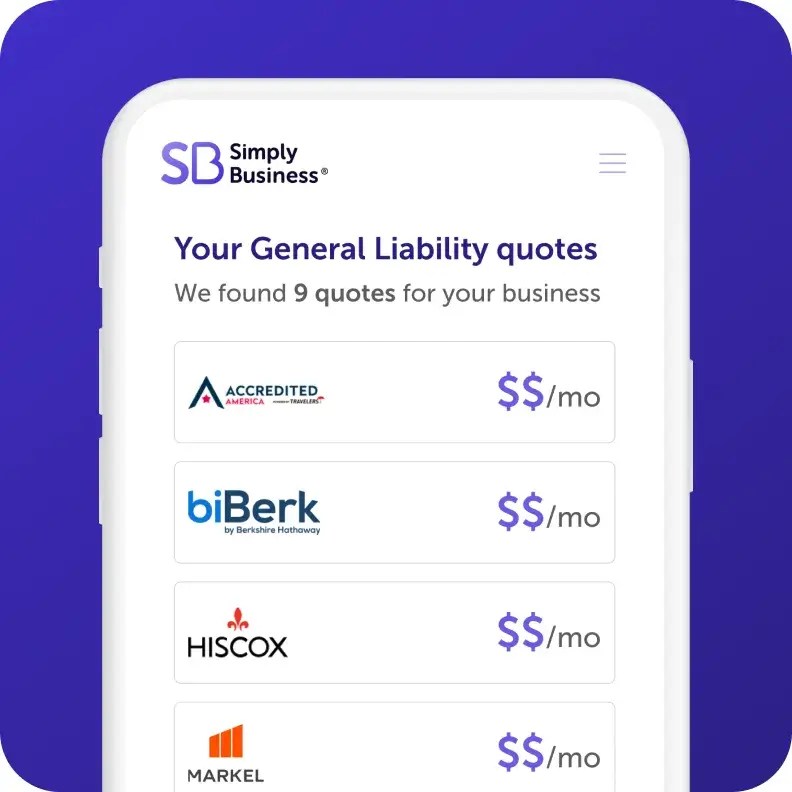
Compare quotes side by side from top-rated insurers and customize your coverage.

Get protected in minutes
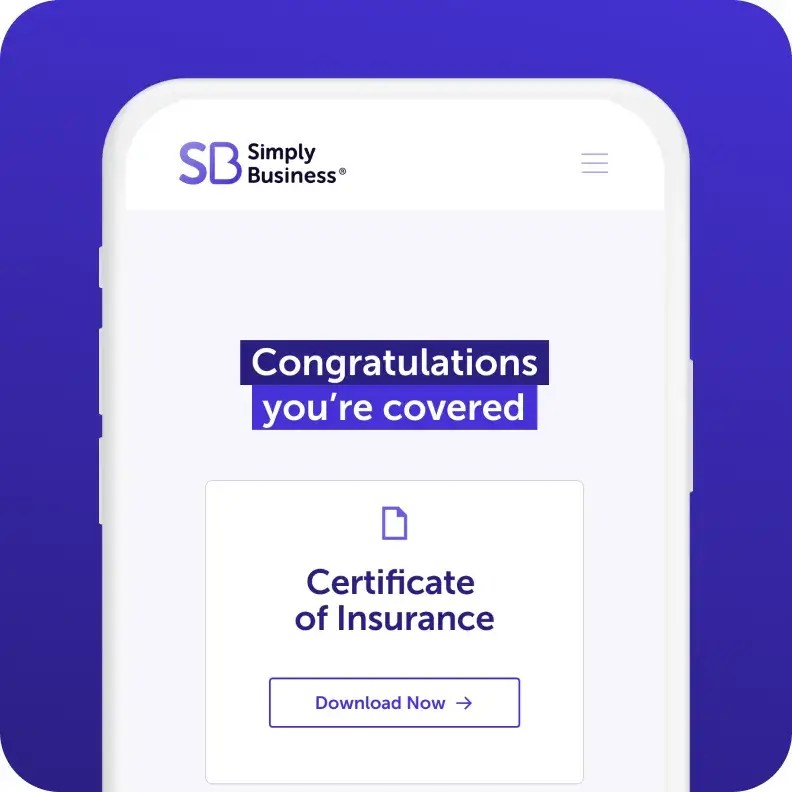
Purchase your policy, and get instant proof of insurance – all online, and all within 10 minutes.
Our +1 million customers worldwide are big fans. And you will be too.
Trusted by over one million small business owners globally, Simply Business makes it easy to compare options and choose coverage with confidence. Read our customer reviews to see what they say about their experience.

Fair price, explained everything. I was finished with Simply Business before any other companies answered.

Natalie B.
Housekeeping, Idaho
With Simply Business I know I can look at different carriers, but also see all my stuff in the same place… a lot of [insurance] providers don’t offer a variety of coverage, all in one place.
Jef
Owner of Bunker83 LLC
Site was easy to follow. Covered what i needed. Cost was reasonable and quick process.
Tracie R.
Janitorial services, North Carolina
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.