Appraiser Insurance
Find out what insurance coverage you need as an appraiser.
Compare policies from leading national insurers. Get a quote in minutes.

Over 1 million customers worldwide.

Buy instantly online.

Written by
Why Do I Need Appraiser Insurance?
You love your job as an appraiser. And why wouldn’t you? You’re met with exciting opportunities every day. Whether you’re appraising jewelry, collectibles, or family heirlooms, informing clients that their items are of high value is always rewarding. Your business is valuable too.
Below are some of the most common types of insurance policies that appraisers carry to stay protected.
What Type of Appraiser Insurance Do I Need?

General Liability
A foundational insurance coverage to help handle costs from third-party accidents, property damage, and bodily injury.
From
$20.75
/month*

Business Personal Property
Coverage to replace or repair equipment, furniture, fixtures, and inventory.
Business insurance —
a quick explainer
Learn more about policies for small businesses, what they cover, why you might need them, and how we can help – all in just 60 seconds.
Business insurance is often made up of different types of policies to cover different things, similar to how your health insurance can be made up of medical dental and vision coverage. Here are some of the ones small business owners need. General liability is kind of the Swiss army knife of insurance. It can do a lot, like help handle costs from third party accidents, property damage, bodily injury, and more. Nobody’s perfect, right? That’s what professional liability is for. It could come in handy in the event of honest mistakes or claims of negligence. Workers’ comp can protect your business and help take care of employees who get sick or injured on the job. Small businesses are big targets for cyber criminals. Cyber Insurance can help cover costs associated with stolen customer data, cyber attacks, breaches, and fraud. BOP or a business owners policy combines different types of coverages like general liability and commercial property insurance. Putting them together for you is where we come in. You tell us a bit about your business online or on the phone, and we customize the coverage options for what you do and what you need. It’s your business, it should be your insurance as well. That’s why we’re here.
What Does Appraiser Insurance Cover?
You’re an expert when it comes to assessing an item’s worth. You study it with meticulous care, taking note of every detail. You research market trends and assign value to them. You run your business like clockwork, and your clients are often delighted when they learn their item is worth more than they expected.
Of course, there’s the other side of the coin. You never know when you may encounter a disgruntled client who isn’t happy or doesn’t agree with your appraisal. Even when you do your job by the book, you may experience an unexpected turn of events resulting in an insurance claim.
That’s why insurance for appraisers is so crucial.
There are risks with every type of small business. Even the most diligent business owner can make a mistake, so you need to be prepared. Depending on the nature of your business, you may need more than one policy. We can help you determine the type of coverage you may want to consider for your appraisal business.
Here are two types of policies we typically recommend:
General Liability Insurance
Jewelry, coins, china, musical instruments, and artwork. These may be some of the treasured items you specialize in and assess daily. Items like these can be worth a lot of money. As an appraiser with valuable items in your possession, you’re likely at risk for theft, damage, or loss.
Sometimes your clients bring you personal items to be appraised for insurance purposes. Once the items are in your possession, it makes sense that you likely need insurance too. You can help protect yourself and your business from potential loss with general liability insurance.
Imagine a situation like this. A client brings you a vintage Fender Stratocaster guitar that he received as part of an inheritance. It’s in pristine condition and may be worth over $25,000. You need to keep it in your office for several days so you can inspect it and do some research.
While reaching for a book on a shelf, you accidentally knock over a stack of heavy binders, and they fall on the guitar, causing a significant dent in the instrument’s body. It’s an unfortunate accident, but the damage is done — and you are financially responsible for it.
Without insurance, the cost of that damaged guitar would come out of your own pocket. And that may leave you singing the blues. Property damage claims for small businesses can be significant. The average claim is a hefty $30,000.
But if you had general liability insurance, the cost of the damaged guitar could be covered by your policy, up to its limits. With a GL policy, you could be financially covered for a variety of mishaps, including third-party accidents, and third party property damage and bodily injury.
Here’s what general liability insurance usually covers:
- Third-party bodily injury
- Third-party property damage
- Personal and advertising injury
- Claims arising from product defects
- Medical expenses
- And more
GL insurance usually doesn’t cover:
- Damage to your own property
- Professional services
- Workers compensation or injury to your employees
- Damage to your work
- Automobiles while in business use
- Expected or intentional injury or damage
- And more
Business Personal Property Insurance
As an appraiser, you worry about theft or damage when it comes to your clients’ valuable property. But what about your personal property?
Let’s return to your office mishap. What if — in addition to the falling binders — the entire shelf came crashing down, damaging your desk and filing cabinet? Now you have the financial burden of replacing your office furniture.
That’s where business personal property insurance comes in. When you add it to your appraisal insurance, it can help with the cost of replacing those essential office items.
Business personal property (BPP) insurance typically covers the equipment, furniture, fixtures, and inventory you own, use, or rent inside your workspace.
For a business owner, business personal property insurance can help pay to replace office furniture, computers, cameras, or other essential equipment in the event they’re stolen, damaged, or destroyed.
A BPP policy can cover financial claims involving:
- Theft of business property
- Damage to business property
- Loss of business property
- And more
For small business owners, stolen equipment or property damage can affect their daily operations. If someone steals your security camera, it creates a safety concern, putting your business and clients at risk. With business personal property coverage, the cost of your security camera could be covered, and you could return to running your business worry-free.
Why Do I Need Appraisal Insurance?
You never know when a good day may turn bad. Let’s say one of your apprentice appraisers overestimates the value of a piece of jewelry by several thousand dollars. If the error is later discovered, you could be at risk — and a claim could be filed against your business.
It’s not uncommon for a small business to be sued. According to the Small Business Administration, between 36%-53% of small businesses may encounter a lawsuit in a given year. And the legal costs for those small businesses could range anywhere from $3,000 to $150,000. Your small business likely can’t afford to take a hit like that.
When mistakes happen, appraiser insurance can help protect you financially if you find yourself involved in a lawsuit or having to pay a claim.
Peace of mind is just one reason to get coverage. Having appraisal insurance sends a message that your business is reputable. Your clients may feel more confident trusting you with their personal belongings. Obtaining insurance for appraisers is a great way to protect yourself while providing valuable services to your clients.
Answers to More Appraiser Insurance Coverage Questions
Whether or not you need appraisal insurance may depend on where you live. Check with your local government to find out what’s required in your area.
If you have part-time or full-time employees, you’ll likely need to carry workers compensation insurance.
Additionally, it’s possible you may need proof of business insurance to run your appraisal business or rent office space or equipment.
You may be able to deduct your insurance premiums when filing your business’s taxes. We recommend checking with an accountant for more information on what business expenses are tax-deductible for your specific business.
How much appraisal insurance coverage will I need?
The amount of coverage you’ll need will largely depend on factors such as:
- The size of your business
- Your business’s location
- Your annual revenue
- And more
Our quote form and our licensed insurance agents will gather enough information to help find you coverage for your appraisal business. Plus, if you have questions, our insurance pros are there to assist!
To get your appraiser insurance quote quickly, it’s helpful to have the following information handy:
- Your annual revenue estimates
- Information on any previous insurance claims
A comprehensive solution that includes both general liability and business personal property insurance can cover:
- Third-party bodily injury
- Third-party accidents and damages
- Theft, damage, and loss of business property
- And more
This is a similar question to “How much is this painting worth?” It often depends on a number of factors. As a general rule of thumb, you can expect the cost of your policy to be determined by:
- Your revenue
- Your payroll
- Number of employees
- Your business location
- The type of services you provide
- And more
You can get business personal property coverage as an addition to your general liability (GL) insurance.
Curious to see how much your appraiser liability insurance may cost? Just click here to answer a few easy questions and get free quotes to compare policies.

Why Small Businesses Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

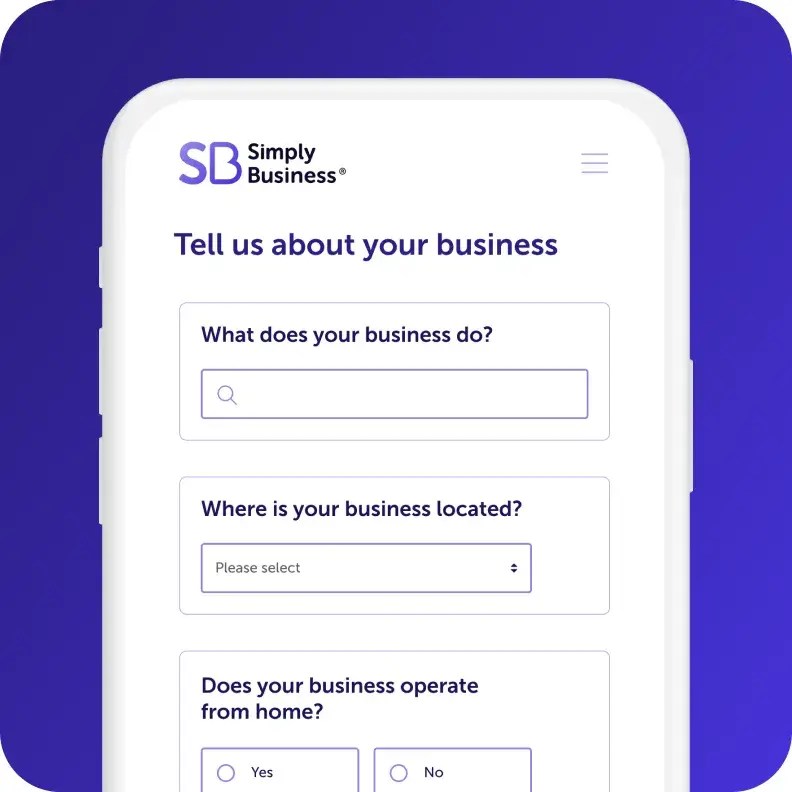
Start your quote
Answer a few questions about
your business in one form.

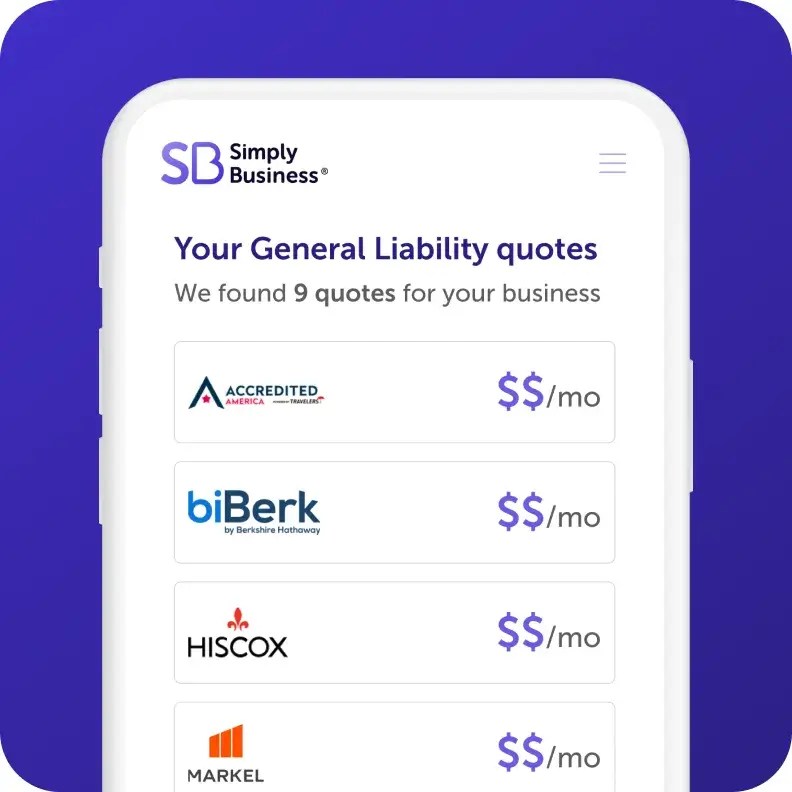
Review quotes
Compare quotes side by side from top-rated insurers and customize your coverage.

Get protected in minutes
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.

Written by
Our +1 million customers are big fans. And you will be too.

I went online, looked around, and found Simply Business. The process was so seamless. I got my certificate within minutes. It was just phenomenal.
Karen
Owner of Tangaza Bath & Body Studio LLC
With Simply Business I know I can look at different carriers, but also see all my stuff in the same place… a lot of [insurance] providers don’t offer a variety of coverage, all in one place.
Jef
Owner of Bunker83 LLC
It wasn’t overwhelming to figure out what was covered and what wasn’t covered. And the cost was competitive.

Kim
Owner of Room to Breathe Professional Organizing
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information
9-minute read
A General Liability Insurance Guide for Small Business
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.
† Limits may vary by state and nature of your business.