Café insurance
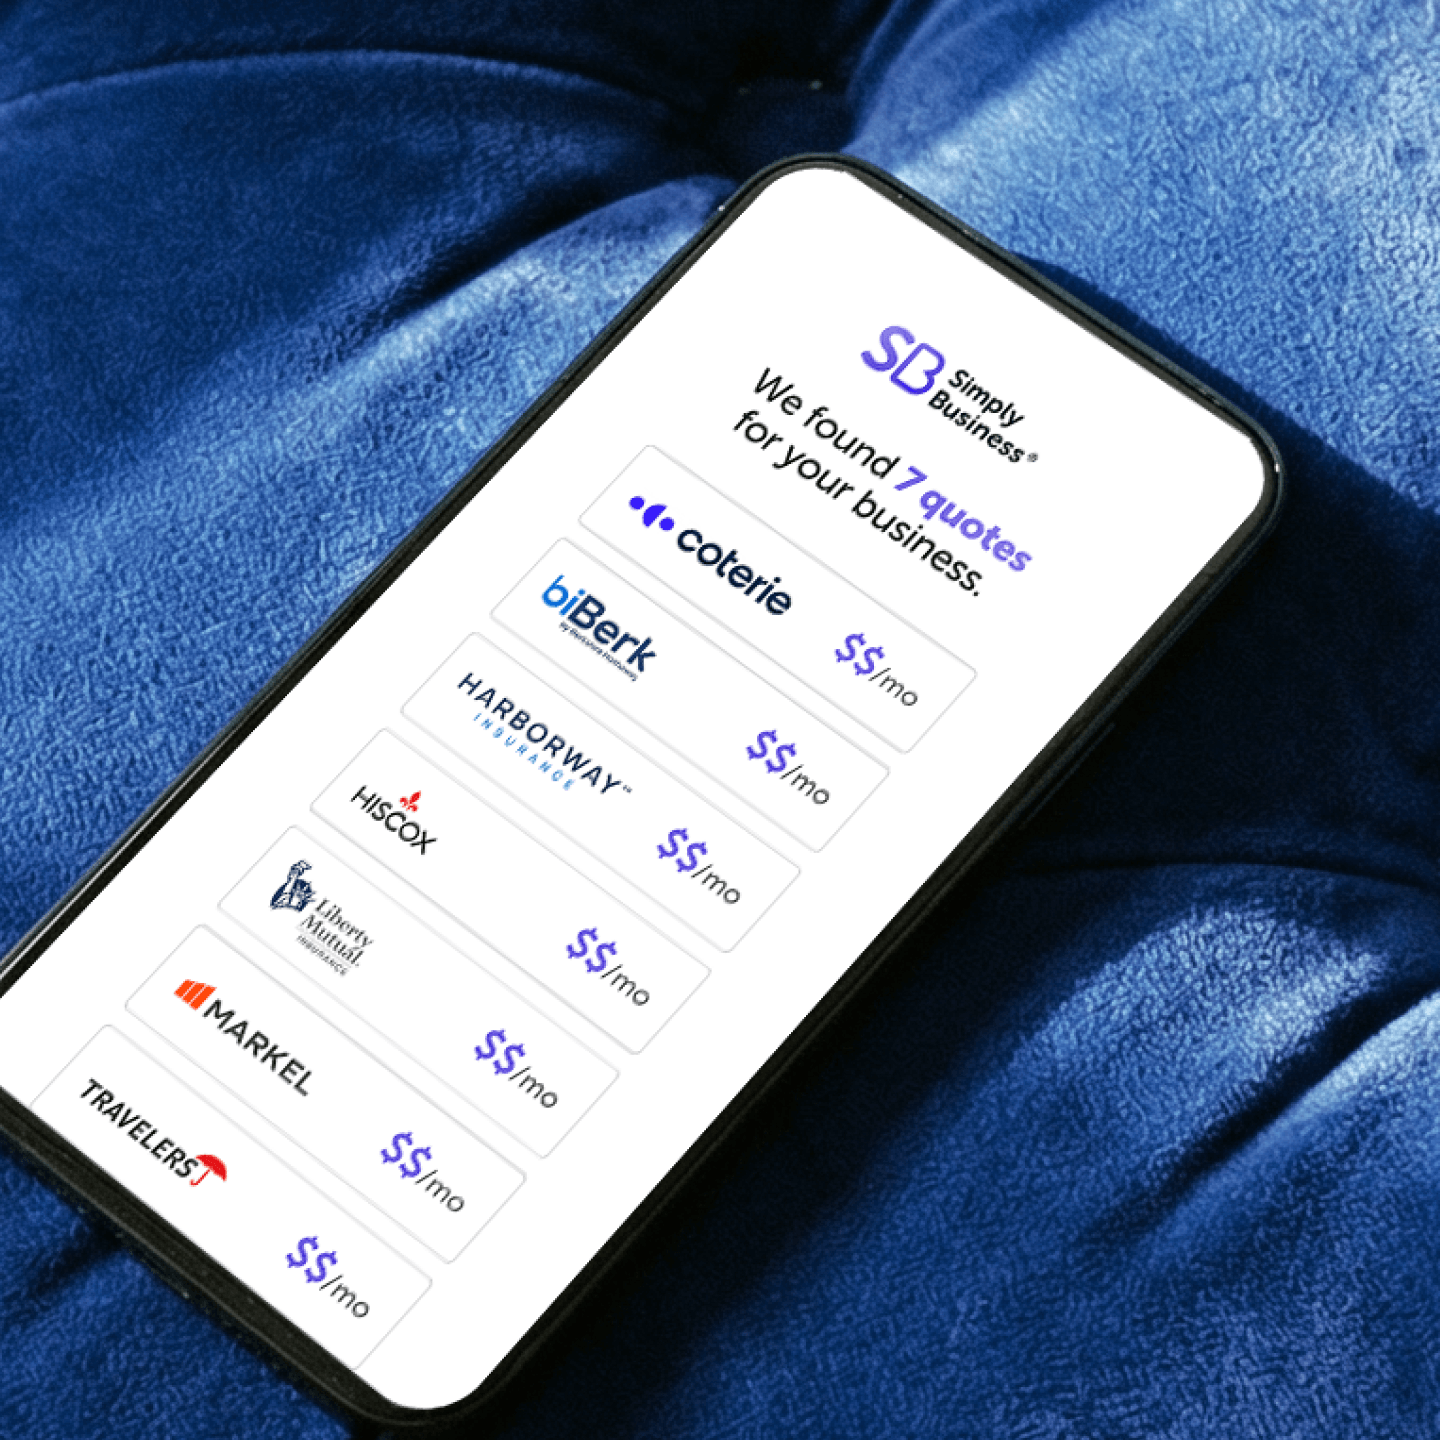
One application, multiple quotes.
All in one place.
Essential Protection
From
$33.75
/month*
Could help cover incidents like a customer slipping on a wet floor, or damage to your equipment from a fire.
What’s included:
Business Owner’s Policy
Coverage limits: up to $1M†

Get multiple quotes in less than 10 mins
Essential Protection
From
$33.75
/month*
Could help cover incidents like a customer slipping on a wet floor, or damage to your equipment from a fire.
What’s included:
Business Owner’s Policy
Coverage limits: up to $1M†
Get multiple quotes in less than 10 mins
Would you rather pick and choose your coverage? Explore all options
Over 1 million customers worldwide.

Buy instantly online.

Written by
Why Do I Need Café Insurance?
You know that the quality of espresso can make or break a macchiato. You know the exact science of making a perfect Americano. You might even know how to top it all off with some latte art. But you may not know offhand the right kinds of business insurance for a café.
Below are some of the most common types of insurance policies that café and coffee shop owners carry to stay protected.
What Type of Café Insurance Do I Need?

Business Owner’s Policy (BOP)
General liability, property insurance, and more all in one convenient package.
From
$33.75
/month*

Workers’ Comp
Coverage to help take care of employees who get sick or injured on the job. Most states require this coverage for small businesses with full- or part-time employees. It also can benefit business owners who don’t have employees.
From
$38.91
/month*

General Liability
A foundational insurance coverage to help handle costs from third-party accidents, property damage, and bodily injury.
From
$20.75
/month*
Business insurance —
a quick explainer
Learn more about policies for small businesses, what they cover, why you might need them, and how we can help – all in just 60 seconds.
Business insurance is often made up of different types of policies to cover different things, similar to how your health insurance can be made up of medical dental and vision coverage. Here are some of the ones small business owners need. General liability is kind of the Swiss army knife of insurance. It can do a lot, like help handle costs from third party accidents, property damage, bodily injury, and more. Nobody’s perfect, right? That’s what professional liability is for. It could come in handy in the event of honest mistakes or claims of negligence. Workers’ comp can protect your business and help take care of employees who get sick or injured on the job. Small businesses are big targets for cyber criminals. Cyber Insurance can help cover costs associated with stolen customer data, cyber attacks, breaches, and fraud. BOP or a business owners policy combines different types of coverages like general liability and commercial property insurance. Putting them together for you is where we come in. You tell us a bit about your business online or on the phone, and we customize the coverage options for what you do and what you need. It’s your business, it should be your insurance as well. That’s why we’re here.
What Does Café Insurance Cover?
When referring to “Café Insurance,” we mean any one or combination of multiple business insurance policies that will help cover a café business. We’ll get into more detail below.
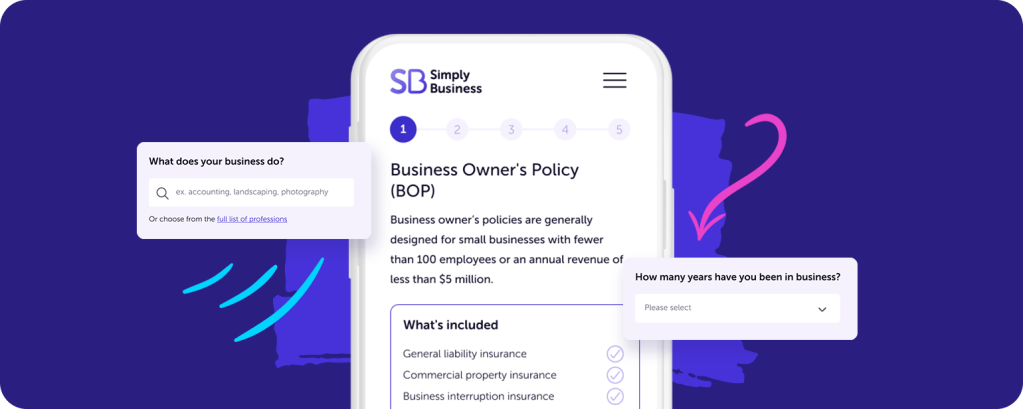
A business owner’s policy (BOP) is a great place to start. A BOP bundles several types of coverage — typically including property and liability insurance — into one convenient policy. As a café owner, you’re used to the grind in more ways than one. But your commercial insurance doesn’t have to make things more complicated for you.
- Simplicity: Manage one policy instead of several.
- Flexibility: Add or drop coverages as your needs change.
- Value: Bundling coverage often costs less than having separate policies.
We recommend BOP insurance for cafés and coffee shops because it can be customizable and typically combines different coverage types, including:
General liability insurance
A general liability (GL) policy typically covers:
- Third-party bodily injury
- Third-party property damage
- Personal and advertising injury
- Claims due to defective goods
GL isn’t generally a legal requirement, but it’s a very popular type of policy for small businesses. It generally covers a variety of common commercial claims and can be a smart choice for just about any business.
Commercial property insurance
A commercial property insurance policy generally can cover damage to assets resulting from:
- Fire
- Wind, storms, and snow
- Vehicular damage to the business’s property
- Sprinkler leakage and various other forms of water damage
- Vandalism or theft on the premises
- Building collapse
Property insurance for small businesses is particularly useful for businesses with valuable physical property. If you own your café location, this can be great coverage to have in your back pocket. If you rent, your landlord may even require you to carry it.
While commercial property insurance typically covers losses following certain natural disasters, it does not apply to damage from floods or earthquakes. Vehicle damage and cyber claims are typically not included, either.
Business interruption insurance
If your café is forced to close due to theft, arson, or certain natural disasters, business interruption insurance may be able to help you cover some expenses, up to your policy limits. These expenses typically include:
- Temporary relocation
- Payroll
- Operational expenses
- Loan payments and taxes
- Closure due to damage to a nearby building or business
- Training costs on new replacement equipment
Business interruption due to floods, earthquakes, and public health events isn’t eligible. However, it could be a lifeline for you, your employees, and your café in the event of a forced closure due to a covered event.
Optional add-ons and customizations
Depending on your café’s specific needs, you may want to expand your coverage to include some other common risks to small businesses. BOP insurance can be amended to include:
- Spoiled merchandise
- Equipment breakdown
- Forgery
- Employee theft
Cafés rely on costly specialized equipment and high-quality ingredients to deliver the best food and beverages possible. If your whole milk spoils or your espresso machine blows a gasket, it could slow or even shut down your business until replacements and/or repairs are dealt with. While these coverage add-ons aren’t required, they may help prevent you from paying out of pocket for common cafe problems.
Café Insurance Cost
The cost of insurance is difficult to predict without getting the full picture. It’s like making a complicated coffee drink without measuring your ingredients to keep your ratios in check. As with most types of insurance, the cost of café insurance coverage will depend on a variety of factors including:
- The coverage limits you select
- The location of your café
- The size and age of the café
- The value of your property
- Any previous claims associated with the café
- Any optional coverage you decide to add
One of the best ways to figure out how much a business owner’s policy for your café would cost is to get a quote. In certain cases, cafés and restaurants may be able to find coverage for as low as $575 a year, with the option to make interest-free monthly payments.

What Does Café Insurance Cost
Try our insurance calculator.
Get a quick estimate in just 3 steps.

Answers to More Café Insurance Coverage Questions
BOP insurance for cafeé and coffee shops bundles together different policies, so it often can be less expensive than buying individual policies separately.
As with most types of insurance, the cost of cafe insurance will depend on a number of factors, such as:
- Your type of business
- The services you provide
- Where your business is located
- The number of employees you have
- Your estimated revenue
- And more
If you’re still unsure, getting a restaurant insurance quote or speaking with an agent could help you get a better idea of how much a business owner’s policy will cost you.
If you’re thinking of buying insurance for your cafe or coffee shop, we want to make it easier for you.
We think it’s helpful to have an idea about your annual revenue and payroll estimates as well as information about any previous insurance before you get started.
Small business insurance is what we do. Whether it’s covering you for accidents and mistakes, meeting workers’ comp requirements, or protecting your equipment and tools, we can help find the coverage you need for your restaurant.
We provide customized coverage options and quotes from top-rated small business insurers – all in just 10 minutes. More than 1 million small business owners worldwide trust us with their insurance, and we consistently earn high customer ratings and reviews.

Why Small Businesses Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

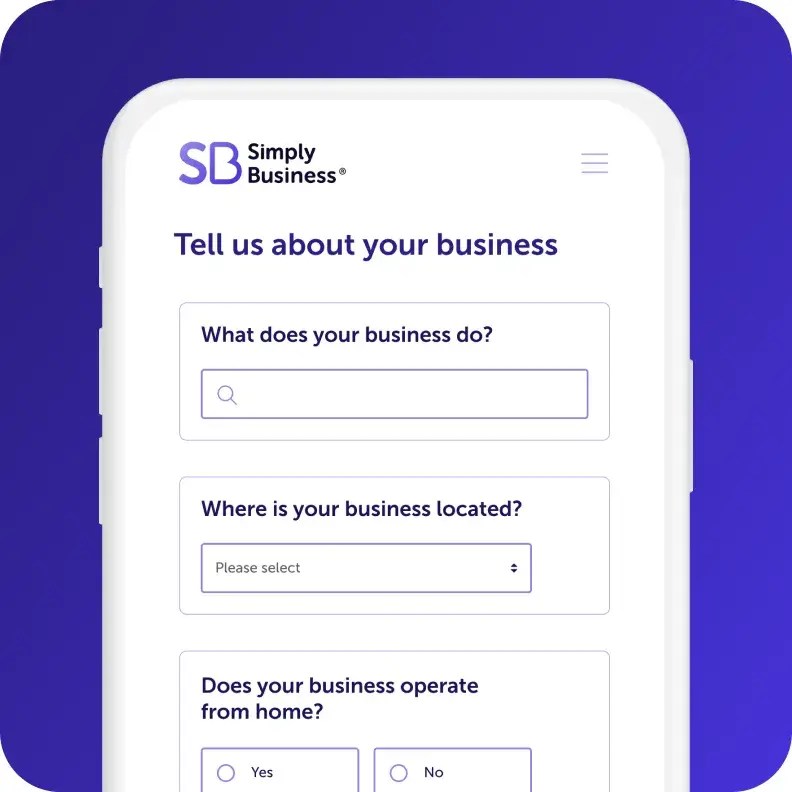
Start your quote
Answer a few questions about
your business in one form.

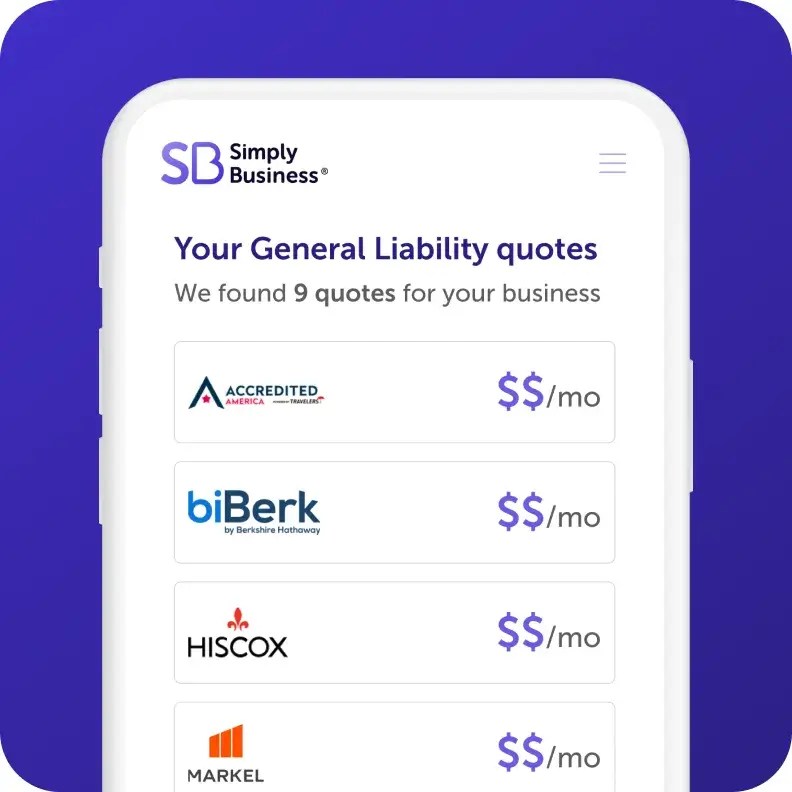
Review quotes
Compare quotes side by side from top-rated insurers and customize your coverage.

Get protected in minutes
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.

Written by
Our +1 million customers are big fans. And you will be too.

I went online, looked around, and found Simply Business. The process was so seamless. I got my certificate within minutes. It was just phenomenal.
Karen
Owner of Tangaza Bath & Body Studio LLC
With Simply Business I know I can look at different carriers, but also see all my stuff in the same place… a lot of [insurance] providers don’t offer a variety of coverage, all in one place.
Jef
Owner of Bunker83 LLC
It wasn’t overwhelming to figure out what was covered and what wasn’t covered. And the cost was competitive.

Kim
Owner of Room to Breathe Professional Organizing
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information
8-minute read
How Much Does Coffee Shop Insurance Cost?

9-minute read
A General Liability Insurance Guide for Small Business
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.
† Limits may vary by state and nature of your business.
Page last updated: