Financial Planner Insurance
Find out what insurance coverage you need as a financial planner.
Compare policies from leading national insurers. Get a quote in minutes.
Over 1 million customers worldwide.

Buy instantly online.

Written by
Why Do I Need Financial Planner Insurance?
As a financial planner, you’ve put in the hours and dedication to take your craft to the next level of professionalism and have earned the CFP designation. You’re a master at numbers and strategizing best practices for saving toward a big goal, whether that’s a vacation, retirement, or college fund. You know when to spend, when to save, and how to make realistic goals. However, you may not know much about small business insurance policies.
Below are some of the most common types of insurance policies that financial planners carry to stay protected.
What Type of Financial Planner Insurance Do I Need?

From
$25.83
/month*

General Liability
A foundational insurance coverage to help handle costs from third-party accidents, property damage, and bodily injury.
From
$20.75
/month*

Workers’ Comp
Coverage to help take care of employees who get sick or injured on the job. Most states require this coverage for small businesses with full- or part-time employees. It also can benefit business owners who don’t have employees.
From
$38.91
/month*
Business insurance —
a quick explainer
Learn more about policies for small businesses, what they cover, why you might need them, and how we can help – all in just 60 seconds.
Business insurance is often made up of different types of policies to cover different things, similar to how your health insurance can be made up of medical dental and vision coverage. Here are some of the ones small business owners need. General liability is kind of the Swiss army knife of insurance. It can do a lot, like help handle costs from third party accidents, property damage, bodily injury, and more. Nobody’s perfect, right? That’s what professional liability is for. It could come in handy in the event of honest mistakes or claims of negligence. Workers’ comp can protect your business and help take care of employees who get sick or injured on the job. Small businesses are big targets for cyber criminals. Cyber Insurance can help cover costs associated with stolen customer data, cyber attacks, breaches, and fraud. BOP or a business owners policy combines different types of coverages like general liability and commercial property insurance. Putting them together for you is where we come in. You tell us a bit about your business online or on the phone, and we customize the coverage options for what you do and what you need. It’s your business, it should be your insurance as well. That’s why we’re here.
What Does Financial Planner Insurance Cover?
Without the right insurance, one unexpected mishap can drain your profits. Here’s which coverages for financial planner insurance that can help protect you from common risks.
Professional Liability Insurance for Financial Planners
Professional Liability insurance — which is also referred to as errors and omissions insurance (E&O insurance) — is a type of policy that provides coverage in the event a client alleges negligence resulting from your professional services. If your client decides to sue your business for errors related to your services and advice, your professional liability insurance policy may cover damages and legal costs that you might be ordered to pay due to negligence.
For example, say your client is asking you to help them plan to save up for their son’s college tuition. You do all the work and give them your advice, but the client alleges you were negligent while delivering your services with false information or misguidance. You could receive a claim for alleged negligence, but professional liability may help cover the legal costs to that claim.
General Liability Insurance for Financial Planners
General liability insurance — also known as commercial general liability (CGL) — protects your business from third-party claims of bodily injury or damage to someone else’s property.
If you have an office where clients come to visit, there’s always a risk that they may accidentally injure themselves on site. That could be as simple as their tripping on a rug and hitting their head, requiring a trip to the hospital. General liability insurance may help cover some of the medical bills for that injured individual. Also, if you are visiting a client on their property and you happen to accidentally knock over an expensive chair and break a table in the process, general liability insurance may help cover the repair costs to their property.
Learn more about General Liability Insurance.
Workers Compensation Insurance for Financial Planners
Do you have full-time employees or part-time help? If that’s the case, you may need workers compensation insurance. If someone who works for you gets hurt on the job, this coverage provides help with medical bills, lost wages, and any legal costs that relate to the injury.
Most states require any business with employees to have workers compensation insurance, so make sure you add it to your policy!
Learn more about workers compensation insurance.
How Much Does Financial Planner Insurance Cost?
Not sure how much you might pay for insurance coverage as a financial planner? While there’s no one answer for how much your policy will cost, your final premium will usually be determined by:
- The number of employees you have (including part-time and consultants)
- Your location
- Payroll
- Revenue
- And more
Want to find out how much your insurance policy might cost? Just click here to answer a few questions about your business.
Answers to More Financial Planner Insurance Coverage Questions
Financial planner insurance is a collection of separate business insurance policies designed to protect financial advisors and planning firms from the specific risks they face day to day. These include Professional Liability, General Liability, and Workers’ Compensation coverage.
- Professional Liability (also known as Errors & Omissions) typically protects against claims of negligence or errors in financial advice
- General Liability helps cover third-party bodily injury or property damage
- Workers’ Compensation helps cover medical costs and lost wages for injured employees
Together, these policies help shield your practice from lawsuits, client disputes, and workplace accidents that could otherwise drain your profits.
Insurance policies for financial planners typically covers claims of professional negligence, third-party injuries or property damage, and employee injuries on the job. The exact protection depends on which insurance policies you carry.
For example, if a client alleges you gave them misguided investment advice, Professional Liability insurance can help cover legal defense costs and damages. If a client trips and falls in your office, General Liability insurance can help cover their medical bills. And if you have employees, Workers’ Compensation can cover injury-related costs if one of them gets hurt at work.
Professional Liability insurance, also called Errors and Omissions (E&O) insurance, typically covers legal costs and damages if a client sues your financial planning business over alleged negligence or mistakes in your advice.
For example, if you help a client plan for their child’s college tuition and they later claim your guidance was flawed, Professional Liability insurance can help pay for legal defense and any settlement or judgment. This coverage is important for financial planners because giving advice is the core of the business, and even honest mistakes can lead to costly claims.
General Liability insurance, also known as Commercial General Liability (CGL), protects your financial planning business from third-party claims of bodily injury or property damage. It’s a foundational policy for any business that meets clients in person.
- Typically covers medical costs if a client is injured at your office, like tripping on a rug
- Typically covers repair costs if you accidentally damage a client’s property while visiting them
- Helps pay legal fees if a third party sues over an injury or property damage claim
Workers’ Compensation insurance typically covers medical bills, some lost wages, and legal costs if an employee gets sick or injured on the job. Depending on state law, most states require any financial planning business with full- or part-time employees to carry this coverage.
Even if you don’t have employees, workers’ comp can still benefit sole proprietors in some states by covering their own work-related injuries. Requirements vary by state, so it’s worth confirming your specific obligations before skipping this coverage.
Financial planner insurance costs start from around $20.75/month for General Liability, $25.83/month for Professional Liability, and $29.35/month for Workers’ Compensation, based on Simply Business data from the tenth percentile of policies sold between January and June 2025.
Your actual premium depends on factors like your location, number of employees, payroll, revenue, and claims history. Getting a personalized quote is the most reliable way to know what you’ll pay.
Premiums are calculated based on several factors specific to your business, including your location, revenue, payroll, and number of employees, among others. Insurers use these details to assess your level of risk.
- Location: State regulations and local risk factors can affect pricing
- Revenue and payroll: Higher earnings or staffing costs typically mean higher premiums
- Employee count: More employees increase workers’ comp exposure
- Business history: Prior claims or existing coverage can influence your rate
Because these variables differ for every business, the only way to get an accurate number is to request a quote.
You can get a quote for financial planner insurance policies from Simply Business by answering a few questions about your business online, comparing quotes from top-rated carriers, and purchasing coverage instantly—all within about ten minutes.
Simply Business will ask for details like your state, revenue, payroll, and employee count to match you with policies that fit your specific risks and budget.

Why Small Businesses Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

Start your quote
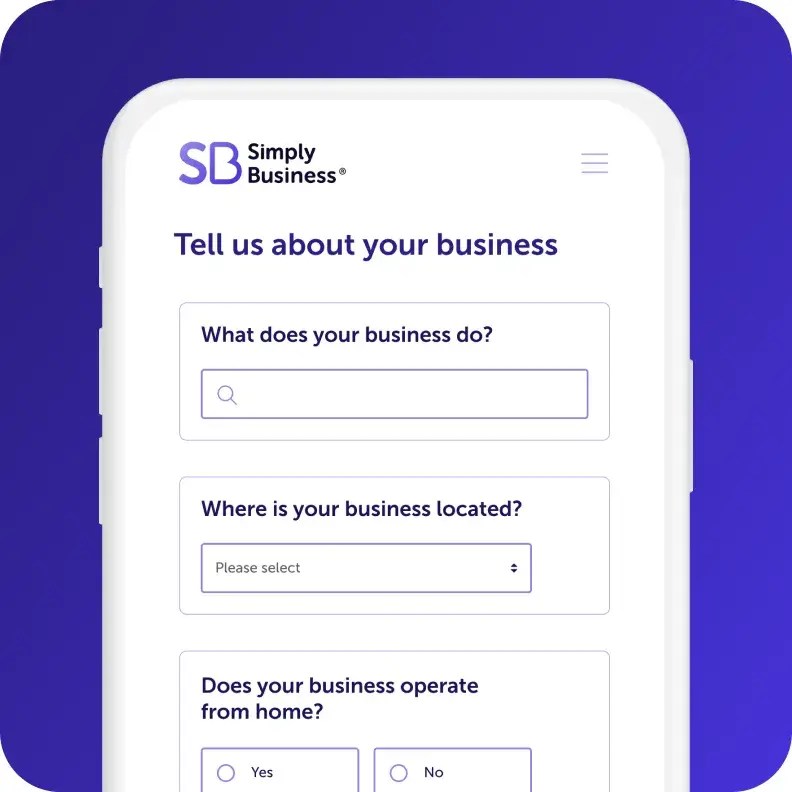
Answer a few questions about
your business in one form.

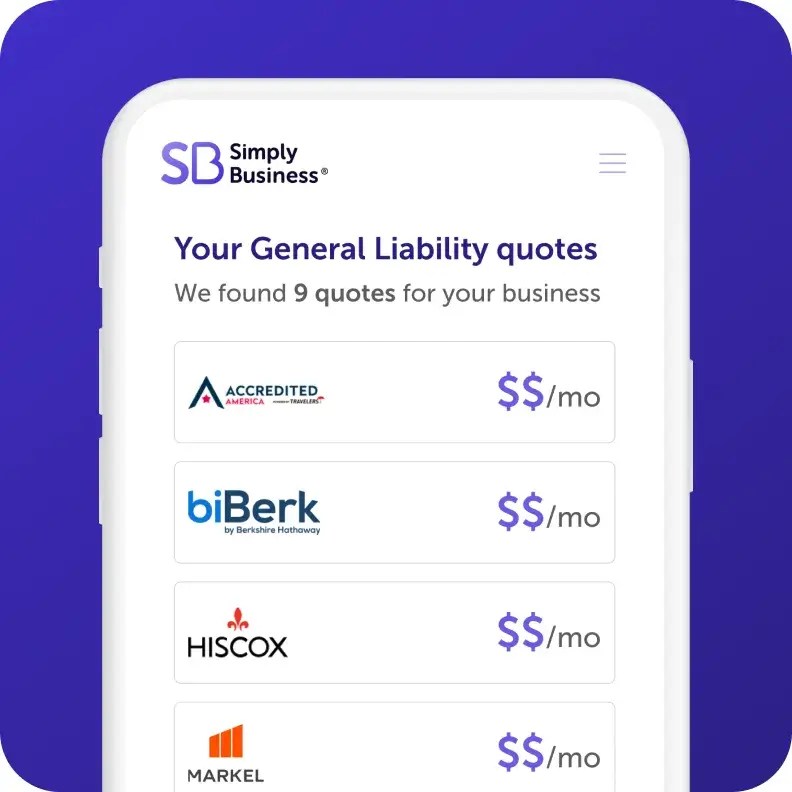
Review quotes
Compare quotes side by side from top-rated insurers and customize your coverage.

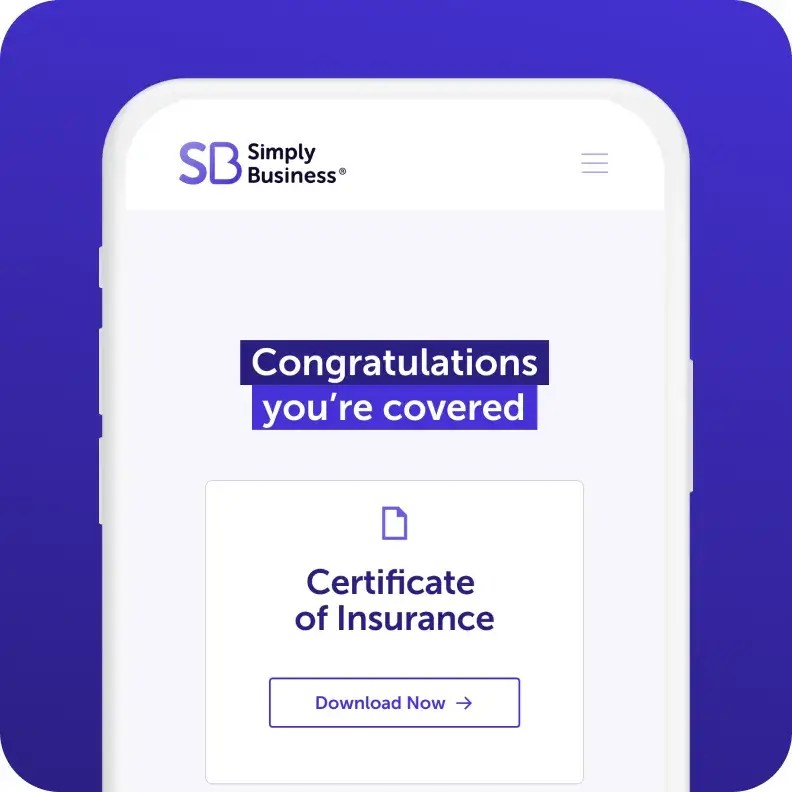
Get protected in minutes
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.

Written by
Our +1 million customers worldwide are big fans. And you will be too.

I went online, looked around, and found Simply Business. The process was so seamless. I got my certificate within minutes. It was just phenomenal.
Karen
Owner of Tangaza Bath & Body Studio LLC
With Simply Business I know I can look at different carriers, but also see all my stuff in the same place… a lot of [insurance] providers don’t offer a variety of coverage, all in one place.
Jef
Owner of Bunker83 LLC
It wasn’t overwhelming to figure out what was covered and what wasn’t covered. And the cost was competitive.

Kim
Owner of Room to Breathe Professional Organizing
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.
† Limits may vary by state and nature of your business.
Page last updated: