Web designer insurance
One application, multiple quotes.
All in one place.
Essential Protection
From
$25.83
/month*
Can provide coverage if a client claims there was a mistake in the professional services you provided.
What’s included:
Professional Liability / Errors & Omissions
Coverage limits: $100K to $3M†

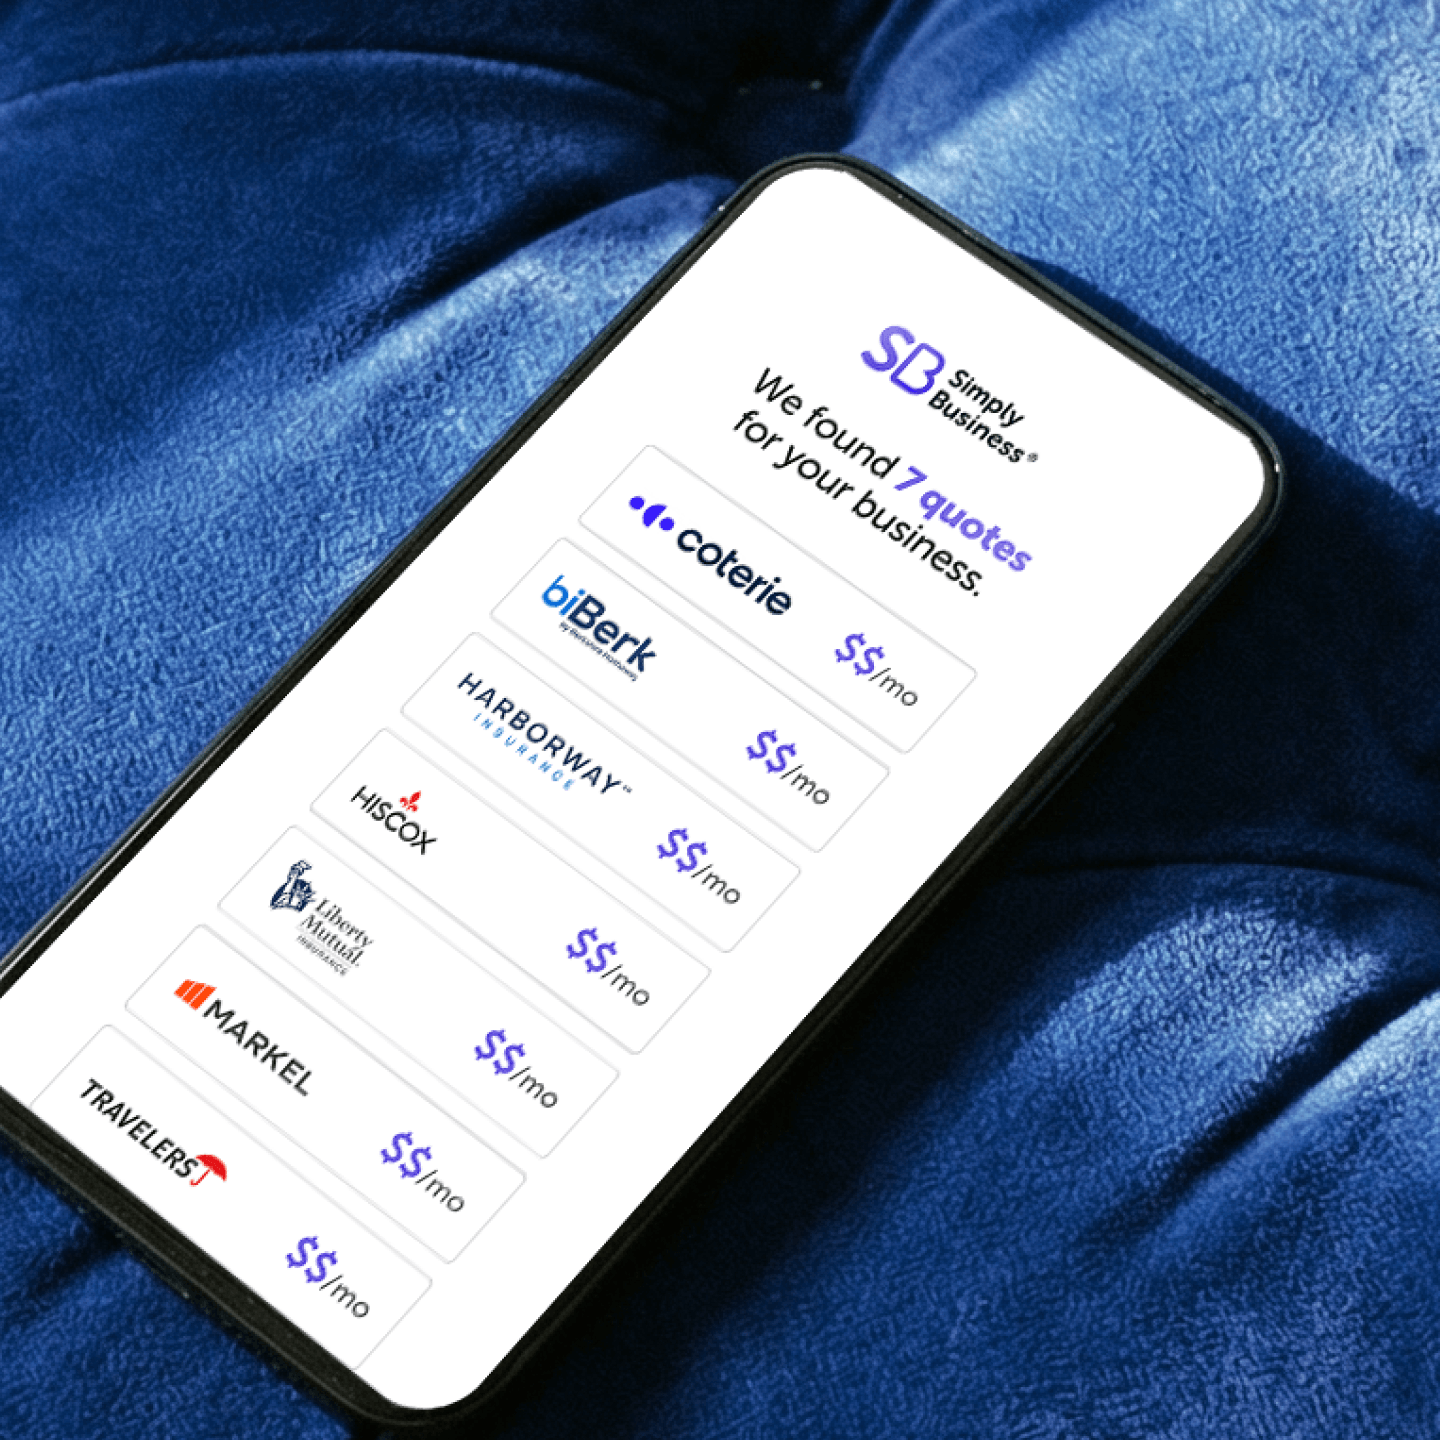
Get multiple quotes in less than 10 mins
Essential Protection
From
$25.83
/month*
Can provide coverage if a client claims there was a mistake in the professional services you provided.
What’s included:
Professional Liability / Errors & Omissions
Coverage limits: $100K to $3M†
Get multiple quotes in less than 10 mins
Would you rather pick and choose your coverage? Explore all options
Over 1 million customers worldwide.

Buy instantly online.

Written by
Why Does a Web Designer Need Insurance?
As far as your customers are concerned, you work magic every day as a web developer. From your perspective, you can see the fascinating and sometimes frustrating work you’ve done for years to get to where you are today. You’ve invested so much time in web design, that it’s time to future-proof your business.
Below are some of the most common types of insurance policies that web designers carry to stay protected.
What Type of Web Designer Insurance Do I Need?

Professional Liability / Errors & Omissions
Coverage for damages and legal costs due to mistakes or negligence claims.
From
$25.83
/month*

General Liability
A foundational insurance coverage to help handle costs from third-party accidents, property damage, and bodily injury.
From
$20.75
/month*

Equipment and Business Property
Also known as inland marine insurance, this coverage can financially protect equipment and inventory that’s in transport or stored offsite.
From
$20.83
/month‡

Business Owner’s Policy (BOP)
General liability, property insurance, and more all in one convenient package.
From
$33.75
/month*

Workers’ Comp
Coverage to help take care of employees who get sick or injured on the job. Most states require this coverage for small businesses with full- or part-time employees. It also can benefit business owners who don’t have employees.
From
$38.91
/month*
Business insurance —
a quick explainer
Learn more about policies for small businesses, what they cover, why you might need them, and how we can help – all in just 60 seconds.
Business insurance is often made up of different types of policies to cover different things, similar to how your health insurance can be made up of medical dental and vision coverage. Here are some of the ones small business owners need. General liability is kind of the Swiss army knife of insurance. It can do a lot, like help handle costs from third party accidents, property damage, bodily injury, and more. Nobody’s perfect, right? That’s what professional liability is for. It could come in handy in the event of honest mistakes or claims of negligence. Workers’ comp can protect your business and help take care of employees who get sick or injured on the job. Small businesses are big targets for cyber criminals. Cyber Insurance can help cover costs associated with stolen customer data, cyber attacks, breaches, and fraud. BOP or a business owners policy combines different types of coverages like general liability and commercial property insurance. Putting them together for you is where we come in. You tell us a bit about your business online or on the phone, and we customize the coverage options for what you do and what you need. It’s your business, it should be your insurance as well. That’s why we’re here.
What Kind of Web Designer Insurance Do I Need?
You know APIs and HTTP, and we know policies and premiums. Together, we can create beautiful websites and protect businesses across the country. Want to take a peek into our world? Here’s what you need to know about the three types of policies available to web designers and what they can cover.
General Liability Insurance
If you’re looking for a solid insurance foundation that could cover a variety of scenarios, look no further than general liability insurance. This type of policy typically covers bodily injury, property damage to third-parties, and third-party accidents. For reference, “third-party” is insurance lingo for your clients or vendors.
Just because this is a generalized insurance doesn’t mean it can’t pack a serious punch. The average customer injury or damage claim — something that GL covers — is a whopping $30,000. If you happen to have that money sitting around, you’d have to pay for the accident out of pocket. If not, it would likely either have to come from your family’s finances or a loan.
What kind of accidents could come your way as a web developer, though? After all, some days, you have to remind yourself to peel your eyes off the screen every so often. Imagine a client visits your office to cover project details when they trip over a cord and drop their laptop which breaks.
On top of the damages for the broken equipment, your client could also sue you for the trouble they had to go through to work around their business setback. If you had general liability insurance, your policy could potentially offset those costs and preserve your finances.
So what does general liability insurance typically cover in your web design business? Here’s a recap:
- Third-party property damage
- Bodily injury (clients or vendors)
- Medical expenses
- Personal and advertising injury
- And more
General liability insurance usually does not cover:
- Personal property damage
- Professional services
- Employee injury and workers compensation
- Damage to your work
- Motor vehicles during business use
- Intentional injury or damage
- And more
Professional Liability Insurance
Perhaps you’ve heard of professional liability insurance for doctors, lawyers, and surgeons, but did you know that web designers can benefit from this coverage too? This type of policy protects your business against a negligence claim. A client could sue you for negligence and damages, even if you don’t agree with the claim. Professional liability insurance covers you if a client claims that you, your employees, or your business were negligent.
In your work, negligence could look like creating something that causes your customer to lose business. For example, you’re so eager to finally wrap up a long project that you don’t realize one of the images you designed could come off as explicit. The site goes live, and your client’s audience is upset. The incident harms the business’s reputation, and they lose money during their launch.
If you were the designer in this scenario, you could face damages and legal fees. Even if the court decided there was no negligence on your part, your lawyer would still expect a check. So businesses that have professional liability insurance could have their costs offset by their policy. Nobody plans on being sued, but coverage minimizes the impact of the “worst-case scenario.”
Let’s review the scenarios that professional liability insurance usually covers:
- Legal defense costs
- Omissions or alleged omissions
- Negligence or alleged negligence
- Claims and damages
- And more
Having professional liability insurance does not usually protect you from:
- Property damage
- Intentional acts and omissions
- Bodily injury
- Medical expenses
- And more
Workers Compensation Insurance
If you grow your web design business into an agency, you can take on more projects, clients, and employees. As your payroll upgrades from a party-of-one to a 2+ person shop, you’ll likely have more insurance needs.
Most states require you to carry workers compensation insurance if you have part-time or full-time employees. This type of insurance usually covers medical bills, lost wages, and legal costs associated with an employee who gets sick or hurt on the job.
Not only is protecting your employees the right thing to do, having workers comp insurance can be a smart financial decision. The average cost of a workers comp claim is $40,051, which means that the price of a single accident makes workers compensation insurance worth having.
Workers compensation insurance for web development firms may cover:
- Medical payments
- Lost wages
- Rehabilitation expenses
- Death benefits
Why Should You Get a Web Designer Insurance Policy?
I know what you’re thinking — I do most of my work sitting at the computer; why would I need insurance for that? While it’s true that working online may not have the same workplace dangers as a construction site, it doesn’t mean you’re immune to accidents.
Forty-three percent of small business owners polled reported being threatened with or involved in a civil lawsuit. While this isn’t the majority, the costs you could face in a lawsuit are usually enough to make you do a double-take.
The average costs small business owners are exposed to without insurance include:
- $30,000 for property damage or accident claims
- $50,000 for reputational harm claims (e.g., slander or libel)
- $20,000 for a client slip-and-fall case
Without insurance, you’d need to pay for damages to your client’s property out of pocket. If you face a lawsuit without insurance coverage, you can probably kiss your business savings goodbye. The toughest part, though, is that you don’t necessarily have to do something wrong to face these business challenges.
Since you’re advising clients and creating something for their business, a single disgruntled client could sue you for negligence. Whether you actually were negligent or not, you can expect to rack up legal fees.
We don’t bring up these scenarios to scare you. But to make a mistake is only human, so you shouldn’t dread what could be. Instead, you can take a step today to have peace of mind.
Having web developer insurance has its perks beyond protecting you on your “bad days.” Having a certificate of insurance (COI) could help you rent office space and build confidence with potential clients and employees.

What Does Web Designer Insurance Cost
Try our insurance calculator.
Get a quick estimate in just 3 steps.

Answers to More Web Designer Insurance Coverage Questions
Sometimes. Business insurance laws are set at the state level, so your location determines your requirements. In most cases, though, you’ll need workers compensation coverage if you have employees. Not sure what your state laws are? Our free quote process considers your location when creating customized quote options.
Typically, business owners can deduct insurance premiums when filing their income taxes. We recommend talking to an accountant about your state’s tax laws and your specific business, though
Each insurance quote is customized, and your ideal level of coverage depends on:
- The size of your business
- Your business’s location
- Your annual revenue
- And more
You can talk to our licensed agents if you have additional questions.
Getting your free insurance quotes is easy, and the process goes even faster if you have the following information on hand:
- Annual revenue estimates
- Payroll estimates
- Information on any previous claims
Business insurance requirements vary by state. You don’t necessarily need to research your state’s laws, though, since our free quote process considers your location. Our licensed insurance agents also can answer questions you may have.
A comprehensive insurance product that includes general liability, professional liability, and workers compensation can cover:
- Bodily injury
- Accidents and damages
- Employee injuries
- Unintentional mistakes
- And more
Each quote is customized to each business owner. Premium prices depend on your services and whether or not you have employees. Pricing is also affected by:
- Payroll estimates
- The location of your business
- The specific services you offer
- And more
Want to see how much your business insurance may cost? Just answer a few questions here to get free quotes and compare policy prices.
If you’re a multi-talented business owner, our licensed agents can work with you to find protection for all of your services.

Why Small Businesses Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

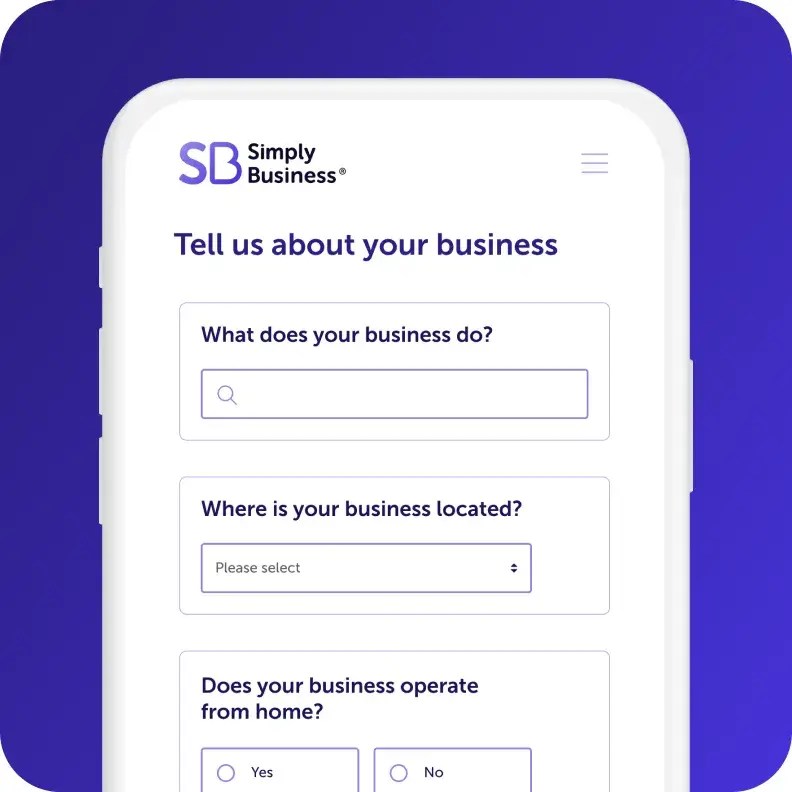
Start your quote
Answer a few questions about
your business in one form.

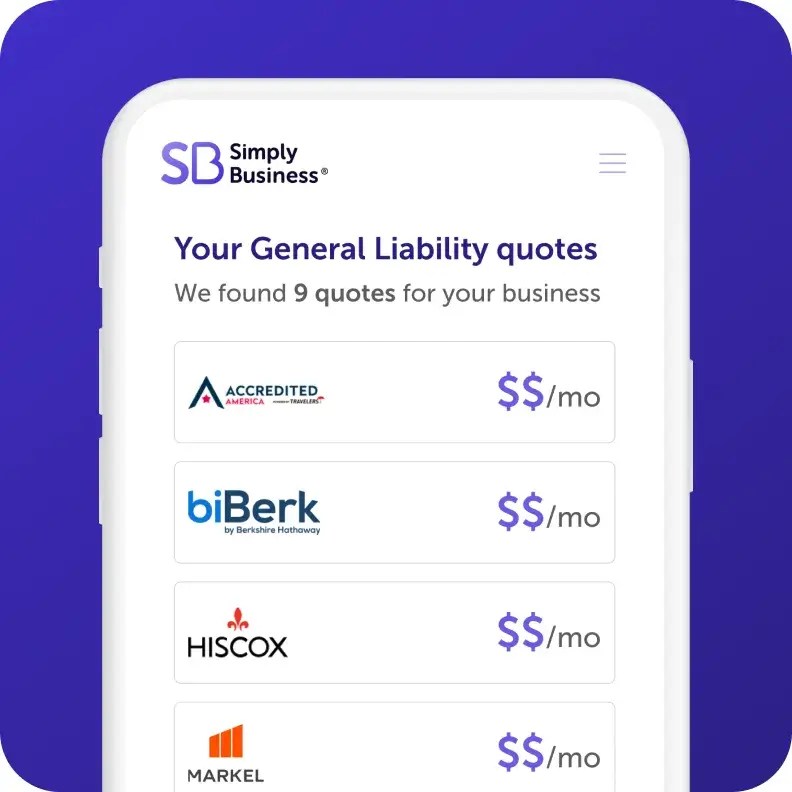
Review quotes
Compare quotes side by side from top-rated insurers and customize your coverage.

Get protected in minutes
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.

Written by
Our +1 million customers are big fans. And you will be too.

I went online, looked around, and found Simply Business. The process was so seamless. I got my certificate within minutes. It was just phenomenal.
Karen
Owner of Tangaza Bath & Body Studio LLC
With Simply Business I know I can look at different carriers, but also see all my stuff in the same place… a lot of [insurance] providers don’t offer a variety of coverage, all in one place.
Jef
Owner of Bunker83 LLC
It wasn’t overwhelming to figure out what was covered and what wasn’t covered. And the cost was competitive.

Kim
Owner of Room to Breathe Professional Organizing
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.
† Limits may vary by state and nature of your business.
‡ Displayed price is based on the lowest available coverage limit for Equipment and Small Tools policies.
Page last updated: