Glazier insurance
One application, multiple quotes.
All in one place.
Essential Protection
From
$38
/month*
Could help cover claims against your business for property damage and injuries to others.
What’s included:
General Liability
Coverage limits: $1M to $2M†

Get multiple quotes in less than 10 mins
Essential Protection
From
$38
/month*
Could help cover claims against your business for property damage and injuries to others.
What’s included:
General Liability
Coverage limits: $1M to $2M†
Get multiple quotes in less than 10 mins
Would you rather pick and choose your coverage? Explore all options
Over 1 million customers worldwide.

Buy instantly online.

Written by
Why Do I Need Glazier Insurance?
Getting insurance for your glazier business is a lot like tempered glass. It’s a process you undertake to make the result stronger, whether it’s a pane of glass or your business. If an accident happens in either scenario, the cleanup process is less impactful.
Below are some of the most common types of insurance policies that glaziers carry to stay protected.
What Type of Glazier Insurance Do I Need?

General Liability
A foundational insurance coverage to help handle costs from third-party accidents, property damage, and bodily injury.
From
$38
/month*

Contractor’s Equipment and Small Tools Insurance
Also known as inland marine insurance, this coverage can financially protect equipment and inventory that’s in transport or stored offsite.
From
$20.83
/month‡

Workers’ Comp
Coverage to help take care of employees who get sick or injured on the job. Most states require this coverage for small businesses with full- or part-time employees. It also can benefit business owners who don’t have employees.
From
$38.91
/month*
Business insurance —
a quick explainer
Learn more about policies for small businesses, what they cover, why you might need them, and how we can help – all in just 60 seconds.
Business insurance is often made up of different types of policies to cover different things, similar to how your health insurance can be made up of medical dental and vision coverage. Here are some of the ones small business owners need. General liability is kind of the Swiss army knife of insurance. It can do a lot, like help handle costs from third party accidents, property damage, bodily injury, and more. Nobody’s perfect, right? That’s what professional liability is for. It could come in handy in the event of honest mistakes or claims of negligence. Workers’ comp can protect your business and help take care of employees who get sick or injured on the job. Small businesses are big targets for cyber criminals. Cyber Insurance can help cover costs associated with stolen customer data, cyber attacks, breaches, and fraud. BOP or a business owners policy combines different types of coverages like general liability and commercial property insurance. Putting them together for you is where we come in. You tell us a bit about your business online or on the phone, and we customize the coverage options for what you do and what you need. It’s your business, it should be your insurance as well. That’s why we’re here.
What Types of Insurance Do I Need for My Glazier Business?
Every industry has its own lingo. While you and your crew know all about adhesion, beveling, and cutting, here at Simply Business, we live and breathe deductibles and liabilities. It’s easy for our two worlds to collide, though. We aim to provide the facts you need without all of the legal fluff.
Ready to learn? Let’s review the two types of business insurance to consider.
General Liability Insurance
If you’re looking for glazier insurance that can help with a wide range of scenarios, then general liability insurance is for you. This type of policy typically covers bodily injury, property damage, and third-party accidents. In this case, “third-party” means your customers and vendors.
You also may want to consider adding contents coverage to your plan, which could help with the cost if your equipment such as your favorite cordless drill, is stolen or damaged.
You already know how physically demanding and dangerous your work can be, which makes business insurance worth having. While you may be OK taking on some risk for yourself, there could be consequences if your business harms one of your customers.
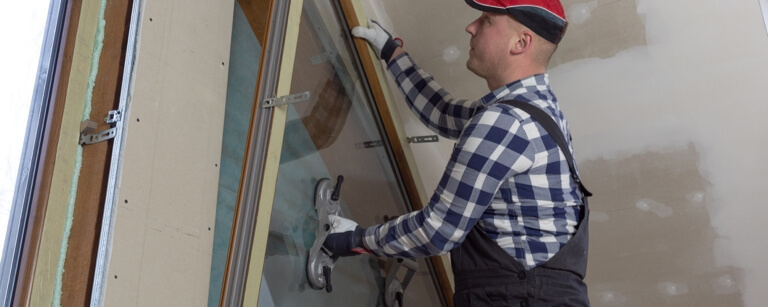
For example, imagine you’re helping a family install a new bay window in their kitchen. You forgot a tool in the truck, so you step outside to retrieve it. While you’re away, the customer’s kids pick up your tools and injure themselves. Theoretically, the family could potentially sue you for medical bills and damages.
Without insurance, this accident could be a financial setback for your business. The average customer injury or damage claim — something that GL covers — is a whopping $30,000. If you happen to have that money sitting around, you’d have to pay for the accident out of pocket. If not, it would likely either need to come from your family’s finances or a loan.
Having glazier insurance in this scenario would have a very different outcome. Your general liability coverage could cover the customer’s medical bills, as well as legal costs if they sue you, up to your policy limit.
It’s no fun to think about the bad things that may or may not happen, which is why having insurance can be a weight off your shoulders.
To recap, here’s what general liability insurance usually can cover:
- Bodily injury to another person
- Third-party property damage
- Personal and advertising injury
- Medical expenses
- And more
Now check out what general liability insurance usually doesn’t cover:
- Damage to your own property
- Professional services
- Workers compensation or injury to your employees
- Damage to your work
- Motor vehicles while in business use
- Expected or intentional injury or damage
- And more
Workers Compensation Insurance
While general liability insurance requirements vary by state, it’s likely you’ll need to carry workers compensation insurance if you have employees. This type of insurance covers medical bills, lost wages, and any legal costs associated with an employee who gets sick or injured on the job.
You’ll likely need this type of insurance even if you only have one or two part-time employees. Having workers comp is a good idea whether it’s required by law or not. The average work injury cost is about $41,000, with fractures or dislocations averaging $60,000.
Having a workers comp policy that matches your business needs protects both you and your valued employees.
In general, workers compensation insurance for glaziers can cover:
- Medical payments
- Lost wages
- Rehabilitation expenses
- Death benefits
Why Should I Get Glazier Insurance?
We’ve covered a handful of scenarios that could occur in any business, particularly one with unique dangers like a glazier company. Accidents can happen to anyone, though. Did you know that up to 43% of small business owners polled reported being threatened with or involved in a civil lawsuit?
We aren’t sharing these stats and scenarios to scare you. Instead, it’s better to be informed and proactive than take a gamble with your business. Just take a look at the most common incidents that can befall small business owners, including how much they cost on average:
- Reputational Harm — $50,000
- Customer Injury or Damage — $30,000
- Customer Slip and Fall — $20,000
You’ve come too far in your life and career to lose your business over a split-second accident. By investing in business insurance each month, you can rest easy knowing that you’ll have someone in your corner if things go wrong. You also may be relieved to know that you don’t need to pay for a one-size-fits-all policy that is far beyond your needs or budget.
Each policy is tailored to your current situation and location based on reponses you provide — not some template applied to every glazier business. By answering a few questions, our quote process can help you narrow down what you need.
There are additional positives that come with having glazier insurance. Having a certificate of insurance (COI) can help you establish trust with landlords, vendors, and customers.
Here at Simply Business, we make it easy to get the coverage you need when you need it.

What Does Glazier Insurance Cost
Try our insurance calculator.
Get a quick estimate in just 3 steps.
Answers to More Glazier Insurance Coverage Questions
Different states and landlords set their laws and requirements regarding business insurance. While it’s common for states to require workers comp coverage if you have employees, general liability insurance may be optional. It depends on the specific state you’re located in.
In general, glazier insurance premiums are tax-deductible on your business income tax. We always recommend talking to a local accountant about your business finances, though.
The amount of coverage your business may need will depend on:
- The size of your business
- Your business’s location
- Your annual revenue and payroll
- And more
Don’t worry — you won’t need to figure out your ideal coverage amount all on your own. We designed our quote form to recommend policy options based on your answers.
If you have more questions, our licensed insurance agents are available and will be happy to assist you!
Finding and comparing quotes is simple (and free). If you’re ready to explore your options, you can speed up the process by having the following information handy:
- Annual revenue estimates
- Payroll estimates
- Information on any previous claims
Yes, business insurance requirements vary by state. There’s no need to research state laws before you get started, since our quote form narrows down policy options by your location.
Your glazier insurance coverage depends on which types of policies you choose. If you have a comprehensive plan that includes general liability and workers comp, your insurance can cover:
- Bodily injury
- Accidents and damages
- Employee injuries
- Negligence or alleged negligence
- And more
It’s tough to provide an exact cost here, since each insurance policy is customized. Typically, you can expect your insurance premiums to be determined by:
- Payroll and revenue estimates
- The location of your business
- The specific services you offer
- And more
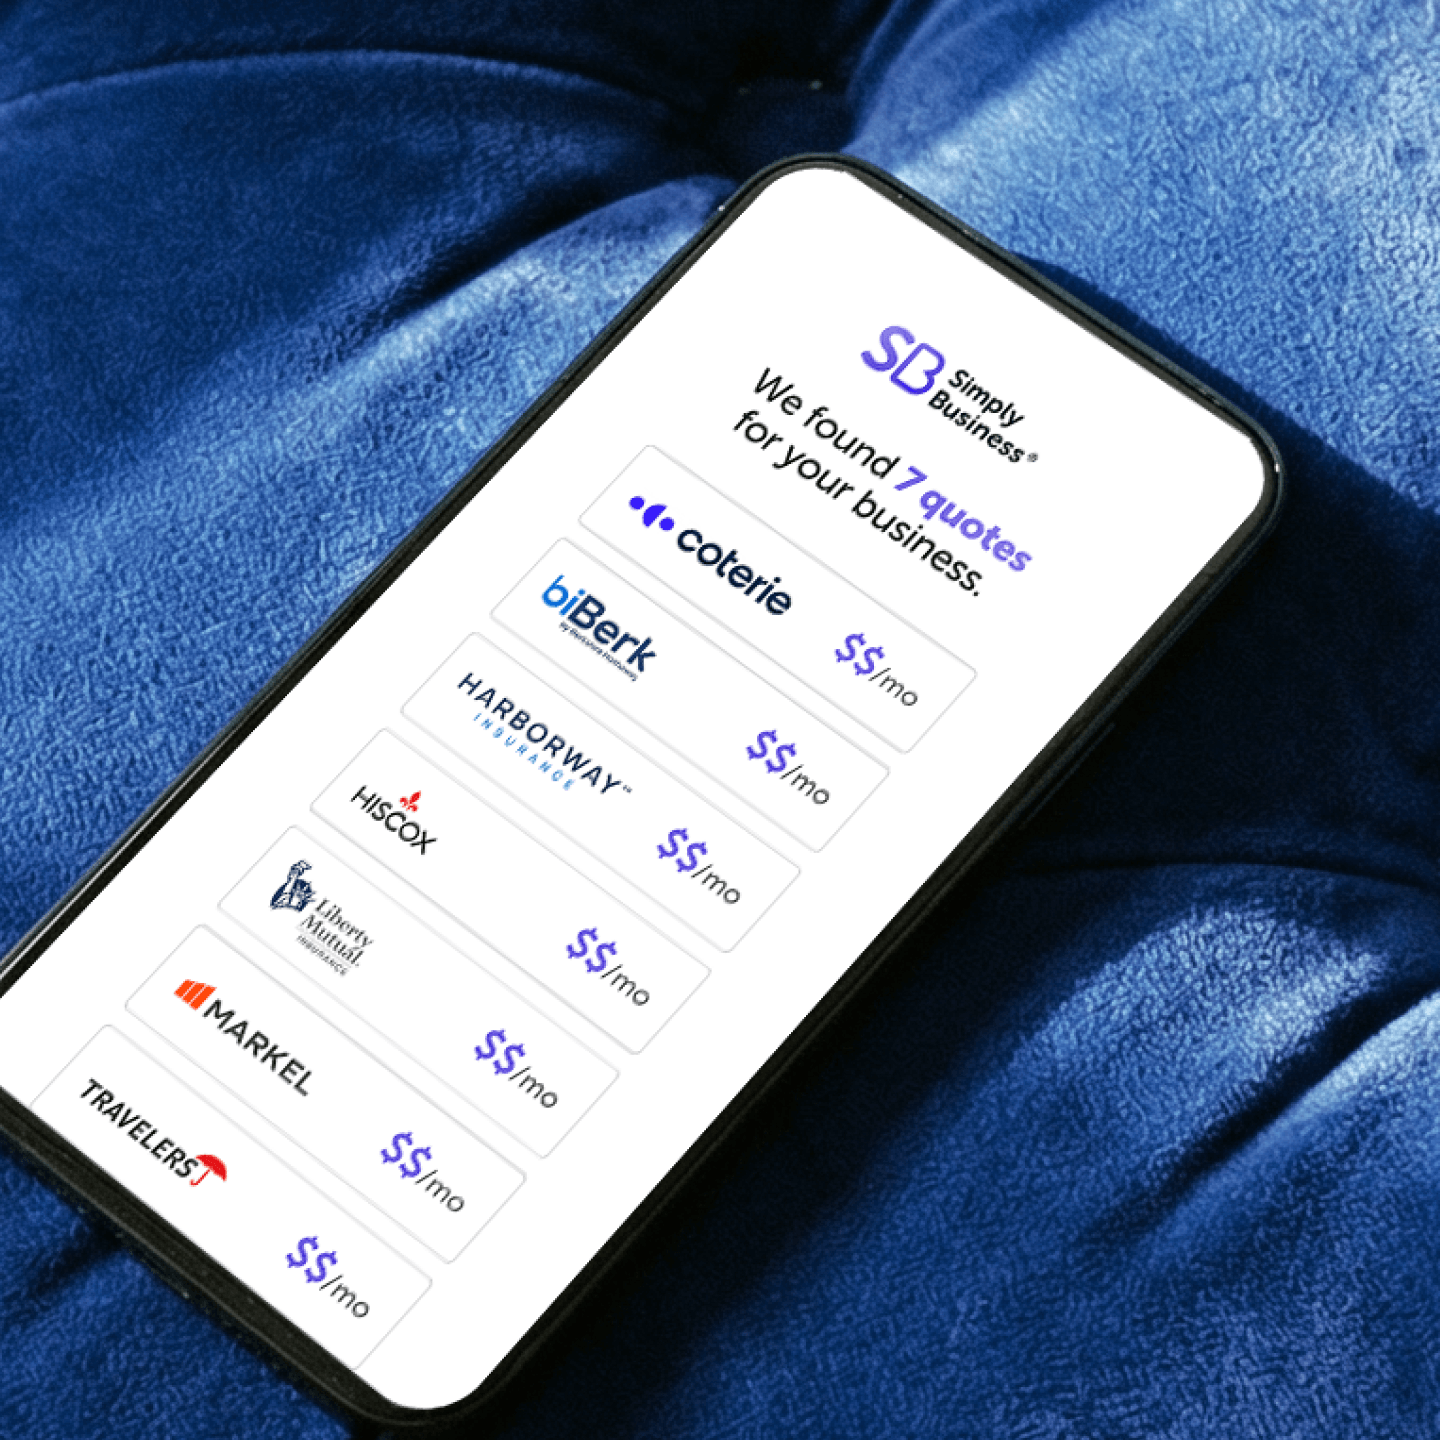
Want to see how much your glazier insurance may cost? Just click here and get free quotes from some of the top insurers in the country.

Why Small Businesses Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

Start your quote
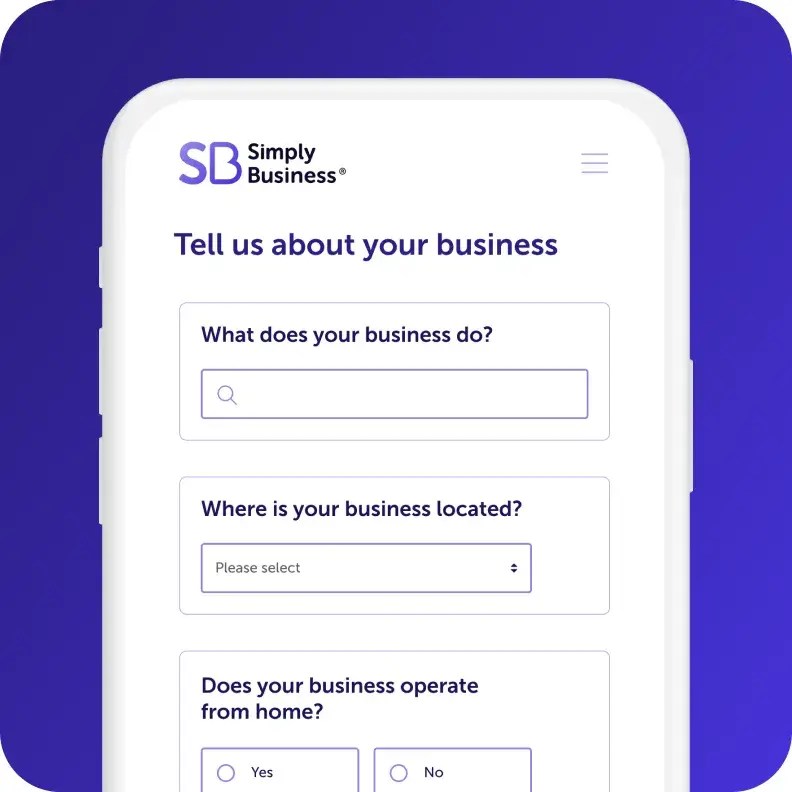
Answer a few questions about
your business in one form.

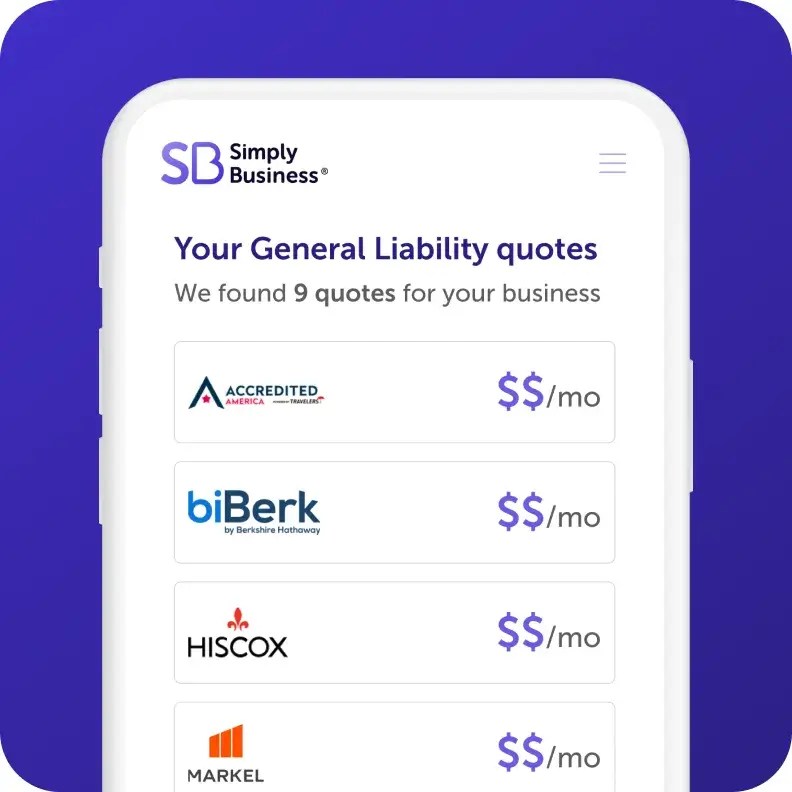
Review quotes
Compare quotes side by side from top-rated insurers and customize your coverage.

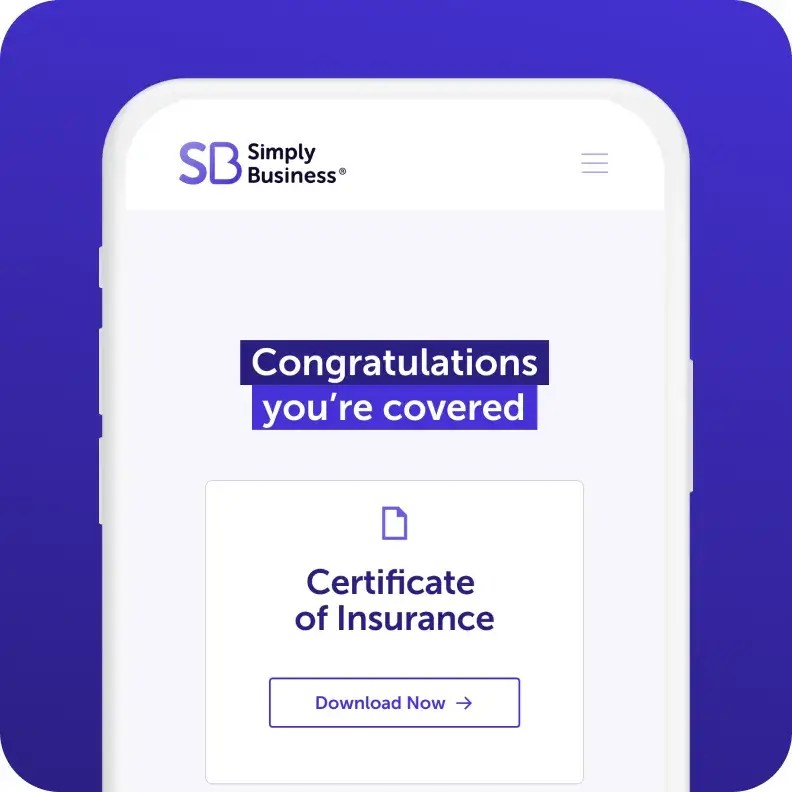
Get protected in minutes
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.

Written by
Our +1 million customers are big fans. And you will be too.

I went online, looked around, and found Simply Business. The process was so seamless. I got my certificate within minutes. It was just phenomenal.
Karen
Owner of Tangaza Bath & Body Studio LLC
With Simply Business I know I can look at different carriers, but also see all my stuff in the same place… a lot of [insurance] providers don’t offer a variety of coverage, all in one place.
Jef
Owner of Bunker83 LLC
It wasn’t overwhelming to figure out what was covered and what wasn’t covered. And the cost was competitive.

Kim
Owner of Room to Breathe Professional Organizing
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information
9-minute read
A General Liability Insurance Guide for Small Business
10-minute read
How to Mark Your Tools to Prevent Theft: A Simple Guide
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.
† Limits may vary by state and nature of your business.
‡ Displayed price is based on the lowest available coverage limit for Equipment and Small Tools policies.
Page last updated: