Land Surveyor Insurance
Find out what insurance coverage you need as a land surveyor.
Compare policies from leading national insurers. Get a quote in minutes.
Over 1 million customers worldwide.

Buy instantly online.

Written by
Why Do Land Surveyors Need Insurance?
Land surveying is precision work, and small errors can have expensive consequences. Property lines, topographic surveys, construction layouts — clients rely on your measurements to make high-stakes decisions. And accuracy is only part of the potential risk.
A boundary mistake can spark a property dispute. Fieldwork can lead to a jobsite injury. A high-value GPS rover or total station can disappear from a locked vehicle. Land surveyor insurance can help keep a professional error, accident, or equipment loss from throwing your business off course.
Below are some of the most common insurance policies land surveyors consider carrying to stay protected.
What Type of Land Surveyor Insurance Do I Need?
Below is a list of common types of insurance land surveyors may need and how much they might cost.

General Liability
Foundational insurance for land surveyors to help handle costs from third-party accidents, property damage, and bodily injury.
From
$20.75
/month*

Workers’ Comp
Coverage for employees who suffer a work-related injury or illness. Workers’ compensation insurance is typically required by law in most states, depending on your business structure and employee headcount. It also can benefit business owners who don’t have employees.
From
$38.91
/month*

Professional Liability
Professional liability, also known as errors & omissions (E&O) insurance, typically covers the costs of claims arising from professional errors, negligence, or unintentional omissions in your work.
From
$25.83
/month*

Contractor’s Equipment and Small Tools Insurance
Also known as inland marine insurance, this coverage typically helps protect your gear and equipment in transit or at a jobsite.
From
$20.83
/month‡

Business Owner’s Policy (BOP)
General liability, property insurance, and more, all in one convenient package.
From
$33.75
/month*
Business insurance —
a quick explainer
Learn more about policies for small businesses, what they cover, why you might need them, and how we can help – all in just 60 seconds.
Business insurance is often made up of different types of policies to cover different things, similar to how your health insurance can be made up of medical dental and vision coverage. Here are some of the ones small business owners need. General liability is kind of the Swiss army knife of insurance. It can do a lot, like help handle costs from third party accidents, property damage, bodily injury, and more. Nobody’s perfect, right? That’s what professional liability is for. It could come in handy in the event of honest mistakes or claims of negligence. Workers’ comp can protect your business and help take care of employees who get sick or injured on the job. Small businesses are big targets for cyber criminals. Cyber Insurance can help cover costs associated with stolen customer data, cyber attacks, breaches, and fraud. BOP or a business owners policy combines different types of coverages like general liability and commercial property insurance. Putting them together for you is where we come in. You tell us a bit about your business online or on the phone, and we customize the coverage options for what you do and what you need. It’s your business, it should be your insurance as well. That’s why we’re here.
What Does Land Surveyor Insurance Typically Cover?
From residential boundary surveys to large commercial mapping projects, here’s how a combination of coverages can help when something goes wrong.
You’re surveying a commercial property when a pedestrian trips over your tripod and injures their shoulder. Suddenly, routine fieldwork comes with a medical claim.
General liability insurance can help cover third-party bodily injury, property damage claims, and related legal costs as a result of your operations.
A burst pipe causes water damage in your office overnight, soaking computers, a plotter, and other business property. With client deadlines on the calendar, the damage quickly disrupts your busy schedule.
A business owner’s policy (BOP) typically bundles general liability, commercial property protection, and business interruption coverage to help pay for damages, repairs, and lost income so you can get back to work quickly.
Your boundary survey is challenged by a neighbor after the client starts construction. Resolving the error means additional survey work, delays, and a costly dispute.
Professional liability insurance, also known as errors & omissions (E&O) coverage, can help protect against claims alleging mistakes or negligence in your professional work. It may also help cover legal defense costs, settlements, and judgments for covered claims, up to your policy limits.
Your survey technician is carrying heavy equipment down a steep embankment when they lose their footing and badly injure an ankle. They need medical treatment and several weeks away from fieldwork. Workers’ compensation insurance can help cover their medical bills and may replace a portion of their wages as they recover.
Workers’ comp is often legally required and can help protect your business from costly claims, as well as taking care of your crew if they suffer a work-related illness or injury on the job. Even if you operate solo, workers’ compensation insurance is typically recommended, because many personal health insurance policies don’t cover work-related injuries.
For example, you’re working an out-of-town project and lock your laser levels, tripods, measuring wheels, and field accessories inside your field truck outside your hotel. When you wake up the next morning, the vehicle has been broken into, and thousands of dollars in critical surveying gear is gone.
Contractor’s equipment and small tools coverage, also known as inland marine insurance, typically can help pay to replace or repair covered equipment when it’s stolen or damaged in transit or at a field location up to your policy limits.
Who Needs Land Surveyor Insurance?
Surveying covers a range of specialties, and each brings its own mix of professional, field, and equipment risks. You may want to consider land surveyor insurance if you’re a:
- Land surveyor determining property boundaries, mapping elevations, and assessing site conditions, where inaccurate data can lead to disputes, construction delays, or costly client claims.
- Geomatics engineer collecting and analyzing spatial data with GNSS, GIS, LiDAR, and other technologies, where an error can carry through to design, planning, or construction decisions.
- Boundary consultant researching deeds, survey records, and property-line issues, where inaccurate analysis can contribute to encroachment disputes or legal action between property owners.
- Mapping specialist producing maps and spatial data for clients, where inaccurate or incomplete information can affect planning, design, or construction decisions.
- Topographic surveyor mapping elevations, contours, and site features, where incorrect measurements can affect grading, drainage, or construction plans.
- Construction surveyor performing construction staking, establishing layouts, elevations, and reference points for buildings, roads, and other projects, where a positioning error can lead to rework, delays, or costly construction mistakes.
- GIS mapping business managing geographic databases and digital mapping projects, where corrupted, inaccurate, or compromised data can disrupt client work and expose sensitive information.
- Contract surveyor working independently for property owners, developers, or contractors, where a professional claim or loss of expensive field equipment can hit especially hard.
- Drone mapping specialist using aerial imagery and UAV technology to collect site data, where an accident causing third-party damage or equipment loss can quickly turn an efficient survey into a costly problem.
Whether you work solo or manage a surveying firm, insurance can help protect your professional work, your equipment, and the business you’ve built.
How Much Does Land Surveyor Insurance Cost?
Land surveyor insurance that combines core policies like general liability, business owner’s policy (BOP), professional liability, workers’ comp, and contractor’s equipment & small tools insurance typically costs¹ between $XX and $XX per month, depending on which policies you buy.
Your final premium will depend on factors such as your location, the type of work you do, the number of employees you have, your annual revenue, and your claims history.
| Coverage Type | Median Monthly Costs1 |
|---|---|
| General Liability Insurance | $47 per month |
| Business Owner’s Policy | $47 per month |
| Professional Liability Insurance | $41 per month |
| Workers’ Comp Insurance | $131 per month |
| Contractor’s Equipment and Small Tools | $27 per month |
1 Pricing based on general liability, BOP, professional liability, workers’ comp, and contractor’s equipment and small tools policies purchased from Simply Business by customers identifying as a “land surveyor” between July 1, 2025 and December 31, 2025.

Try Our Land Surveyor Insurance Calculator
Get a quick estimate in just 3 steps.
Answers to More Questions About Land Surveyor Insurance
Land surveyor insurance is a collection of separate policies commonly bought by surveyors to help protect against risks such as professional errors, third-party injuries and property damage, employee injuries, and stolen or damaged equipment.
Because land surveying is a state-licensed profession, insurance needs are often driven by state regulations and client contracts. If you have employees, even part-time, workers’ compensation insurance is required in most states. Additionally, many state licensing boards, local municipalities, and clients require proof of professional liability or general liability insurance before you can obtain a license, bid on projects, or pull permits.
Be sure to check your state licensing board rules and project contracts to confirm the specific coverage limits required for your business.
Clients rely on surveyors to provide accurate professional information. And a boundary error, topographic survey mistake, or inaccurate GIS data can lead to construction delays, property disputes, or financial losses.
Professional liability insurance, also known as E&O coverage, can help cover certain claims alleging mistakes or negligence in your professional services.
General liability primarily addresses physical risks, such as a client tripping over your field equipment or your crew accidentally damaging someone’s property. Professional liability addresses claims arising from your professional services, such as an incorrect boundary determination or a mapping error that causes a client financial loss.
Many surveyors need both because the policies protect against different types of claims.
No. General liability is generally for third-party bodily injury and property damage, not financial losses caused by mistakes in your professional services.
If an inaccurate boundary survey leads to a client dispute, construction delay, or other financial loss, professional liability is the coverage that typically addresses this type of claim, subject to your policy terms.
Surveying equipment often travels from your office to field locations, where a standard business property policy may not provide enough protection.
Contractor’s equipment and small tools insurance, also known as inland marine coverage, can help protect covered total stations, GNSS rovers, 3D laser scanners, LiDAR equipment, and other mobile surveying gear from risks such as theft or damage in transit or in the field.
If your business owns vehicles used to travel between offices and survey sites or transport employees and equipment, you will likely need commercial auto insurance.
As of the date of this article, Simply Business doesn’t offer commercial auto insurance, but our licensed insurance agents can help you find trusted providers who do.
If you store GIS databases, CAD files, client information, digital site plans, or other business data, a cyberattack or data loss can interrupt your work and potentially impact your clients.
Cyber insurance can help with certain costs associated with data breaches, ransomware, data recovery, cyber extortion, and business interruption, depending on the policy.
Yes. COIs for most policies from Simply Business are available soon after you purchase your coverage. And you can download and share your COI instantly through your online account or right from your phone. That can be useful when a commercial client, municipality, lender, or other party needs proof of insurance before a project or contract can move forward.
Your insurance premium depends on several factors, including, but not limited to:
- The surveying and mapping services you provide
- Your annual revenue and payroll
- The size of your team
- The size and complexity of your projects
- Whether you use subcontractors
- Your geographic service area
- The value of your surveying and mapping equipment
- Your claims history and years in business
- Your chosen policy types, coverage limits, and deductibles
Larger or more complex projects and services with greater potential client financial exposure can also affect your coverage needs and limits.
Before signing on the dotted line, consider asking:
- Does my policy meet the insurance requirements in my client contracts or professional licensing rules?
- Are my coverage limits appropriate for the size and scope of the projects I take on?
- Does my professional liability policy cover all the surveying, mapping, GIS, and consulting services I perform?
- How does my policy distinguish professional errors from general liability claims?
- Are my total stations, GNSS rovers, LiDAR equipment, scanners, and other field instruments potentially covered in transit and at survey sites?
- Are my surveying drones covered for physical damage, or do I need separate drone liability coverage?
- Does my personal vehicle use require commercial auto coverage?
- Do I need cyber insurance for GIS databases, CAD files, client information, or other digital data?
- Are subcontractors covered, or do they need to carry their own insurance?
- Can I download a COI immediately when I need one for a new contract?
Our licensed agents can walk you through these questions — give us a call.

Why Small Businesses Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

Start your quote
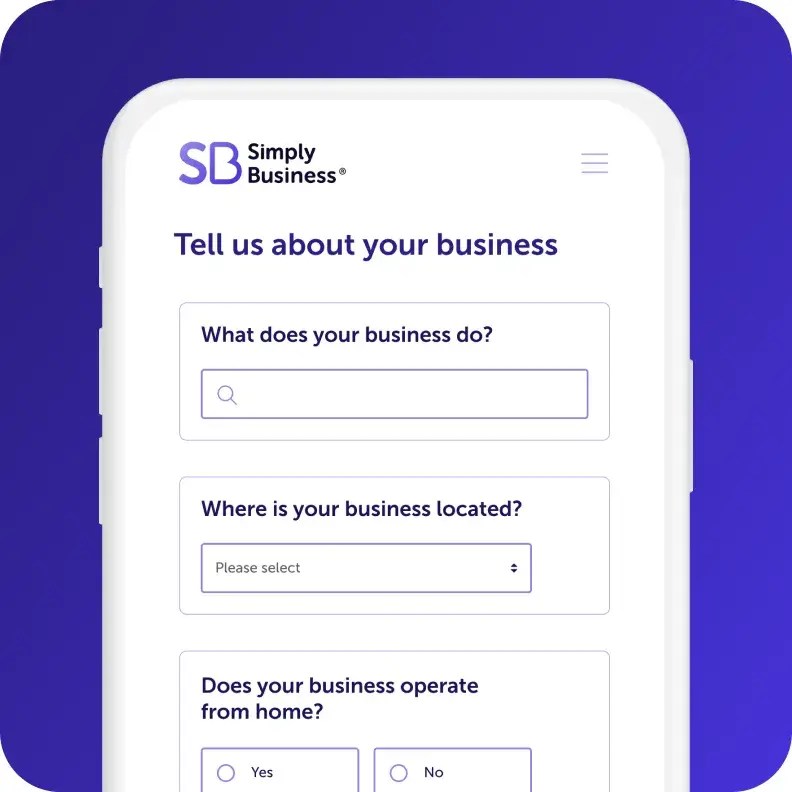
Answer a few questions about
your business in one form.

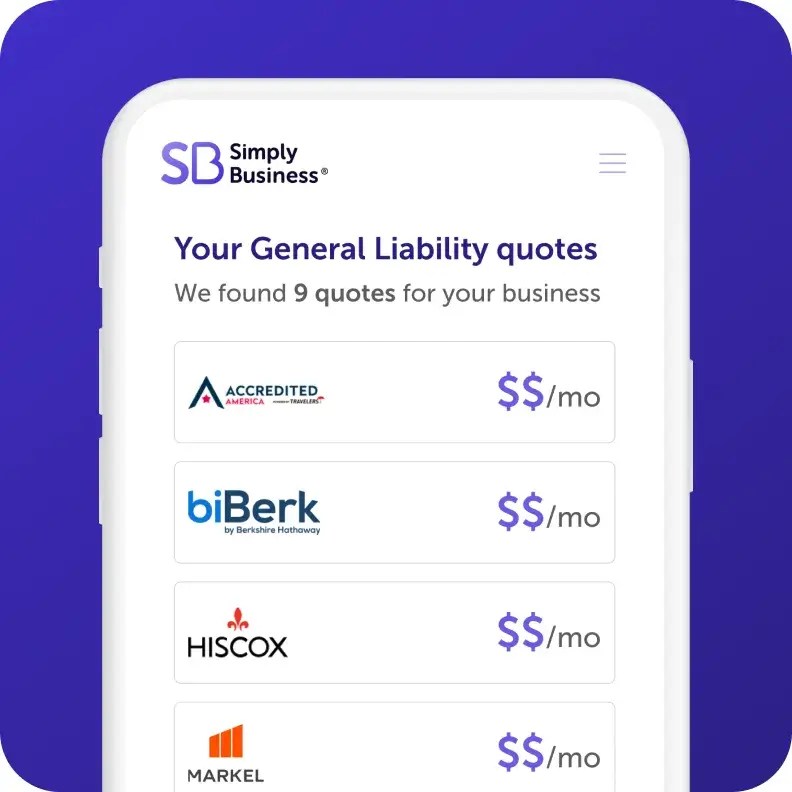
Review quotes
Compare quotes side by side from top-rated insurers and customize your coverage.

Get protected in minutes
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.

Written by
Our +1 million customers worldwide are big fans. And you will be too.
I went online, looked around, and found Simply Business. The process was so seamless. I got my certificate within minutes. It was just phenomenal.
Karen
Owner of Tangaza Bath & Body Studio LLC
With Simply Business I know I can look at different carriers, but also see all my stuff in the same place… a lot of [insurance] providers don’t offer a variety of coverage, all in one place.
Jef
Owner of Bunker83 LLC
It wasn’t overwhelming to figure out what was covered and what wasn’t covered. And the cost was competitive.

Kim
Owner of Room to Breathe Professional Organizing
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.
† Limits may vary by state and nature of your business.
‡ Displayed price is based on the lowest available coverage limit for Equipment and Small Tools policies.
Page last updated: