Blogging Insurance
Find out what insurance coverage you need as a blogger.
Compare policies from leading national insurers. Get a quote in minutes.
Over 1 million customers worldwide.

Buy instantly online.

Written by
Why Do I Need Blogger Insurance?
As a professional blogger, you write for a living. So what’s the risk in that? It turns out, there’s quite a bit. Check out this article about freelance writing that goes into some of the risks. And don’t forget about the equipment you use to create your written content. If your pricey laptop or camera gets damaged, without insurance, you could be on the hook to pay for a replacement for those items.
Below are some of the most common types of insurance policies that bloggers carry to stay protected.
What Type of Blogger Insurance Do I Need?

General Liability
A foundational insurance coverage to help handle costs from third-party accidents, property damage, and bodily injury.
From
$20.75
/month*

Business Personal Property
Coverage to replace or repair equipment, furniture, fixtures, and inventory.
What Does Blogger Insurance Cover?
Even if you’re not a “big-name writer,” you could get on someone’s radar for a high-dollar lawsuit. Don’t consider it a compliment, either. It’s all too easy for large companies and even readers to sue you for libel, copyright infringement, defamation, and more.
Plus, even if you’re found not guilty, you still have to pay for a lawyer to defend you.
The good news? Insurance for bloggers can be found at an affordable price. We can help you find a policy that can protect your freelance business and offer some peace of mind when writing.
Here are a couple of important policies that we typically recommend to bloggers.
General Liability Insurance
When you think of general liability insurance (GL insurance), you probably think of policies that protect construction workers, general contractors, and workers in accident-prone industries. Well, bloggers can benefit from GL insurance too.
If someone visits your at-home office for an interview and gets injured, you could be at risk for a lawsuit. Plus, there is some legal precedent for holding bloggers accountable when a product they recommend injures a reader. Who would have thought? But it’s all the more reason to consider protecting yourself with General Liability blogging insurance.
In addition, you’re also at risk for libel, defamation, copyright infringement, and much more. Let’s look at a quick example.
Let’s say a food blogger, also known to be a local celebrity, writes a review of Nick’s Nachos, a local Tex-Mex restaurant. Unfortunately, the review isn’t so great. The blogger says the chips were stale and the restaurant was not worth the trip or cost. As a direct result of the review, Nick’s Nachos loses 30% of their annual revenue.
When Nick’s Nachos restaurant owner realizes that the blog post cost him significant business, he sues the blogger for libel.
If you’re a blogger, that example might suggest it’s time to strongly consider securing business insurance as soon as possible.
Here’s just one reason why. According to an industry benchmark study, the cost for reputational harm (e.g. slander or libel) can cost $35,000 on average.
Just imagine paying that out of your own pocket. Could you do it? Most bloggers can’t. And an expense like that might be enough to put the average freelance blogger’s business under water (and much more). But with blogging insurance, you’re covered up to your policy limits.
You can expect most general liability policies for bloggers to cover:
- Third-party property damage (aka clients or vendors)
- Third-party bodily injury
- Medical expenses
- Personal and advertising injury
- And more
General liability insurance usually does not cover:
- Personal property damage
- Professional services
- Employee injury and workers compensation
- Damage to your work
- Motor vehicles during business use
- Intentional injury or damage
- And more
Trust us, it can be worth the extra cost to get peace of mind, and especially worth it if you face a costly lawsuit.
Business Personal Property Insurance
As a blogger, you likely have a computer, but maybe you have a top-dollar camera too. These items might be crucial to your success. After all, can you imagine writing all of your content with pencil and paper? Forget it.
But computers and digital cameras aren’t meant to live forever. Sometimes accidents happen and they can get damaged, whether it’s by water, coffee, your toddler, or something else. If your lifeline for work (aka your laptop and/or camera) gets seriously damaged while you’re on the job, you’re likely responsible for a replacement, unless you have personal property insurance. If you already have personal property insurance as part of your blogging insurance, you can get reimbursement for your damaged property.
Talk about a breath of fresh air, especially if your business finances have been tight lately. It’s nice to have peace of mind, knowing you’re covered in the event of most accidents.
Why Do I Need Blogging Insurance?
The answer is simple. Blogging insurance can help protect you if you face a general liability claim, involving either an injury or accident, or more likely, a reputational claim. We can help you find a policy with the coverage that fits your needs at an affordable price. When you compare that to the cost of a lawsuit, insurance can be well worth investing in.
Sometimes, you can even write off blogging insurance on your income tax return. As always, it’s best to talk to an accountant before doing so.
In addition, blogging insurance can help you replace damaged property, including a laptop, digital camera, and other property that you use for work, up to your policy’s limits. That’s a nice added benefit.
If you have a customer-facing website, you can showcase that you’re insured too. It can make your customers feel more confident when hiring you. After all, if something happens, they know they may be entitled to compensation for any damage.
Business insurance —
a quick explainer
Learn more about policies for small businesses, what they cover, why you might need them, and how we can help – all in just 60 seconds.
Business insurance is often made up of different types of policies to cover different things, similar to how your health insurance can be made up of medical dental and vision coverage. Here are some of the ones small business owners need. General liability is kind of the Swiss army knife of insurance. It can do a lot, like help handle costs from third party accidents, property damage, bodily injury, and more. Nobody’s perfect, right? That’s what professional liability is for. It could come in handy in the event of honest mistakes or claims of negligence. Workers’ comp can protect your business and help take care of employees who get sick or injured on the job. Small businesses are big targets for cyber criminals. Cyber Insurance can help cover costs associated with stolen customer data, cyber attacks, breaches, and fraud. BOP or a business owners policy combines different types of coverages like general liability and commercial property insurance. Putting them together for you is where we come in. You tell us a bit about your business online or on the phone, and we customize the coverage options for what you do and what you need. It’s your business, it should be your insurance as well. That’s why we’re here.
Answers to More Blogger Insurance Coverage Questions
In general, it’s not required by law. But the answer depends on where your business is located and if you have employees.
If you do have employees, you’ll likely need to purchase workers compensation insurance. But, again, the law varies by state, so it’s best to check with your state to find the rules based on where you work.
Generally speaking, yes. Blogging insurance is usually a tax-deductible expense. But, as mentioned, it’s always a good idea to check with an accountant or other tax professional before claiming this expense as a deduction.
There’s no one-size-fits-all answer here. The amount of coverage you need can depend on:
- The size of your business
- Your business’s location
- Your annual revenue
- And much more
Fortunately, our insurance professionals are well-versed in helping bloggers like you. Just fill out our online quote form or give one of our licensed insurance agents a call at 844-654-7272. We can help you understand the amount of coverage that’s best for your business.
We want to make getting blogging insurance as easy as possible. To speed up the process, it helps to have this information on-hand:
- Annual revenue estimates
- Information on any previous claims
The cost of a policy can vary from blogger to blogger. It can depend on a number of factors, but generally speaking, you can expect your insurance costs to be determined by:
- Your revenue
- Your payroll
- Number of employees
- Your business location
- The services you provide
- And more
Want to get a more detailed quote? Just fill out our online quote form today to find out what several different policies may cost.

Why Small Businesses Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

Start your quote
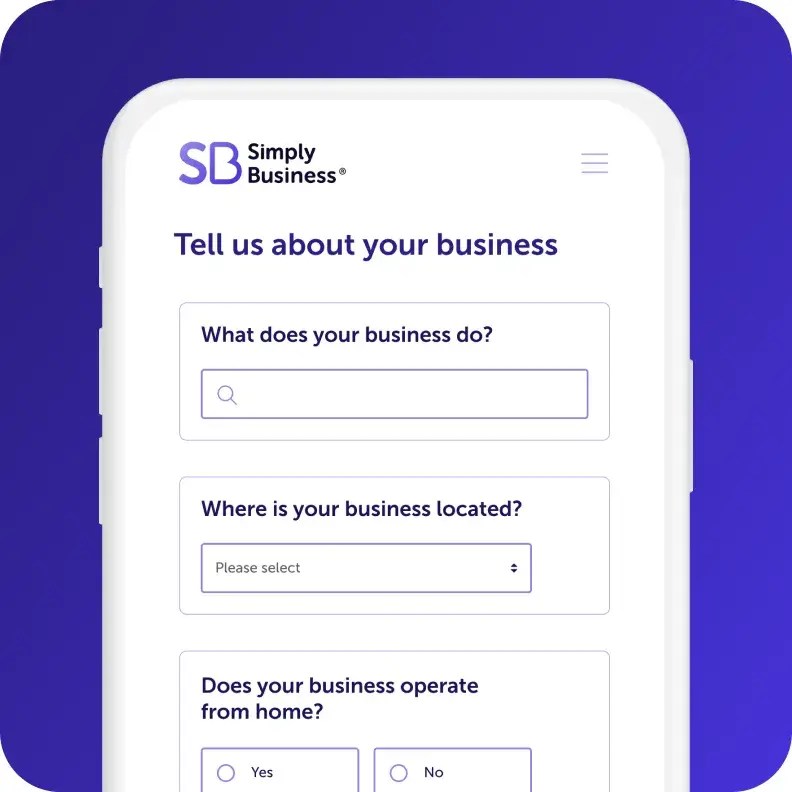
Answer a few questions about
your business in one form.

Review quotes
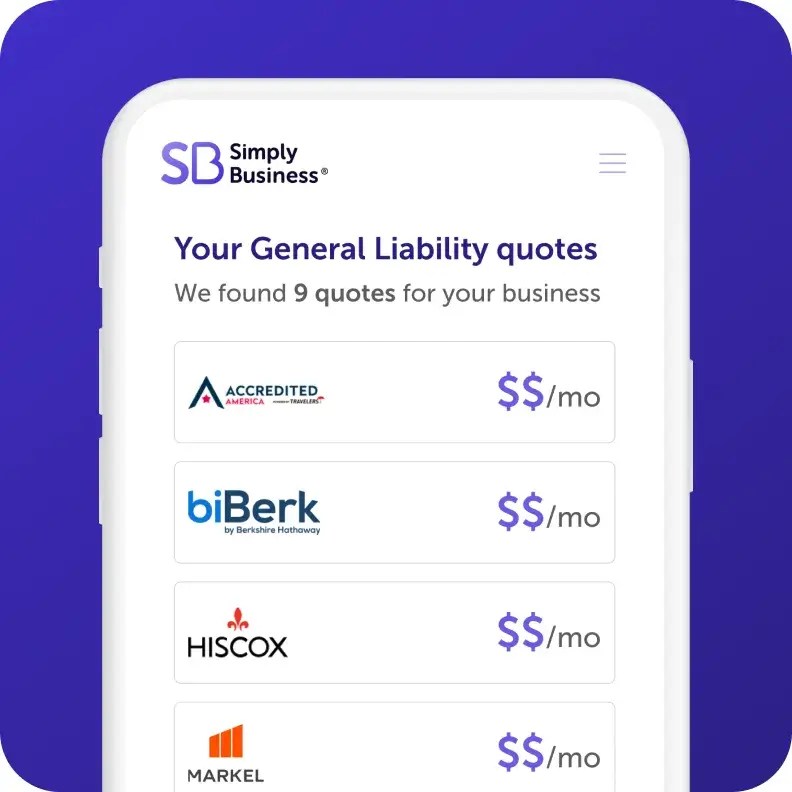
Compare quotes side by side from top-rated insurers and customize your coverage.

Get protected in minutes
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.

Written by
Our +1 million customers worldwide are big fans. And you will be too.
I went online, looked around, and found Simply Business. The process was so seamless. I got my certificate within minutes. It was just phenomenal.
Karen
Owner of Tangaza Bath & Body Studio LLC
With Simply Business I know I can look at different carriers, but also see all my stuff in the same place… a lot of [insurance] providers don’t offer a variety of coverage, all in one place.
Jef
Owner of Bunker83 LLC
It wasn’t overwhelming to figure out what was covered and what wasn’t covered. And the cost was competitive.

Kim
Owner of Room to Breathe Professional Organizing
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information
9-minute read
A General Liability Insurance Guide for Small Business
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.