Roofing insurance
One application, multiple quotes.
All in one place.
Essential Protection
From
$188
/month*
Could help cover claims against your business for property damage and injuries to others.
What’s included:
General Liability
Coverage limits: $1M to $2M†

Get multiple quotes in less than 10 mins
Essential Protection
From
$188
/month*
Could help cover claims against your business for property damage and injuries to others.
What’s included:
General Liability
Coverage limits: $100K to $2M†
Get multiple quotes in less than 10 mins
Would you rather pick and choose your coverage? Explore all options
Over 1 million customers worldwide.

Buy instantly online.

Written by
Why Do I Need Roofing Insurance?
Roofers and their employees are exposed to a lot of risks. From the potential for falls to increased risk of property damage, you need insurance that protects your business.
Below are some of the most common types of insurance policies that roofers carry to stay protected.
What Type of Roofing Insurance Do I Need?

General Liability
A foundational insurance coverage to help handle costs from third-party accidents, property damage, and bodily injury.
From
$188
/month*

Workers’ Comp
Coverage to help take care of employees who get sick or injured on the job. Most states require this coverage for small businesses with full- or part-time employees. It also can benefit business owners who don’t have employees.
From
$38.91
/month*
Business insurance —
a quick explainer
Learn more about policies for small businesses, what they cover, why you might need them, and how we can help – all in just 60 seconds.
Business insurance is often made up of different types of policies to cover different things, similar to how your health insurance can be made up of medical dental and vision coverage. Here are some of the ones small business owners need. General liability is kind of the Swiss army knife of insurance. It can do a lot, like help handle costs from third party accidents, property damage, bodily injury, and more. Nobody’s perfect, right? That’s what professional liability is for. It could come in handy in the event of honest mistakes or claims of negligence. Workers’ comp can protect your business and help take care of employees who get sick or injured on the job. Small businesses are big targets for cyber criminals. Cyber Insurance can help cover costs associated with stolen customer data, cyber attacks, breaches, and fraud. BOP or a business owners policy combines different types of coverages like general liability and commercial property insurance. Putting them together for you is where we come in. You tell us a bit about your business online or on the phone, and we customize the coverage options for what you do and what you need. It’s your business, it should be your insurance as well. That’s why we’re here.
What Kind of Insurance Do I Need as a Roofer?
“Roofing insurance” is actually a general term to describe a bundle of policies that typically provide comprehensive protection for roofers and their employees.
Every roofing contractor is unique, but there are some insurance policies every roofer needs to stay protected, considering that it’s a high-risk line of work. Take a look at what those insurance policies are, including a few reasons why you need them.
General Liability Insurance for Roofing Contractors
General liability insurance (GL) — also referred to as roofing liability insurance — covers you and your roofing business against third-party property damage or accidents, as well as the costs of a resulting lawsuit. Additionally, GL insurance can cover some of the costs of your roofing tools and equipment if damaged on the job.
OK, that was a mouthful. What exactly does all of that mean?
Let’s say your employees cover a customer’s roof with a tarp before a big overnight storm. During the rainstorm, water leaked into the homeowner’s bedroom, causing thousands of dollars in water damage and furniture replacement costs.
Without GL insurance, you’d end up footing the entire bill — but with this insurance coverage, you’re likely to be covered. Your plan may cover the costs associated with the claim – including legal fees along the way – up to your coverage limits, so you would only pay your deductible.
Property damage bills can add up. In some cases, they can be catastrophic, potentially putting your roofing business right out of, well, business. In fact, did you know that the average claim for property damage for small businesses is $30,000.
Even if you think you or your employees won’t make mistakes, you don’t know if a customer might sue you. For example, if a customer sues you for property damage you didn’t cause, you’d still have to hire a lawyer to defend you. And with an estimated 43% of small business owners reporting being threatened with or involved in a civil lawsuit, there’s a good chance it could happen to you.
Fortunately, roofing liability insurance can come in handy by paying for the costs of your lawyer, as well as any claims you may be ordered to pay.
To recap, here’s what your general liability insurance can cover:
- Bodily injury to another person (e.g., a customer)
- Third-party property damage
- Personal and advertising injury
- Medical expenses
- And more
General liability insurance usually does not cover:
- Damage to your property
- Professional services
- Workers compensation or injury to your employees
- Motor vehicles while in business use
- Expected or intentional injury or damage
- And more
Workers Compensation Insurance for Roofing Contractors
If an employee gets sick or injured while working for you, workers compensation — also known as employer liability insurance — can pay for some of the costs associated with those medical bills.
Most states require roofing businesses to carry this policy when they hire their first employee, so you may want to add it to your coverage when you start hiring.
Here’s how workers compensation insurance works: If an employee gets injured on the job, this coverage can pay for medical costs and part of lost wages (up to your policy limit). Carrying workers compensation can give you peace of mind, as having it may prevent an employee from suing your business for most workplace injury claims.
Workers compensation insurance for roofing contractors can cover:
- Medical payments
- Lost wages
- Rehabilitation expenses
- Death benefits
Why Should I Get Insurance for My Roofing Business?
We understand that it’s important to protect your budget, especially as a small business owner. So maybe you’re planning on putting off buying roofing contractors insurance, or you just don’t think you need it at all.
Here’s the thing, though — as a roofer, you and your employees are highly vulnerable to property damage claims and accidents that could ruin your business if you don’t have proper insurance protection.
For example, if you get sued over property damage to a customer’s roof — even if you know you didn’t cause that damage — you still have to hire a lawyer to defend you. That could cost a lot of money, all which would probably come out of your own finances if you didn’t have roofer insurance.
Additionally, your state likely requires you to carry insurance in order to get your contractor’s license. It’s often illegal to work as a roofing contractor without a license, so having a roofing liability insurance policy is critical to being on the right side of the law (learn more about how to get a contractor’s license in your state).
All in all, having business insurance means you can:
- Pay for costs and claims from third-party property damages and accidents (up to your coverage limits).
- Help you get more customers, as it shows you take your business — and safety — seriously.
- Assist in hiring and retaining experienced roofing employees.
- Keep you on the right side of the law, as many states require some form of roofing contractor insurance.
- Give you peace of mind, knowing that you probably won’t have to pay for most damages out of your own pocket (or your family’s).
Good news: when you get your roofing insurance policy through Simply Business, we’ll provide you with a certificate of insurance (COI) so you can apply to get your license or show customers you have coverage.
What Does Plumber Insurance Cover?

What Does Roofing Insurance Cost
Try our insurance calculator.
Get a quick estimate in just 3 steps.

Answers to More Roofing Insurance Coverage Questions
The answer to this question largely depends on the state where you live, as well as the various locations where you work as a roofer. However, even if you’re not required to have roofing liability insurance in your state, there are several reasons you should carry it:
- Roofing liability insurance can prevent you from paying for property damage and accidents out of your pocket.
- It can cover legal costs if your business is sued.
- Customers may be reluctant to hire you unless you have the right insurance coverage.
- It might be able to help you get approved for a business license and any contractor’s license you may need.
You can typically deduct the cost of your business insurance premiums, as they are considered a business expense by the IRS. However, we’re not tax experts, so we recommend talking to an accountant about your business’s tax deductions.
Every roofing contractor has different requirements, which is why we help you find policies based on:
- The size of your roofing business
- Where you’re located
- Your annual revenue (even if it’s an estimate)
- And more
Our quote form helps us determine your recommended amounts of coverage from top insurers. If you have more questions or want to chat with one of our licensed insurance agents, we’re here to help!
If you’re shopping for a roofing insurance quote, you probably don’t want to spend a lot of time going through a quote form. To speed you through the process and get your quotes in under 10 minutes, be sure to have the following information at hand:
- Annual revenue estimates
- Payroll estimates
- Information on any previous claims
Yes, insurance requirements for roofers can differ from state to state. Each state may require different insurance policies in order to be a licensed contractor. We can cut through the confusion by providing you with recommended roofing liability insurance options based on where you operate.
Roofing insurance covers the most common risks you face as a roofing professional. While you can customize your policy to fit your unique needs, your roofing insurance may cover:
- Property damage. Let’s say you slip off a ladder while coming down from a customer’s roof. You catch yourself, but in the process, you accidentally kick your foot through the homeowner’s bedroom window. Roofing insurance can cover the cost to replace that broken window, as well as any other property damage you or your employees may cause.
- Accidents. If during the process of shingling a customer’s roof, a few shingles fall and hit the homeowner’s dog, your policy can pay for some or all of any resulting vet bills. (You’ll have to buy the dog treats on your own, though.)
- Reputational damage. Let’s say your employee badmouths a customer on Facebook and that customer finds out about the post. If your customer sues for slander or reputational damage, your roofers liability insurance may be able to cover any resulting legal bills and damages.
While roofing insurance costs vary from business to business, you can get a good estimate for what you may pay based on:
- Your business’s payroll
- The location of your business
- The type of roofing services you provide
- And more
Want to find out how much your roofing insurance may cost? Click here to answer a few questions so we can help you learn how much you can expect to pay for your roofing contractors insurance.
If you perform services other than roofing, our licensed agents can help you find the right insurance coverage that can protect you during all of your work.

Why Small Businesses Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

Start your quote
Answer a few questions about
your business in one form.
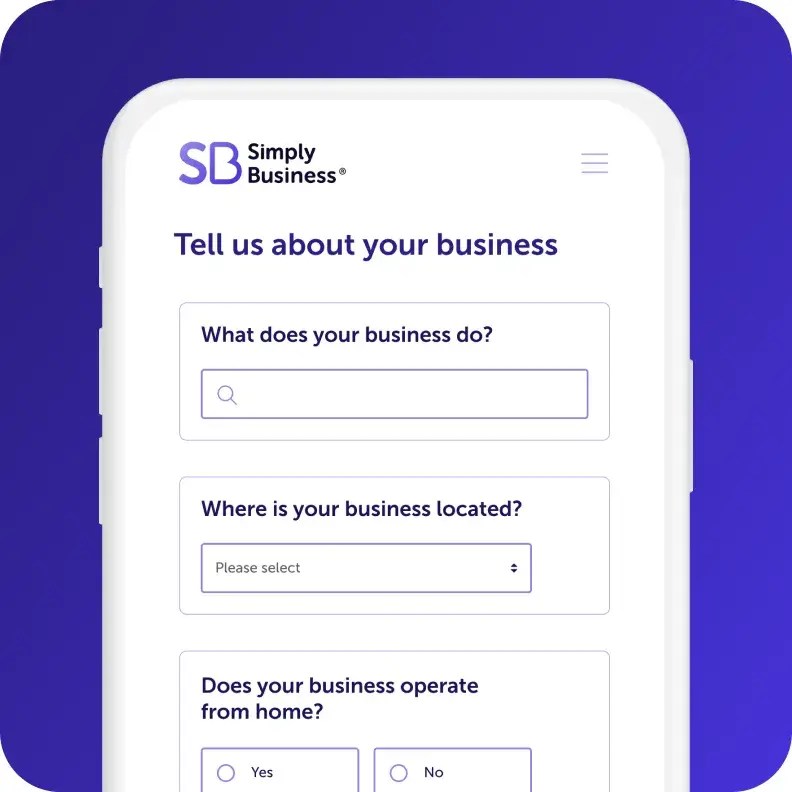

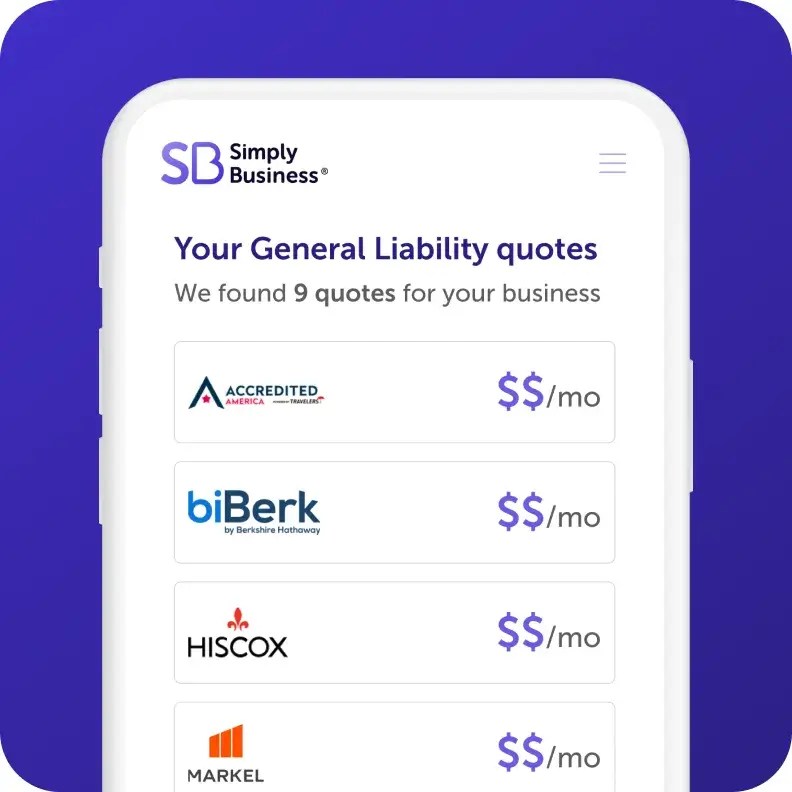
Review quotes
Compare quotes side by side from top-rated insurers and customize your coverage.

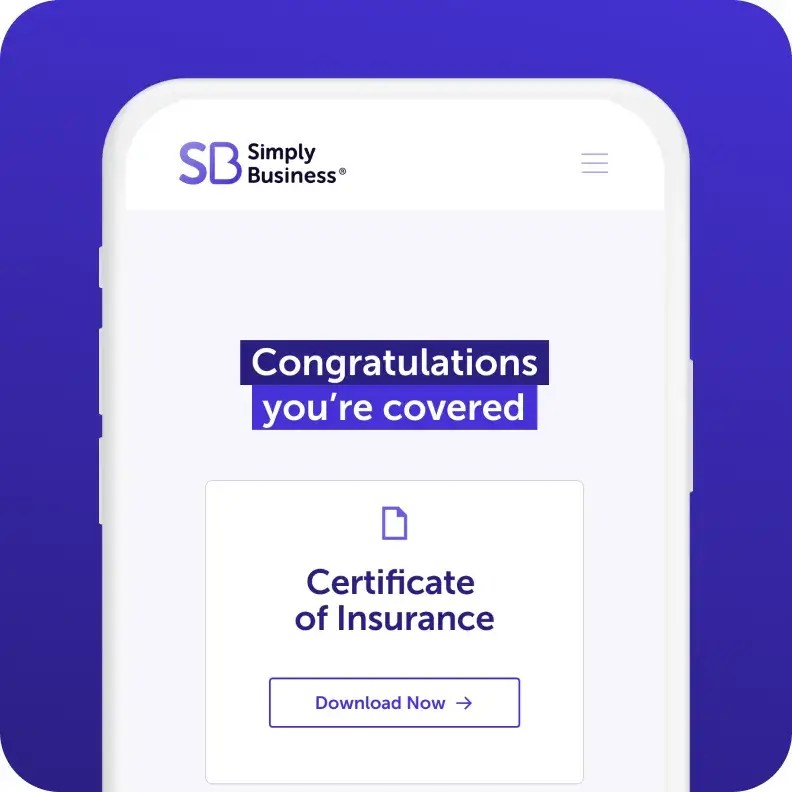
Get protected in minutes
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.

Written by
Our +1 million customers are big fans. And you will be too.

I went online, looked around, and found Simply Business. The process was so seamless. I got my certificate within minutes. It was just phenomenal.
Karen
Owner of Tangaza Bath & Body Studio LLC
With Simply Business I know I can look at different carriers, but also see all my stuff in the same place… a lot of [insurance] providers don’t offer a variety of coverage, all in one place.
Jef
Owner of Bunker83 LLC
It wasn’t overwhelming to figure out what was covered and what wasn’t covered. And the cost was competitive.

Kim
Owner of Room to Breathe Professional Organizing
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information
9-minute read
A General Liability Insurance Guide for Small Business
4-minute read
The Basics of Workers’ Comp
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.
† Limits may vary by state and nature of your business.
Page last updated: