Plumber insurance
One application, multiple quotes.
All in one place.
Essential Protection
From
$41.67
/month*
Could help cover claims against your business for property damage and injuries to others.
What’s included:
General Liability
Coverage limits: $1M to $2M†

Get multiple quotes in less than 10 mins
Essential Protection
From
$41.67
/month*
Could help cover claims against your business for property damage and injuries to others.
What’s included:
General Liability
Coverage limits: $1M to $2M†
Get multiple quotes in less than 10 mins
Would you rather pick and choose your coverage? Explore all options
Over 1 million customers worldwide.

Buy instantly online.

Written by
Plumber Business Insurance
Plumber business insurance is a group of policies—general liability, a business owner’s policy, workers’ compensation, and equipment and tools coverage—that protects your plumbing business from accidents, property damage, injuries, and stolen equipment. Simply Business lets you compare quotes from multiple top-rated carriers in one place, so you can find the right coverage at the right price in minutes.
Why Do Plumbers Need Business Insurance?
Plumbers face daily risks that a single mistake—a loose fitting, a dropped tool, an injured crew member—can turn into a costly claim. Plumber business insurance helps cover those risks so an accident doesn’t drain your profits or shut down your business.
Whether you’re a solo operator or run a full crew, the right mix of policies protects your livelihood from accidents, stolen tools, and jobsite injuries. Below are the most common types of coverage plumbers carry to stay protected.
What Type of Plumber Insurance Do I Need?

General Liability
A foundational plumber insurance coverage to help handle costs from third-party accidents, property damage, and bodily injury.
From
$41.67
/month*

Business Owner’s Policy (BOP)
General liability, property insurance, and more all in one convenient package.
From
$33.75
/month*

Workers’ Comp Insurance
Coverage to help take care of employees who get sick or injured on the job. Most states require this coverage for small businesses with full- or part-time employees. It also can benefit business owners who don’t have employees.
From
$38.91
/month*

Contractor’s Equipment and Small Tools Insurance
Also known as inland marine insurance, this coverage can financially protect equipment and inventory that’s in transport or stored offsite.
From
$20.83
/month‡
What Does Plumber Insurance Cover?
Without the right insurance, one unexpected mishap can drain your profits. Here’s how plumber insurance can help protect you from these common risks:
You’re replacing a kitchen faucet and a connection isn’t seated properly, causing water to soak an expensive rug before you can isolate the line. A general liability policy could help cover the damage and other third-party claims.
Even the most skilled plumbers can face disputes over completed work. Say you install a new shower system, but a small leak behind the wall goes unnoticed and causes hidden water damage over time. Adding a contractor’s errors and omissions endorsement to your general liability policy could help cover the cost to correct faulty work and protect you against a negligence claim.
You’ve been awarded a contract for a multi-unit plumbing installation, but the property owner requests proof the job will be finished as promised. That’s where a surety bond comes in. It’s a financial guarantee that protects your client if you can’t meet your contractual obligations. If the job isn’t finished or doesn’t meet agreed-upon standards, the bond can compensate the customer for their losses.

After a weekend storm, you find several inches of water on the storage area floor—damaging pipe threaders, fittings, and key paperwork. A business owner’s policy (BOP) typically bundles general liability, commercial property protection, and business interruption coverage to help pay for repairs, equipment replacement, and lost income—so you can get back quickly to serving clients.
One of your plumbers strains their back while carrying a new water heater down a set of narrow stairs. Workers’ compensation insurance can help to cover the medical bills and provide wage replacement for their work-related injuries as they recover.
Having workers’ comp insurance is often legally required and can protect your business from costly claims, as well as taking care of your crew if they suffer a work-related illness or injury. Even if you operate solo, we recommend workers’ comp, because many health insurance policies won’t cover work-related injuries.
You show up to the site one morning and find your trailer broken into — compressors, nail guns, and saws gone. Contractor’s equipment and small tools insurance, also known as inland marine insurance, can help pay to replace or repair your stolen or damaged equipment, whether it’s on the move or at a jobsite.
How Much Does Plumber Insurance Cost?
Most plumber businesses pay a median price of $69 per month for small business insurance coverage. Your final premium will depend on factors like your location, number of employees, specific work you do, and your claims history.
Here’s a look at the median costs1 for the most common policies plumber businesses purchase from Simply Business:
| Insurance Type | Estimated Median Monthly Price |
| General liability | $92 |
| Business owner’s policy (BOP) | $47 |
| Workers’ compensation | $126 |
| Inland marine | $27 |
1Data from Simply Business customers specializing as a “plumber” who purchased at least one or a combination of general liability, BOP, tools and equipment, or workers’ compensation policies from July 1, 2025 to December 31, 2025. Reflected price tiers may not include purchase of all available policies under plumber insurance.

Get Plumber Insurance Quotes
Try our plumber insurance calculator.
Get a quick estimate in just 3 steps.
Answers to More Plumber Insurance Coverage Questions
Plumber insurance is a collection of separate policies that can help protect your business, your gear, and your livelihood.
Most states require workers’ compensation if you have employees, and liability insurance is often a prerequisite for professional licensing. We recommend double-checking your local and state regulations to stay compliant.
Even if you don’t have employees, many general contractors and commercial clients require solo plumbers to carry their own workers’ compensation policy to step onto a jobsite. Additionally, because personal health insurance policies typically exclude work-related injuries, a solo policy can help cover your medical bills if you’re injured on the job.
General liability insurance is designed to help cover resulting damage you cause to someone else’s property. Whether the break happens while you’re on the job or the damage is discovered after you’ve finished, your policy can help pay for repairs to floors, walls, or personal belongings. Though it typically does not cover the cost to replace the broken pipe itself.
Potentially, yes—and this is where your general liability policy’s completed operations coverage comes in. If damage from your work shows up after you’ve left the job site, completed operations coverage can help cover the resulting property damage claim. The policy may also help with legal fees incurred when defending against those claims.
Your tools are the heart of your business, but a standard business owner’s policy typically only protects them while they’re at your main shop. Because your work takes you on the road, inland marine insurance—often called contractors’ tools and equipment coverage—is there to help protect your gear while it’s in your van or at a job site.
The cost for your insurance coverage is usually determined by several factors, such as:
- The type of work you do
- Where your business is located
- Your annual revenue
- The types of policies and limits you choose
Other factors may also include your claims history and how long you’ve been in business.
Generally, yes. Commercial and industrial projects typically carry higher premiums because the liability exposure is greater—larger properties, more complex systems, and the potential for significantly higher water damage claims.
If you’re thinking of buying plumber liability insurance, we recommend having the following information on hand when using our plumber insurance calculator:
- The state where you do business
- Your type of business or trade
- Your annual revenue estimates
This information can make it easier to get a quote from one of our insurers.
COIs for most insurance policies are available as soon as you purchase your policy. Once available, Simply Business provides instant digital certificate of insurance access through your online account any time of day. So if a general contractor needs proof of coverage before you start work on Monday morning, you can pull your COI and send it over in minutes.
Instead of requesting a single quote from one carrier, Simply Business lets you compare quotes from 18 top-rated insurers side by side in one application—so you can see your options and choose the coverage and price that fits your plumbing business, rather than committing to the first quote you receive.

Why Plumbers Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your plumbing business.

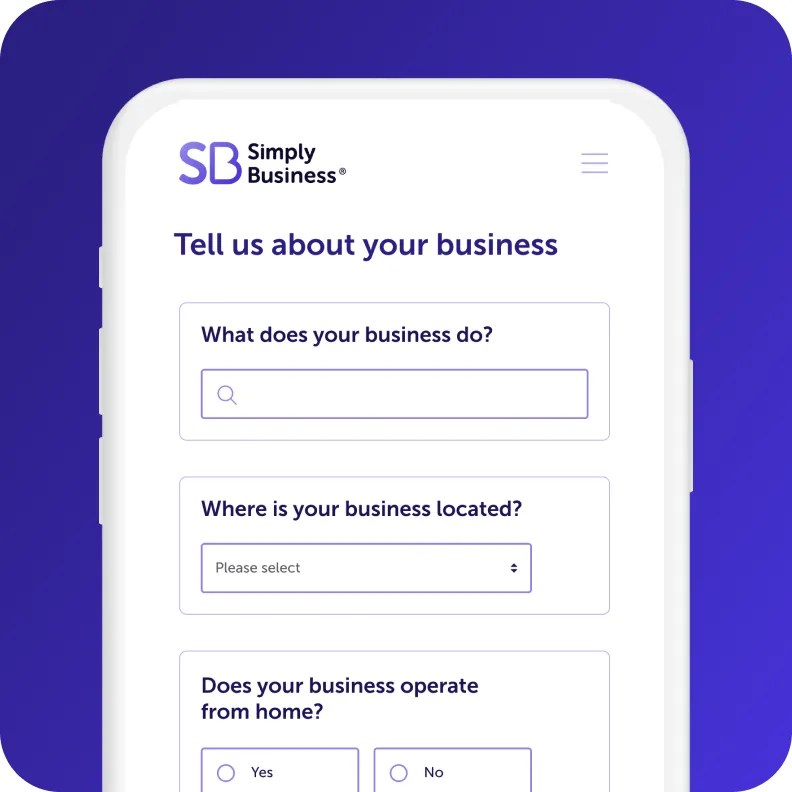
Start your quote
Answer a few questions about
your business in one form.

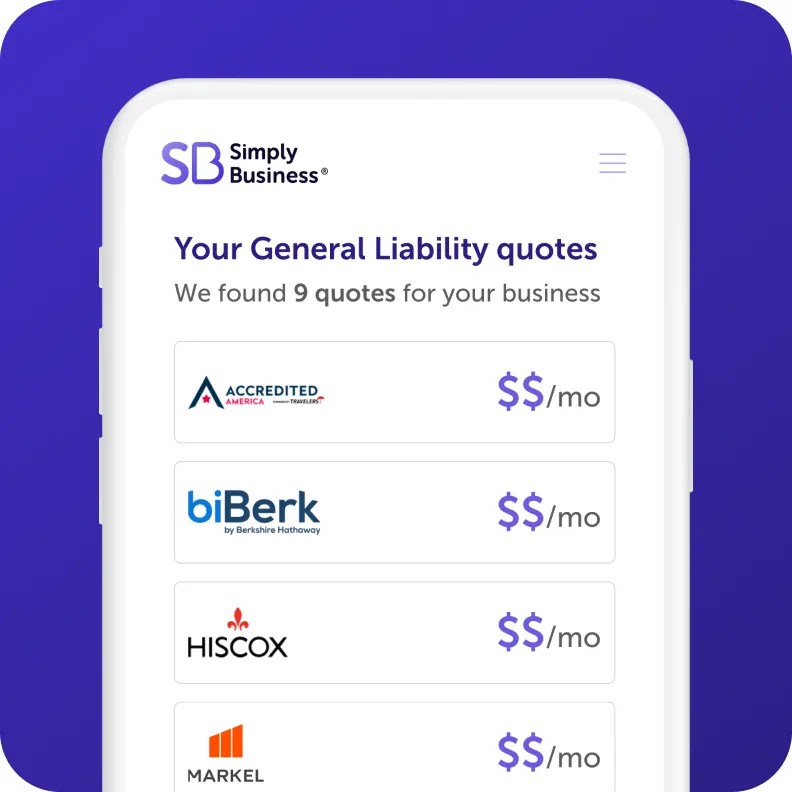
Review quotes
Compare quotes side by side from top-rated insurers and customize your coverage.

Get protected in minutes
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.

Written by
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.
† Limits may vary by state and nature of your business.
‡ Displayed price is based on the lowest available coverage limit for Equipment and Small Tools policies.
Page last updated: