Technology Services Insurance
Find out what insurance coverage you need as a technology services provider.
Compare policies from leading national insurers. Get a quote in minutes.

Over 1 million customers worldwide.

Buy instantly online.

Written by
Stay Ahead of The Curve With Technology Services Insurance
Being a business owner is rewarding yet challenging. Besides keeping pace with changing technologies and managing client expectations, you also have to be ready to handle any curveballs. Being prepared is the best way to stay ahead of the curve and be set up for success in any scenario.
Below are some of the most common types of insurance policies that technology service providers carry to stay protected.
What Type of Technology Services Insurance Do I Need?

General Liability
A foundational insurance coverage to help handle costs from third-party accidents, property damage, and bodily injury.
From
$20.75
/month*

From
$25.83
/month*

Workers’ Comp
Coverage to help take care of employees who get sick or injured on the job. Most states require this coverage for small businesses with full- or part-time employees. It also can benefit business owners who don’t have employees.
From
$38.91
/month*
Business insurance —
a quick explainer
Learn more about policies for small businesses, what they cover, why you might need them, and how we can help – all in just 60 seconds.
Business insurance is often made up of different types of policies to cover different things, similar to how your health insurance can be made up of medical dental and vision coverage. Here are some of the ones small business owners need. General liability is kind of the Swiss army knife of insurance. It can do a lot, like help handle costs from third party accidents, property damage, bodily injury, and more. Nobody’s perfect, right? That’s what professional liability is for. It could come in handy in the event of honest mistakes or claims of negligence. Workers’ comp can protect your business and help take care of employees who get sick or injured on the job. Small businesses are big targets for cyber criminals. Cyber Insurance can help cover costs associated with stolen customer data, cyber attacks, breaches, and fraud. BOP or a business owners policy combines different types of coverages like general liability and commercial property insurance. Putting them together for you is where we come in. You tell us a bit about your business online or on the phone, and we customize the coverage options for what you do and what you need. It’s your business, it should be your insurance as well. That’s why we’re here.
What Does Technology Services Insurance Cover?
We understand that even thinking about business insurance can be overwhelming, so we do our best to give you the exact information you need without all of the heavy legal jargon. For starters, it’s helpful to know that there are three different types of business insurance you may purchase. Second, you may not be required to have all of the policies we’ll cover.
General Liability Insurance
When you start to consider tech services insurance, general liability insurance is likely what comes to mind. As the name suggests, this kind of insurance is the most generalized type. It covers bodily injury, property damage, and third-party accidents. For reference, a “third party” usually includes your clients or vendors. When you choose a general liability insurance plan, you also may have the option to add “contents coverage,” which may reimburse you for stolen property.
Even though offering technology services doesn’t seem inherently dangerous, accidents are possible with any business. The average claim for property damage or accidents in small businesses is $30,000. Without liability insurance, you would likely have to pay the entire bill yourself. We’re going to go out on a limb and guess that that’s not what you dream about spending $30,000 on.
If working in tech doesn’t seem as dangerous as, say, being a stunt professional, then what does business insurance cover? Here’s a scenario: you’re in a meeting with a client where you’re explaining how cloud backup works. You’re using dry-erase markers as props to illustrate your point, and in an accidental swoop, you knock over a cup of coffee, which ruins one of the client’s laptops.
Your client sues for the cost of replacing the laptop, and you either need to pay a settlement or for legal fees. Without business insurance, all of these costs would fall on your shoulders. However, if you have general liability insurance, your policy would defend the lawsuit and pay for some of — and potentially all of — any settlements up to your policy limits.
So what does general liability insurance typically cover in a technology services business? Here’s a recap:
- Third-party property damage (aka clients or vendors)
- Bodily injury
- Medical expenses
- Personal and advertising injury
- And more
General liability insurance usually does not cover:
- Personal property damage
- Professional services
- Employee injury and workers compensation
- Damage to your work
- Motor vehicles during business use
- Intentional injury or damage
- And more
Professional Liability Insurance
You give your best effort on every project, and clients trust your expertise. What happens if a client claims you did something that caused their business harm, though?
You may be able to use your professional liability insurance (sometimes referred to as errors and omissions insurance) to defend your reputation and protect your finances.
As someone working in technology services, you’re offering a professional service. As a result, clients can sue you for negligence and damages, whether you agree with the claim or not. Professional liability insurance can cover you if a client claims that you, your employees, or your business were negligent.
What does “negligence” look like for technology service providers? Imagine you propose a timeline for a project after the client has made it clear that the product timeline is crucial to them. You’re eager to please, so you get started on the work right away. However, you have a few setbacks and miss a couple of key deadlines. These deadline changes have set your client’s operations back significantly, and they file a claim against your company for negligence.
What options do you have? You could pay a settlement out of court or get a lawyer to defend the claim. Whether the courts determine you were negligent or not, you’ll likely be walking away with some bills to be paid. Without professional liability insurance, you would have to find the money in your business or personal finances to pay for the incident. With professional liability insurance, your policy would offset these costs, potentially saving your business.
Let’s review the scenarios that professional liability insurance typically covers:
- Legal defense costs
- Omissions or alleged omissions
- Negligence or alleged negligence
- Claims and damages
- And more
Having professional liability insurance does not usually protect you from:
- Property damage
- Intentional acts and omissions
- Bodily injury
- Medical expenses
- And more
Workers Compensation Insurance
Growing your business and bringing on employees is an exciting development, but one that comes with more responsibility. In most cases, the law requires you to have workers compensation insurance if you have part-time or full-time employees. This type of insurance policy covers medical bills, lost wages, and any legal costs associated with an employee who gets sick or hurt on the job.
Workplace injuries are expensive, so having workers compensation insurance is critical. The average cost of workers comp claims is $40,051, and even sprains or strains can cost businesses more than $30,000 an incident.
Workers compensation insurance for tech businesses can cover:
- Medical payments
- Lost wages
- Rehabilitation expenses
- Death benefits
Why Should You Get a Technology Provider Insurance Policy?
Stop and reflect on all the hours you’ve dedicated to learning your craft and building your business. You should be proud! It takes courage to chart your own path, and you deserve to continue to grow your business for as long as you’d like.
While thinking about the scenarios that you’d need to use your business insurance can be daunting, getting covered should be a happy occasion. After all, you get insurance for something that needs protecting. If you’re concerned about adding a monthly bill, know that you don’t need to pay for a large one-size-fits-all policy.
Your policy premiums depend on how many employees you have, your business location, the types of tech services you provide, your estimated revenue, and more. You can answer a few questions here to get a tailored estimate.
The average costs that uninsured small business owners are exposed to include:
- $30,000 for property damage or accident claims
- $39,000 for work injury claims
- $50,000 for reputational harm claims (e.g., slander or libel)
- $20,000 for a client slip-and-fall case
When it comes to your business and livelihood, it’s better to be safe than sorry. Forty-three percent of small business owners have reported being threatened with or involved in a civil lawsuit, which means it could happen to you too.
The real kicker is that you don’t necessarily have to do anything wrong for charges or costs to befall you. You could provide a reputable service, but if a customer decides that they’re dissatisfied with an outcome, they could sue. Even if the court determines you’re in the right, you could still rack up your own legal fees.
If you were to have technology providers insurance, though, those expenses and legal fees likely wouldn’t have to come from your personal finances.
Business insurance comes with benefits that have nothing to do with accidents or negligence.
Showing proof of insurance can help you:
- Rent out a room or space for your business
- Convince other people to work with you
- Earn clients’ confidence
- Open another location
- And more!
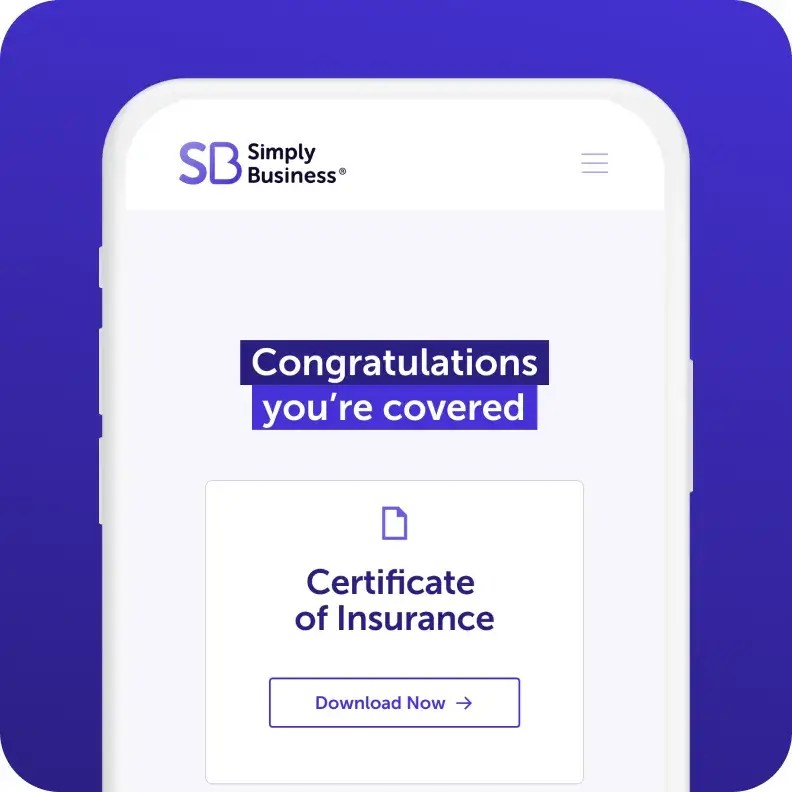
When you buy insurance through Simply Business, you’ll receive a certificate of insurance (COI), so you can provide proof of coverage.
Answers to More Technology Services Insurance Coverage Questions
Laws about business insurance vary from state to state, so you may not be required to have tech business insurance. We always recommend it, though. Additionally, if you have employees, you’ll need to have workers compensation coverage.
Technology service providers can typically deduct insurance premiums from their business income tax filings. We strongly recommend checking with an accountant for more information about your state’s tax laws.
Your business details determine your insurance policy needs, and the level of coverage depends on a few factors:
- The size of your business
- Your business’s location
- Your annual revenue
- And more
Our quote form considers your details to provide recommended coverage amounts. If you have more questions, our licensed insurance agents will be happy to assist you!
Getting an insurance quote is an easy process, but you will need to provide some information. Here’s what you should have on hand before getting started:
- Annual revenue estimates
- Payroll estimates
- Information on any previous claims
Small business insurance requirements are handled at a state, not federal, level. Our quote form and insurance agents consider your location and can help you understand your state’s requirements.
A comprehensive insurance product — one that includes general liability, professional liability, and workers compensation — can cover:
- Bodily injury
- Accidents and damages
- Employee injuries
- Unintentional mistakes
- And more
Coverage amounts and monthly premiums are customized for each business, and factors such as the type of work you do and whether or not you have employees affect types of coverage available. Policy pricing is also impacted by:
- Payroll estimates
- The location of your business
- The specific services you offer
- And more
Want to see how much your technology services insurance may cost? Just click here to answer a few questions and get free quotes to compare policy prices.
Every business owner is unique, and our licensed agents can help you find insurance that offers appropriate protection for your other services.

Why Small Businesses Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

Start your quote
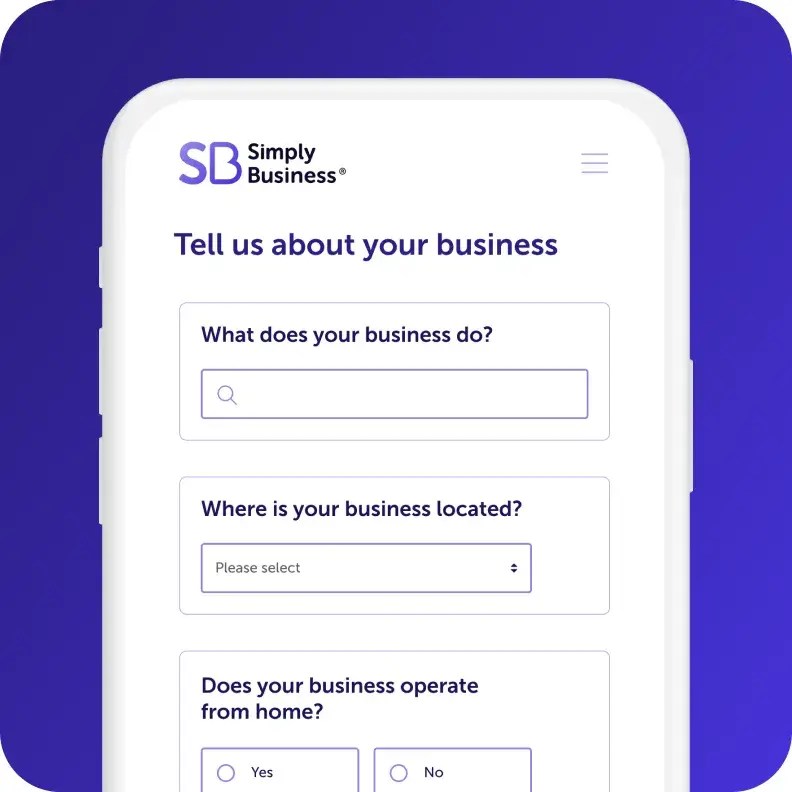
Answer a few questions about
your business in one form.

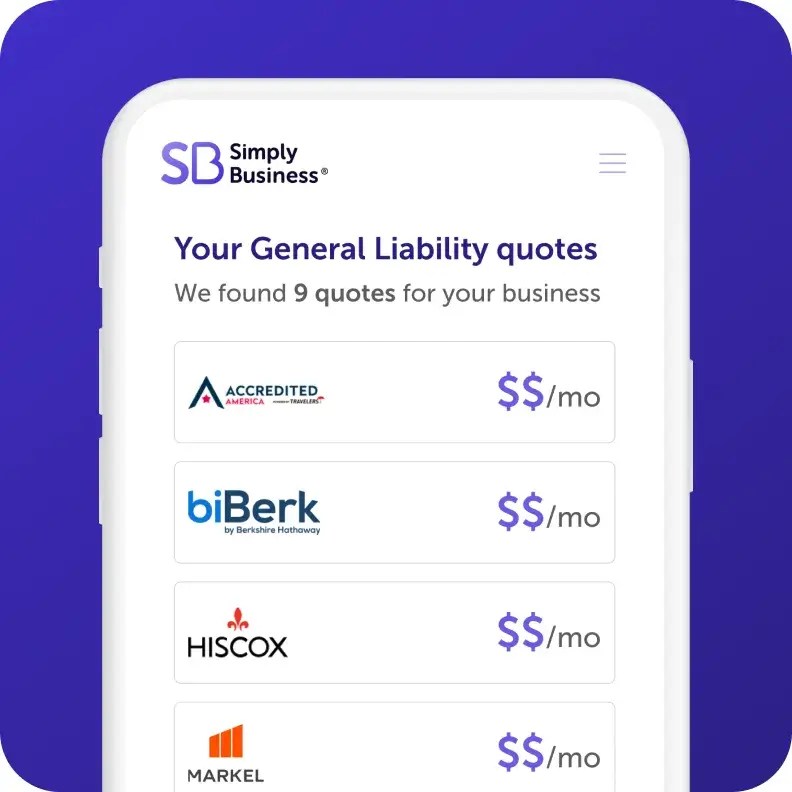
Review quotes
Compare quotes side by side from top-rated insurers and customize your coverage.

Get protected in minutes
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.

Written by
Our +1 million customers are big fans. And you will be too.

I went online, looked around, and found Simply Business. The process was so seamless. I got my certificate within minutes. It was just phenomenal.
Karen
Owner of Tangaza Bath & Body Studio LLC
With Simply Business I know I can look at different carriers, but also see all my stuff in the same place… a lot of [insurance] providers don’t offer a variety of coverage, all in one place.
Jef
Owner of Bunker83 LLC
It wasn’t overwhelming to figure out what was covered and what wasn’t covered. And the cost was competitive.

Kim
Owner of Room to Breathe Professional Organizing
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.
Page last updated: