Commercial contractor insurance
One application, multiple quotes.
All in one place.
Essential Protection
From
$68.75
/month*
Can help cover claims of accidental damage to a customer’s property, such as dents to walls or floors.
What’s included:
General Liability
Coverage limits: $1M to $2M†

Get multiple quotes in less than 10 mins
Essential Protection
From
$68.75
/month*
Can help cover claims of accidental damage to a customer’s property, such as dents to walls or floors.
What’s included:
General Liability
Coverage limits: $1M to $2M†
Get multiple quotes in less than 10 mins
Would you rather pick and choose your coverage? Explore all options
Over 1 million customers worldwide.

Buy instantly online.

Written by
Why Do I Need Commercial Contractor Insurance?
As a commercial contractor, you know how much planning and work goes into the execution of a single project. From securing permits to scoping the project, many variables make up a successful contracting project. There’s a chance that something can go awry with so many variables — even if you are an experienced contractor. Do you have the proper protection if something goes wrong?
Below are some of the most common types of insurance policies that commercial contractors carry to stay protected.
What Type of Commercial Contractor Insurance Do I Need?

General Liability
A foundational insurance coverage to help handle costs from third-party accidents, property damage, and bodily injury.
From
$68.75
/month*

Workers’ Comp
Coverage to help take care of employees who get sick or injured on the job. Most states require this coverage for small businesses with full- or part-time employees. It also can benefit business owners who don’t have employees.
From
$38.91
/month*

Contractor’s Equipment and Small Tools Insurance
Also known as inland marine insurance, this coverage can financially protect equipment and inventory that’s in transport or stored offsite.
From
$20.83
/month‡
Business insurance —
a quick explainer
Learn more about policies for small businesses, what they cover, why you might need them, and how we can help – all in just 60 seconds.
Business insurance is often made up of different types of policies to cover different things, similar to how your health insurance can be made up of medical dental and vision coverage. Here are some of the ones small business owners need. General liability is kind of the Swiss army knife of insurance. It can do a lot, like help handle costs from third party accidents, property damage, bodily injury, and more. Nobody’s perfect, right? That’s what professional liability is for. It could come in handy in the event of honest mistakes or claims of negligence. Workers’ comp can protect your business and help take care of employees who get sick or injured on the job. Small businesses are big targets for cyber criminals. Cyber Insurance can help cover costs associated with stolen customer data, cyber attacks, breaches, and fraud. BOP or a business owners policy combines different types of coverages like general liability and commercial property insurance. Putting them together for you is where we come in. You tell us a bit about your business online or on the phone, and we customize the coverage options for what you do and what you need. It’s your business, it should be your insurance as well. That’s why we’re here.
What Type of Insurance Should I Consider for My Commercial Contracting Business?
Your business is unique. Therefore, you need insurance that’s specific to your business. Insurance for commercial contractors can include several policies, which can help protect you from the risks and liabilities you may face in your industry.
When building your commercial contractors insurance bundle, we may suggest these two core plans as part of your comprehensive policy:
General Liability Insurance
As a commercial contractor, you likely rent an office space where you work and meet with clients to discuss projects. If you have a designated space like this, you’ll likely need commercial general liability (GL) insurance.
This policy type can cover the cost of incidents such as third-party accidents, property damage, and bodily injury to a third party.
GL insurance is highly recommended as a foundational policy because it can protect you and your business from significant costs and claims. For example, the average customer injury or damage claim (something that GL covers) is $30,000.
Without general liability insurance, you run the risk of potentially paying for those costs out of your bank account.
So how does general liability insurance function in a real situation?
Let’s say that while working on a job site, you leave a few tools out unattended. As a result, someone accidentally trips over the tools, and they break their wrist.
In this case, your general liability insurance could typically cover the cost of the individual’s medical bills and any legal costs if they were to sue you.
To summarize, here’s what general liability insurance usually can cover:
- Bodily injury to another person
- Third-party property damage
- Personal and advertising injury
- Medical expenses
- And more
Here’s what general liability insurance usually doesn’t cover:
- Damage to your own property
- Professional services
- Workers compensation or injury to your employees
- Damage to your work
- Motor vehicles while in business use
- Expected or intentional injury or damage
- And more
Workers Compensation Insurance
If you have any full-time, part-time, or even temporary employees on your team, you may be required to carry workers compensation insurance. This type of coverage may be able to cover the costs associated with an employee injury or illness they sustain while working for you.
Most states require business owners with employees to carry workers compensation insurance; check to see what the requirements are in your state.
Not only is workers compensation insurance important for protecting your employees, but it’s also a critical element to running a successful business. With the estimated average work injury cost being $41,000, carrying workers compensation insurance is a responsible business decision.
Even if you have only a few employees on your team, it’s a smart idea to include workers compensation insurance as part of your overall commercial contractors insurance coverage.
To summarize, workers compensation insurance for commercial contractors can cover:
- Medical payments
- Lost wages
- Rehabilitation expenses
- Death benefits
Why Should I Get Insurance for My Commercial Contracting Business?
Maybe you aren’t sure if this is the right time to get business insurance. Perhaps you’re just getting started in the industry and want to keep your expenses to a minimum.
We get it. But here’s the truth: business insurance can be critical to reducing the liabilities and risks you may face, even if you have only a few clients. What happens if something goes wrong, despite your doing everything right?
Although we can mitigate the risks we face, that doesn’t mean they can’t happen. Here are some of the most common incidents that can happen to a small business, including their average costs:
- Reputational Harm — $50,000
- Client Injury or Damage — $30,000
- Client Slip and Fall — $20,000
Those costs can be devastating to a small business. If you have the proper protection of commercial contractors insurance, your policy could cover all or some of the costs of any claims or lawsuits you may experience.
Did you know that up to 43% of small business owners polled reported being threatened with or involved in a civil lawsuit? That’s right — a client could potentially sue you even if you held up your end of the project.
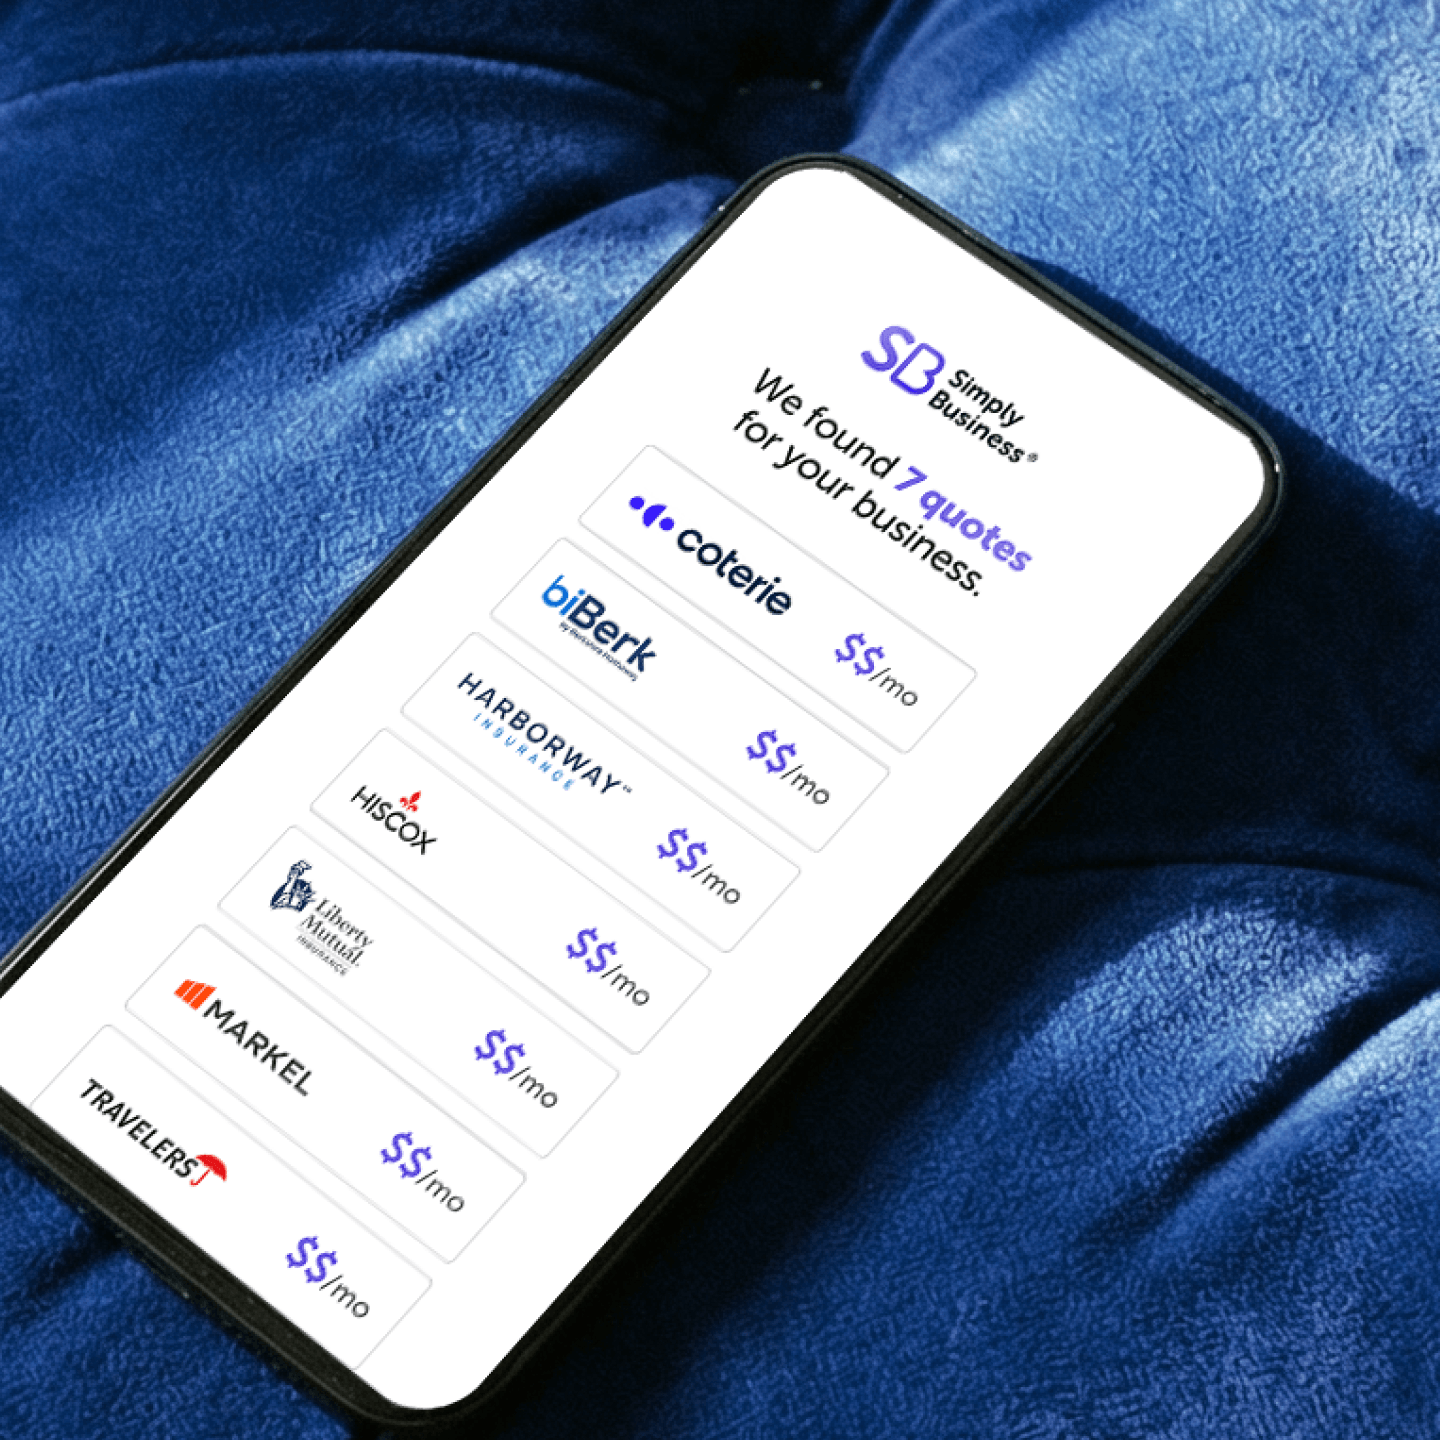
Protect the business you worked so hard to build. At Simply Business, it’s easy to secure an insurance plan that’s unique to your business — at the right price. Just answer a few questions about your business, and you can start comparing quotes from top insurers across the country.
Plus, we can provide you with a certificate of insurance (COI), so you can start providing proof of coverage to clients, vendors, and potential employees.

What Does Commercial Contractor Insurance Cost
Try our insurance calculator.
Get a quick estimate in just 3 steps.

Answers to More Commercial Contractor Insurance Coverage Questions
Because commercial contractors insurance can be a bundle of several policies, you may be required to carry some coverage, but not others. State requirements vary.
For instance, perhaps your state requires you to carry workers compensation if you have employees, but not general liability insurance.
In general, commercial contractors insurance premiums are income tax-deductible by the IRS. We recommend speaking to an accountant if you have questions about your business’s deductible expenses, though.
The amount of coverage your business may need will depend on a few factors:
- The size of your business
- Your business’s location
- Your annual revenue and payroll
- And more
If you aren’t sure what type of insurance coverage you need, our quote form is built to recommend insurance plans for you, based on your needs and the responses you provide.
If you have questions, our licensed insurance agents are available to assist you.
If you’re ready to check out your free quotes, it’s a good idea to have the following information available to make the process as quick as possible:
- Annual revenue estimates
- Payroll estimates
- Information on any previous claims
It may, as your state may have different insurance requirements for commercial contractors than another state (especially when it comes to workers compensation policies).
That’s why our quote process is so important when shopping for an insurance plan. Our questions can narrow down policies for you, based on your needs, as well as any requirements your state may have concerning insurance protection.
Commercial contractors insurance depends on the policies you need to meet your business’s needs. For example, if you opt for both core policies — general liability and workers compensation — your insurance plan can cover:
- Bodily injury
- Accidents and damages
- Employee injuries
- Negligence or alleged negligence
- And more
The cost of commercial contractors insurance varies depending on your business and its unique needs. For the most part, you can expect your insurance premiums to be determined by:
- The number of employees and subcontractors who work for you
- Your business location
- The type of services you provide
- And more
Ready to see how much your commercial contractors insurance may cost? Just click here and get free quotes from top insurers in the country.

Why Small Businesses Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

Start your quote
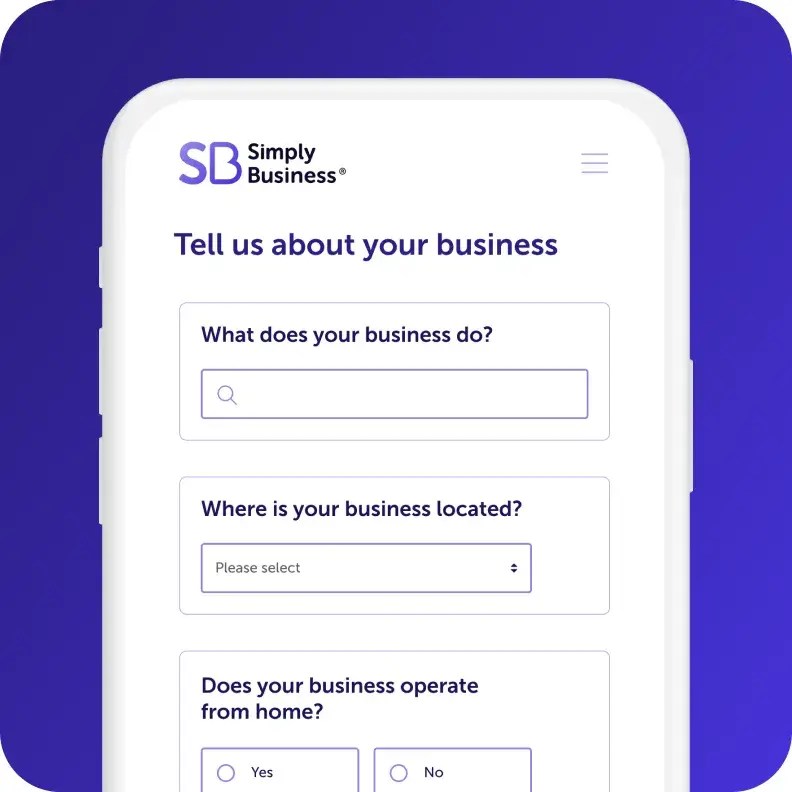
Answer a few questions about
your business in one form.

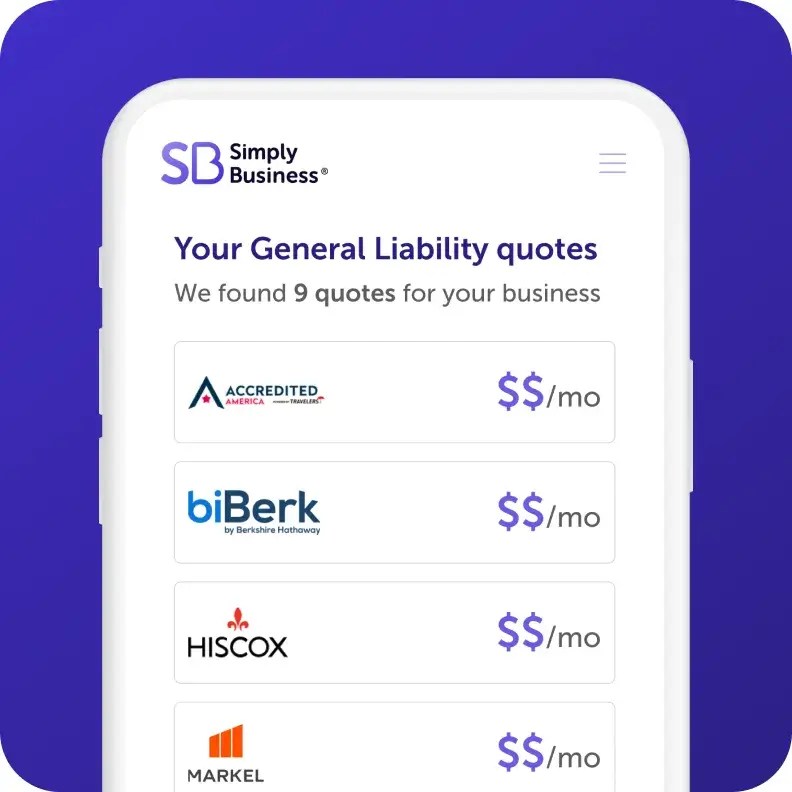
Review quotes
Compare quotes side by side from top-rated insurers and customize your coverage.

Get protected in minutes
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.

Written by
Our +1 million customers are big fans. And you will be too.

I went online, looked around, and found Simply Business. The process was so seamless. I got my certificate within minutes. It was just phenomenal.
Karen
Owner of Tangaza Bath & Body Studio LLC
With Simply Business I know I can look at different carriers, but also see all my stuff in the same place… a lot of [insurance] providers don’t offer a variety of coverage, all in one place.
Jef
Owner of Bunker83 LLC
It wasn’t overwhelming to figure out what was covered and what wasn’t covered. And the cost was competitive.

Kim
Owner of Room to Breathe Professional Organizing
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.
† Limits may vary by state and nature of your business.
‡ Displayed price is based on the lowest available coverage limit for Equipment and Small Tools policies.
Page last updated: