Small Business Insurance in Mississippi

Get a price estimate in just three steps
Rates as low as $20.75/month*
Get a price estimate in just three steps
Rates as low as $20.75/month*

Over 1 million customers worldwide.

Buy instantly online.

Written by
Small Business Insurance in Mississippi
Mississippi’s small business economy runs on construction crews, Gulf Coast restaurants and hotels, farms across the Delta, and professional services firms in Jackson and Hattiesburg. However, each faces a different mix of risks. The right combination of Mississippi commercial insurance policies can help absorb the cost of an injury, accident, or client claim before it has to come out of your pocket.
Mississippi business insurance requirements depend, among other factors, on how many people you employ, the work your business does, the vehicles it operates, and what your clients and landlords put in writing. For example, a licensed contractor in Gulfport has different needs and requirements than a bookkeeper in Hattiesburg, and those obligations can change as a business grows.
Here’s what small business insurance in Mississippi covers, what it typically costs, and which policies fit the industries that drive the state’s economy.
Is Business Insurance Required in Mississippi
General liability (GL) and professional liability, also known as errors & omissions (E&O) insurance, aren’t required by state law for most businesses. However, clients may ask for proof of general liability coverage before signing a contract, and many commercial landlords include it in leases. Some licensed trades may have to carry it to hold a state license.
Mississippi typically requires workers’ compensation insurance when a business regularly employs at least 5 employees, although there are some exceptions depending on the industry. And state law mandates that all drivers have and carry in their vehicles proof of liability insurance to operate, which includes those your business owns and operates. What specifically applies to a small business depends on your workforce and the vehicles you operate.
What Types of Small Business Insurance are Required in Mississippi?
The coverage a Mississippi business must carry often depends on its payroll, industry, and other key factors. Here’s how the most common policies break down.
Workers’ comp insurance can help cover the medical treatment, rehabilitation, and a portion of lost wages when an employee gets hurt or becomes ill from a covered work-related incident.
Mississippi requires coverage from employers with five or more regular-employed workers. Businesses below that count aren’t required to carry it, though they can choose to provide coverage voluntarily. Domestic and farm workers are outside the requirement, as are employees of some nonprofit organizations, unless an employer chooses to cover them. Independent contractors are usually excluded, but in some cases, employees of subcontractors may have certain protections and may be entitled to coverage under a contractor’s workers’ comp policy.
Mississippi employers can meet workers’ comp requirements by buying a policy from an insurance company or getting approval to self-insure from the Workers’ Compensation Commission.
General liability insurance typically covers third-party claims against your business for claims such as bodily injury, property damage, and personal and advertising injury. Mississippi doesn’t require GL for most businesses. But it’s a policy that clients and landlords may want proof of coverage on before doing business or signing a lease.
Licensed contractors are an exception. A contractor applying for or renewing a commercial Certificate of Responsibility with the Mississippi State Board of Contractors must show at least $300,000 per occurrence and $600,000 aggregate in general liability coverage. Residential applicants may provide proof of coverage, but with no minimum amount set by the Board.
Learn more about getting a contractor’s license in Mississippi.
Professional liability insurance can help pay legal defense costs and settlements when a client claims your work caused a financial loss for them. A missed deadline or calculation error can turn into a claim, and defending yourself can get expensive, so this policy can help cover legal defense and settlement costs.
Mississippi doesn’t require errors & omissions insurance from most businesses, but clients may request it in contracts. Some professional industries such as accounting, real estate, and marketing have professional liability coverage as an added layer of protection as well.
Mississippi requires all drivers to have proof of financial responsibility and include a copy of their proof of coverage in the vehicle they are driving. The minimum coverage limits are $25,000 per person for bodily injury, $50,000 per accident, and $25,000 for property damage. While the most common way to satisfy this requirement is through a compliant auto policy, the state allows residents to post a bond in those amounts or have cash or a security deposit equal to the minimum requirements. Business-owned vehicles generally must meet the same coverage requirements.
Personal auto policies typically only cover personal driving and generally exclude coverage for vehicles used for business purposes such as delivery and hauling. So a van making floral deliveries or a truck moving equipment between jobsites typically falls out of the scope of personal coverage, and is where commercial auto insurance comes in.
As of the date when this article is published, Simply Business doesn’t offer commercial auto insurance, but our licensed insurance agents can help you find providers that do.
Get free Mississippi business insurance quotes in 10 minutes or less.
Simply Business provides customized coverage options from top-rated small business insurers — all in just 10 minutes. We do all the leg work so you can sit back, compare quotes, and save.
How Much Does Business Insurance Cost in Mississippi?
How much you pay for Mississippi business insurance often comes down to the type of work your business does, how many people you have on payroll, and where you operate, among several other factors.
Here are median monthly cost ranges for common policies based on purchases by Simply Business customers in Mississippi:
Median Monthly Costs1
| General liability | $41 |
| Professional liability | $41 |
| Workers’ compensation | $100 |
| Business owner’s policy | $47 |
1Data from Simply Business customers located in Mississippi, who purchased at least one or a combination of BOP, general liability, professional liability, and workers’ compensation policies from July 1, 2025 to December 31, 2025. The median costs shown are for illustrative purposes only; actual premiums vary by state, coverage limits, and individual business risk, among other factors.
Some of the factors that shape your premium include, but are not limited to:
- Payroll: Workers’ comp rates follow total wages and headcount, so hiring more employees may increase premiums.
- Industry risk: A tax preparer and construction worker have different risks to third parties and odds of a claim, so coverage is priced differently.
- Location: A business operating along the Gulf Coast may deal with storm risks that an inland business in Oxford doesn’t.
- Claims history: Prior claims on your record can potentially raise what you pay at renewal.
State-Specific Risks for Businesses in Mississippi
Businesses operating in Mississippi face a variety of risks, from weather to its agricultural economy.

Gulf Coast Hurricane and Wind Damage
Businesses in Biloxi and Gulfport sit directly in the path of hurricanes, and wind and storm surges can close a business for weeks. Commercial property coverage often provides protection for wind damage, though coastal properties often carry a separate deductible for named storms.
Coastal businesses that can’t qualify for traditional windstorm coverage on the private market can consider the Mississippi Windstorm Underwriting Association. It can help cover wind and hail damage.

Flooding
Flood damage often falls outside standard coverage in commercial property and business owner’s policies. Heavy rain and river flooding along the Mississippi and Yazoo corridors can reach businesses far from the coast. When flood damage is not covered by these policies, business owners may want to purchase a policy through private insurers or the National Flood Insurance Program.
Tornadoes
Mississippi sits in the “Dixie Alley” tornado corridor, where tornadoes are most likely to arrive in the late fall. Commercial property coverage generally includes wind damage from tornadoes, and business interruption coverage available in a BOP can help replace lost income while you’re closed for repairs.

Agricultural Exposure
This region is known for its cotton, soybean, poultry, and catfish operations. And these industries carry extra risk that may not be covered by standard commercial policies. Crop loss, livestock, and specialized equipment generally are not typically included in a standard GL or property policy, so farm operations often need dedicated agricultural coverage to help fill the gap.
Who Needs Mississippi Small Business Insurance?
- Electricians
- General contractors
- Handypersons
- Professional services
- Remodelers
- Restaurant business owners
- Retail store owners
Best Mississippi Business Insurance for Your Industry
Insurance needs shift by industry; here is some of the coverage the state’s biggest businesses tend to have.
A commercial job of $50,000 or more requires a commercial certificate from the Mississippi State Board of Contractors. Contractors performing residential work over $50,000 for new construction or $10,000 for remodeling or roofing also need certificates. All applicants for a contractor’s license in Mississippi must meet general liability coverage at the Board’s minimum limits. Contractors with five or more employees also must have proof of workers’ comp.
Many contractors and subcontractors also add tools and equipment coverage, often known as an inland marine policy, for gear that moves between jobsites.
The Gulf Coast is Mississippi’s hospitality and gaming center, and hotel, casino, and bar owners there may consider a business owner’s policy (BOP). A BOP combines general liability and commercial property in one coverage, and is an important coverage for owners on the coast because a storm can close a property for a full season. Since a BOP typically won’t cover damage from flooding, a separate flood policy can help mitigate the costs of damages from Gulf Coast storm risks.
For businesses that manufacture, distribute, sell, serve, or furnish alcohol, liquor liability is typically excluded from a standard BOP and must be purchased as a separate policy or specialized endorsement.
Farm labor is exempt from Mississippi’s workers’ compensation requirements, though coverage can be provided voluntarily. Crop and livestock risks are often not covered by standard commercial policies, so cotton, poultry, or catfish operations may choose to purchase additional specialized agricultural liability and equipment coverage.
How to get a Certificate of Insurance in Mississippi
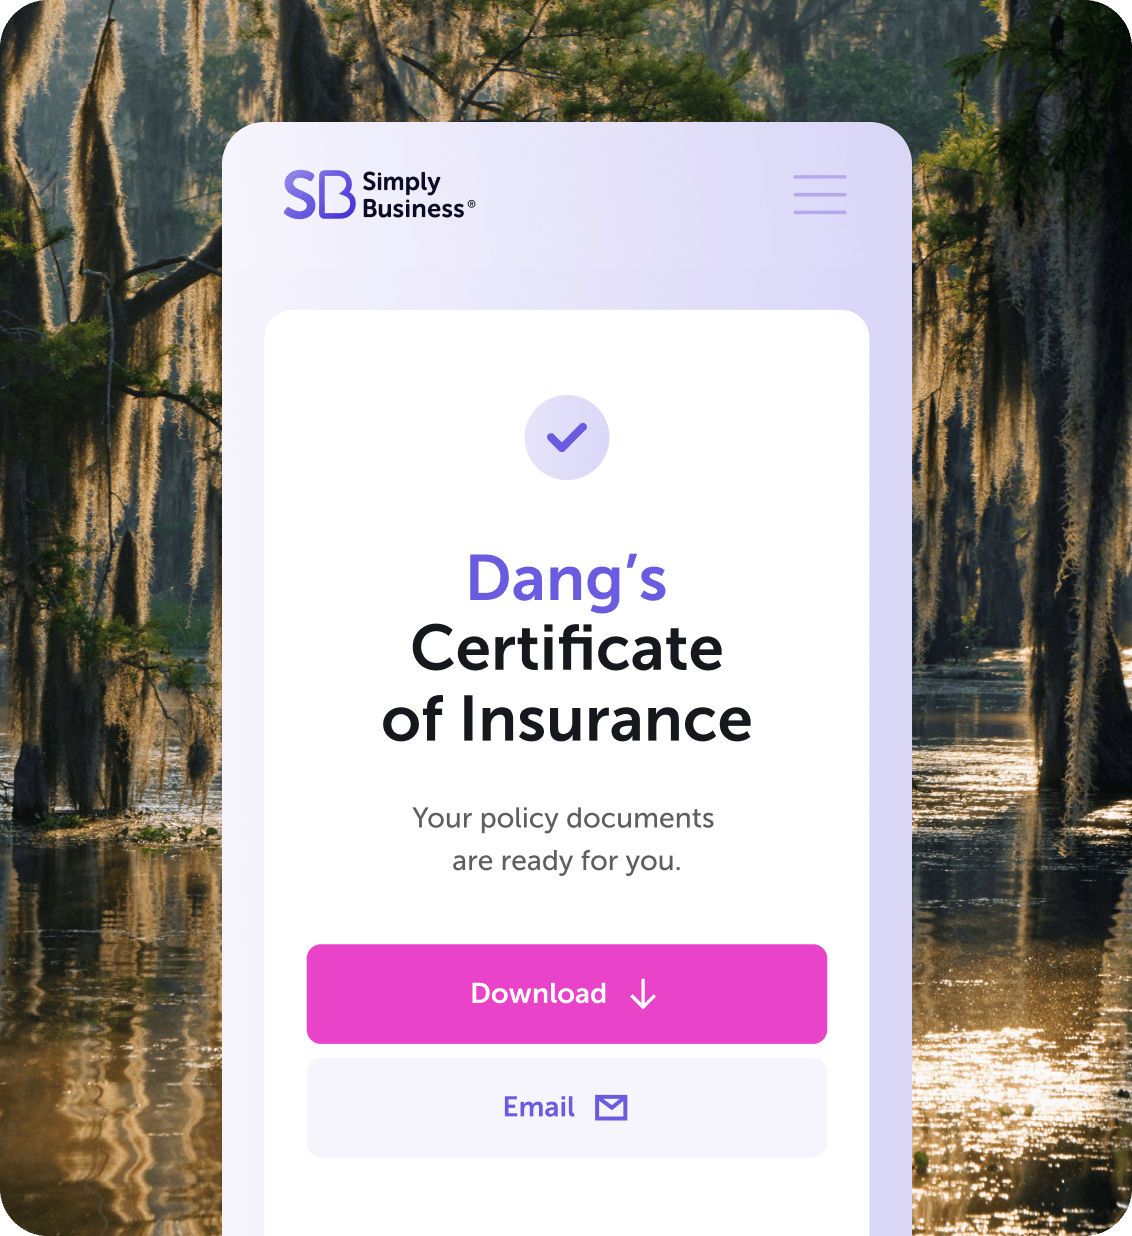
A certificate of insurance (COI) is a document showing your business has active coverage, listing your policy type, limits, and insurer in Mississippi. Clients, commercial landlords, and licensing boards may require one before you can sign a lease or start a project. Contractors in Mississippi provide a COI to the State Board of Contractors when applying for or renewing a license.
Once your Simply Business policy is active, you can download your certificate of insurance from your account. If a client or landlord needs to be named as an additional insured, you may add them to the certificate.
FAQs About Mississippi Business Insurance
Mississippi requires the companies with five or more regularly employed workers carry workers’ comp coverage. Coverage is optional for employers with fewer than five employees.
Commercial contractors in Mississippi do, depending on the size of their projects. The State Board of Contractors sets minimum limits that contractors must hold for a commercial Certificate of Responsibility. Residential applications must show proof of GL coverage, but there isn’t a set minimum amount.
Wind damage is generally covered, often with a separate deductible for named storms. Flood and storm surge damage generally isn’t covered, and business owners can purchase additional coverage through the National Flood Insurance Program or a private insurer.
The Mississippi Insurance Department covers most business insurance; workers’ comp is handled by the Mississippi Workers’ Compensation Commission.
Our Mississippi customers are big fans. And you will be too.
Good customer service and very good rates
Tim R.
Electrician
Easy questionnaire, easy to see and choose the right coverage and right company to protect my business.
John D.
Handyperson
It was quick and easy and all done online. Plus the price was reasonable.
Carol S.
Retail store owner
Additional Information and State Resources for Mississippi Small Business Owners

Written by

Why Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

Start your quote
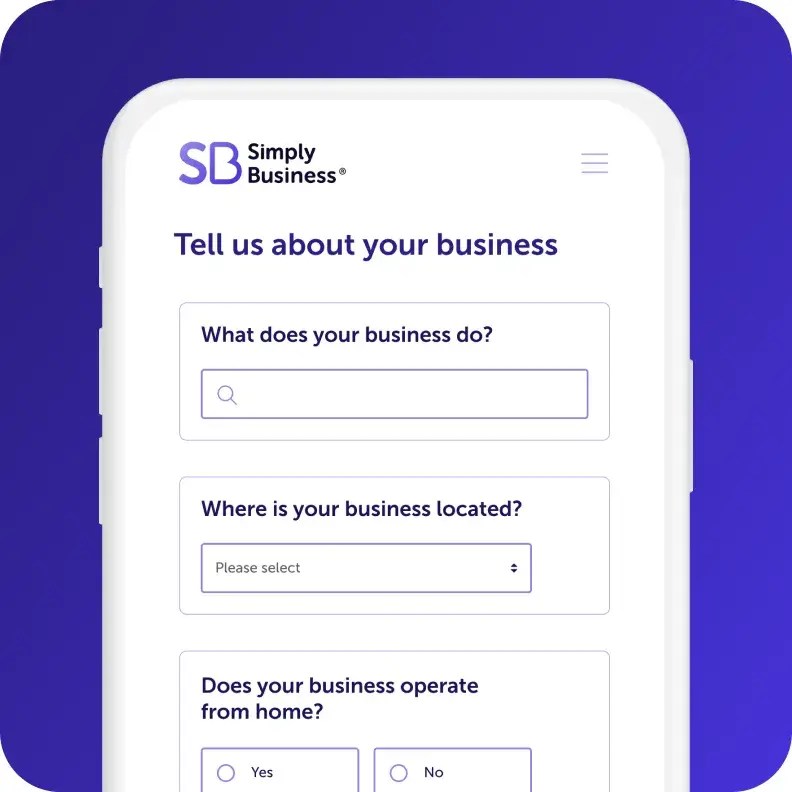
Answer a few questions about
your business in one form.

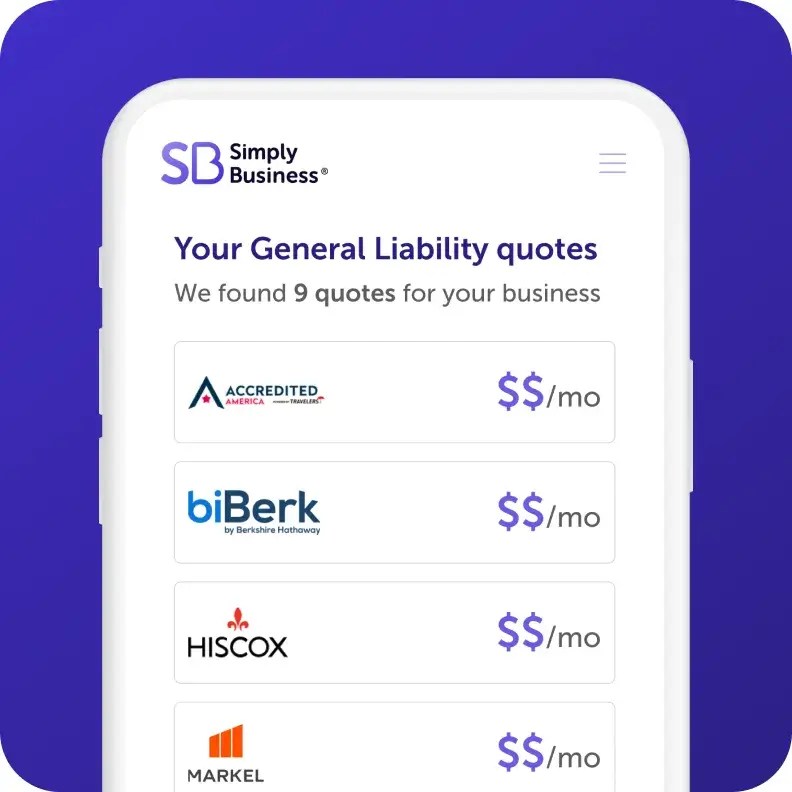
Review quotes
Compare quotes side by side from top-rated insurers and customize your coverage.

Get protected in minutes
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.