
Building, Construction
& Tradesperson Insurance
See what coverage construction businesses typically need, and compare insurance quotes from top-rated carriers.
Trusted by +1M small business owners worldwide
No junk mail. No spam calls. Free quotes.
Find your trade
Select your trade to see coverage options tailored to your day-to-day work.
General Contracting

General Contractor From $68.75/month*
BuilderFrom $68.75/month*

Home Improvement ContractorFrom $56.18/month*


Specialist Trades


Floor ContractorFrom $36/month*

Door & Window InstallationFrom $46/month*

Concrete ContractorsFrom $45/month*
Sheet Metal WorkersFrom $20.75/month*

Steel ErectorsFrom $20.75/month*
Site Prep & Civil


Water Well DrillingFrom $20.75/month*
Other

Home InspectorFrom $26/month*

Satellite TV InstallerFrom $32/month*

Written by
What Insurance Do Construction Businesses Need?
Most construction businesses start with general liability insurance — it’s the coverage clients, general contractors, and licensing boards ask for most. Many states require proof of insurance to get or renew a contractor’s license. Check your state licensing requirements, or see our guide to getting a contractor’s license in New York for an example of how the rules work.
Some states also require a contractor license bond before you can work. A bond isn’t insurance — it helps protect your client or the state if you don’t fulfill your obligations, while insurance can help protect your business. Many contractors carry both.

General Liability
General liability insurance (GL) can help cover third-party claims of bodily injury or property damage — like if a client trips over your extension cord, or a dropped tool cracks a granite countertop. It’s also the coverage you’ll usually need to have before you can sign contracts, pull permits, and start work.
Best for every construction business with:
- The need to sign contracts and pull permits
- Third-party injury and property damage claims

Workers’ Comp
If an employee is injured on the job, workers’ compensation insurance can help cover their medical bills and a portion of their lost wages. Most states require it by law once you hire your first employee — and construction requirements are often stricter than other industries.
Best for contractors with:
- Clients or contracts that require coverage
- Employee medical bills and lost wages after an injury
- A need to meet state requirements once you’re hired

Tools & Equipment Insurance
Tools and equipment coverage — also known as inland marine insurance — can help repair or replace your gear when it’s damaged or stolen, whether it’s on the job site, in transit, or in your truck overnight.
Best for tradespeople who might have:
- Equipment damaged in transit or on-site
- Tools stolen from your truck or the job site

Business Owner’s Policy (BOP)
A business owner’s policy bundles general liability with commercial property coverage, often at a lower cost than buying each policy separately. That means protection for your shop, office, or stored materials, plus coverage for third-party claims.
Best for businesses with a workshop, office, or stored materials that need:
- Protection for your gear and coverage for third-party claims in one policy
- Bundling liability and property coverage at a lower cost

Professional Liability
Professional liability insurance — also called errors and omissions (E&O) insurance — can help cover claims that your advice, designs, or project management caused a client a financial loss. It can help pay both the damages you may owe and your legal defense costs — even if you overturn the allegations made against you.
Best for engineers, home inspectors, project managers, and design-build contractors with:
- Legal defense costs, even where you prevail on the claims
- Claims over design errors or project management mistakes
How Much Does Construction Insurance Cost?
Here’s a snapshot of what Simply Business customers in construction trades pay for general liability insurance — the foundation policy for most businesses:
| Policy | Median Monthly Cost1 |
|---|---|
| Remodeler | $85 |
| General contractor | $82 |
| Handyperson | $51 |
| Electrician | $36 |
1Data from Simply Business customers in the designated trades who purchased a general liability policy from July 1, 2025 to December 31, 2025. Median costs are shown for illustrative purposes only; actual premiums vary by state, coverage limits, and individual business risk.
There’s no single price for construction insurance — your premium reflects your specific business and the work you do, among several other factors. When insurers calculate your quote, they typically look at:
- Your trade — roofing and steel work carry different risks than handyman services
- The number of employees on your crew and your payroll
- The value of your tools, equipment, and vehicles
- Whether you work on residential projects, commercial projects, or both
- Your annual revenue
- Where you work — requirements and rates vary by state
- The coverage types and limits you choose
The fastest way to learn your price is to compare quotes for your specific business — it takes just a few minutes. You can also explore our contractor insurance options, or see our general liability insurance cost guide for a closer look at what businesses like yours pay.
How to Get Covered with Simply Business

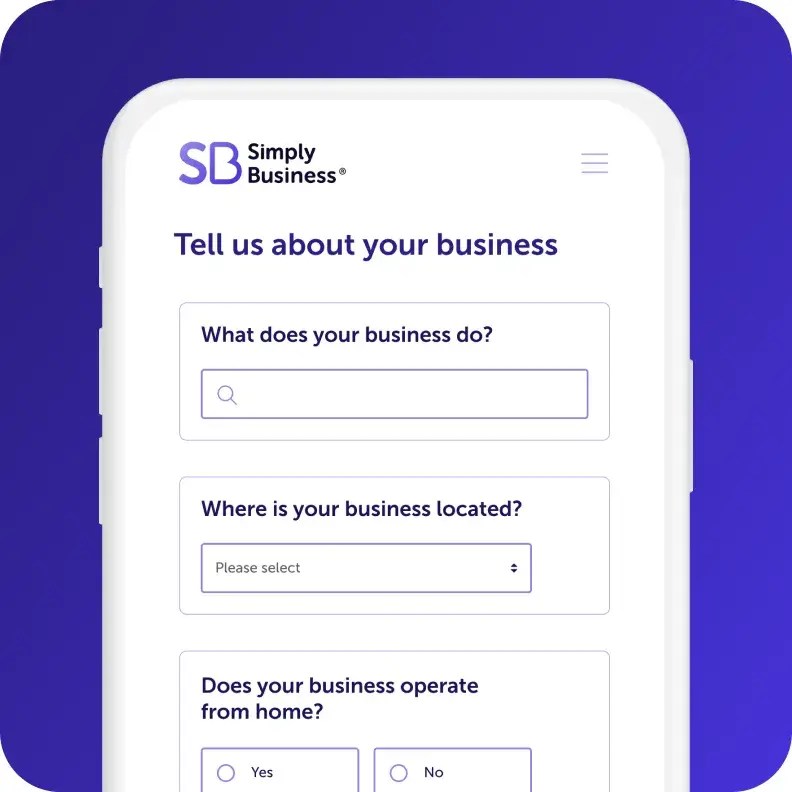
Tell us about your business
Answer a few questions about the work you do.your business in one form.

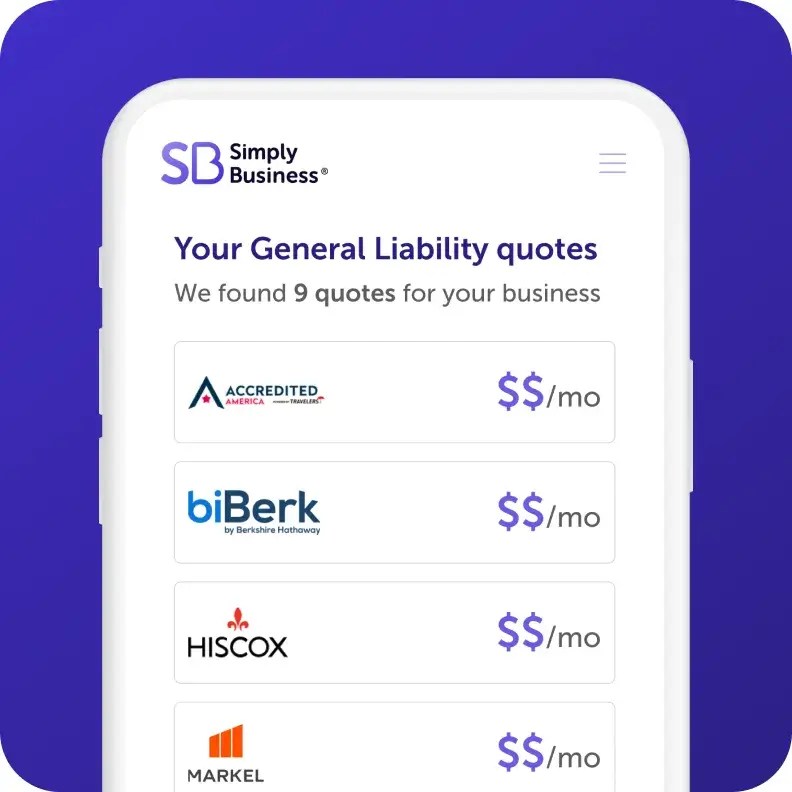
Review quotes
We’ll show you policies from top carriers so you can pick the coverage and price that work for you.

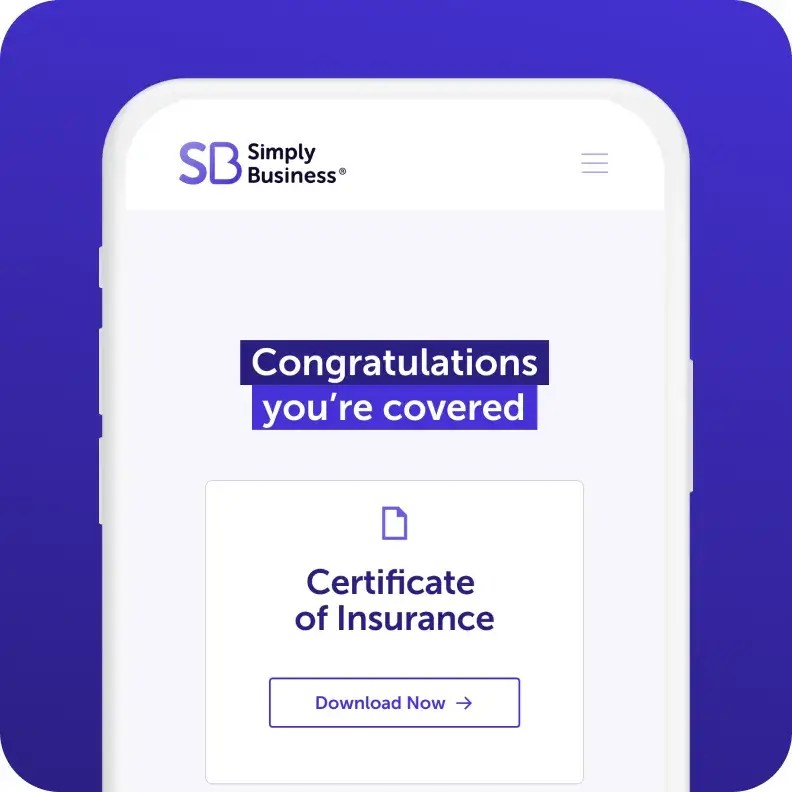
Get protected in minutes
Buy online in under 10 minutes. Download your certificate of insurance right away.
Frequently Asked Questions
Most start with general liability insurance, because it’s what clients, general contractors, and licensing boards request most often. Depending on your work, you may also need workers’ compensation insurance (required by law in most states once you have employees), tools and equipment coverage for your gear, a BOP to protect your shop or office, and professional liability insurance if your work includes designs or professional advice.
It varies based on your trade, crew size, the value of your tools and equipment, where you work, and the coverage limits you choose, among other factors. The best way to find your price is to compare quotes for your specific business — it takes just a few minutes.
Usually, yes. Most general contractors require subcontractors to carry their own general liability insurance before they can step on-site, and relying on someone else’s policy can leave gaps. Having your own coverage also helps you win more bids — many GCs won’t consider uninsured subs.
General liability insurance typically covers third-party claims of bodily injury and property damage. A business owner’s policy bundles that same coverage with commercial property protection for things like your shop, office, tools, and materials — often at a lower combined price. If you have property to protect, a BOP can be the more cost-effective choice.
Yes. When you buy a policy through Simply Business, you can access your certificate of insurance (COI) online right away — and download or share it with clients and general contractors whenever you need it, at no extra cost.
Often, yes. Even when the law doesn’t require it, clients and general contractors usually ask for proof of general liability insurance before work begins, and many states require coverage to get or maintain a contractor’s license. Insurance also helps protect your personal assets, because sole proprietors are often personally responsible for business claims.
Requirements vary. Most states don’t require workers’ compensation insurance for businesses with no employees, but some have stricter rules for construction trades, and many general contractors require it before you can work on their sites. A policy can also help cover your own medical bills and lost income if you’re injured on the job. Learn more about workers’ comp for sole proprietors.
Depending on your projects, you may also want builder’s risk insurance, which typically covers structures under construction and materials on-site; contractors pollution liability, which can help cover cleanup and claims if your work causes pollution; and commercial umbrella insurance, which adds an extra layer of liability coverage on top of your other policies. If you need additional help finding coverage options for your profession, our licensed agents are available to help.
Our +1 million customers are big fans. And you will be too.

First off, for handymen you are the cheapest. And when I have called in and needed assistance, y’all are very friendly.

Casey R.
Handyperson, Tennessee
Very easy to obtain with lots of options to add as far as what your business needs. The pricing was also better than all could offer.
Darrell I.
General contractor, Massachusetts

Written by
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.
† Limits may vary by state and nature of your business.
‡Displayed price is based on the lowest available coverage limit for Equipment and Small Tools policies.