Door and window installation insurance
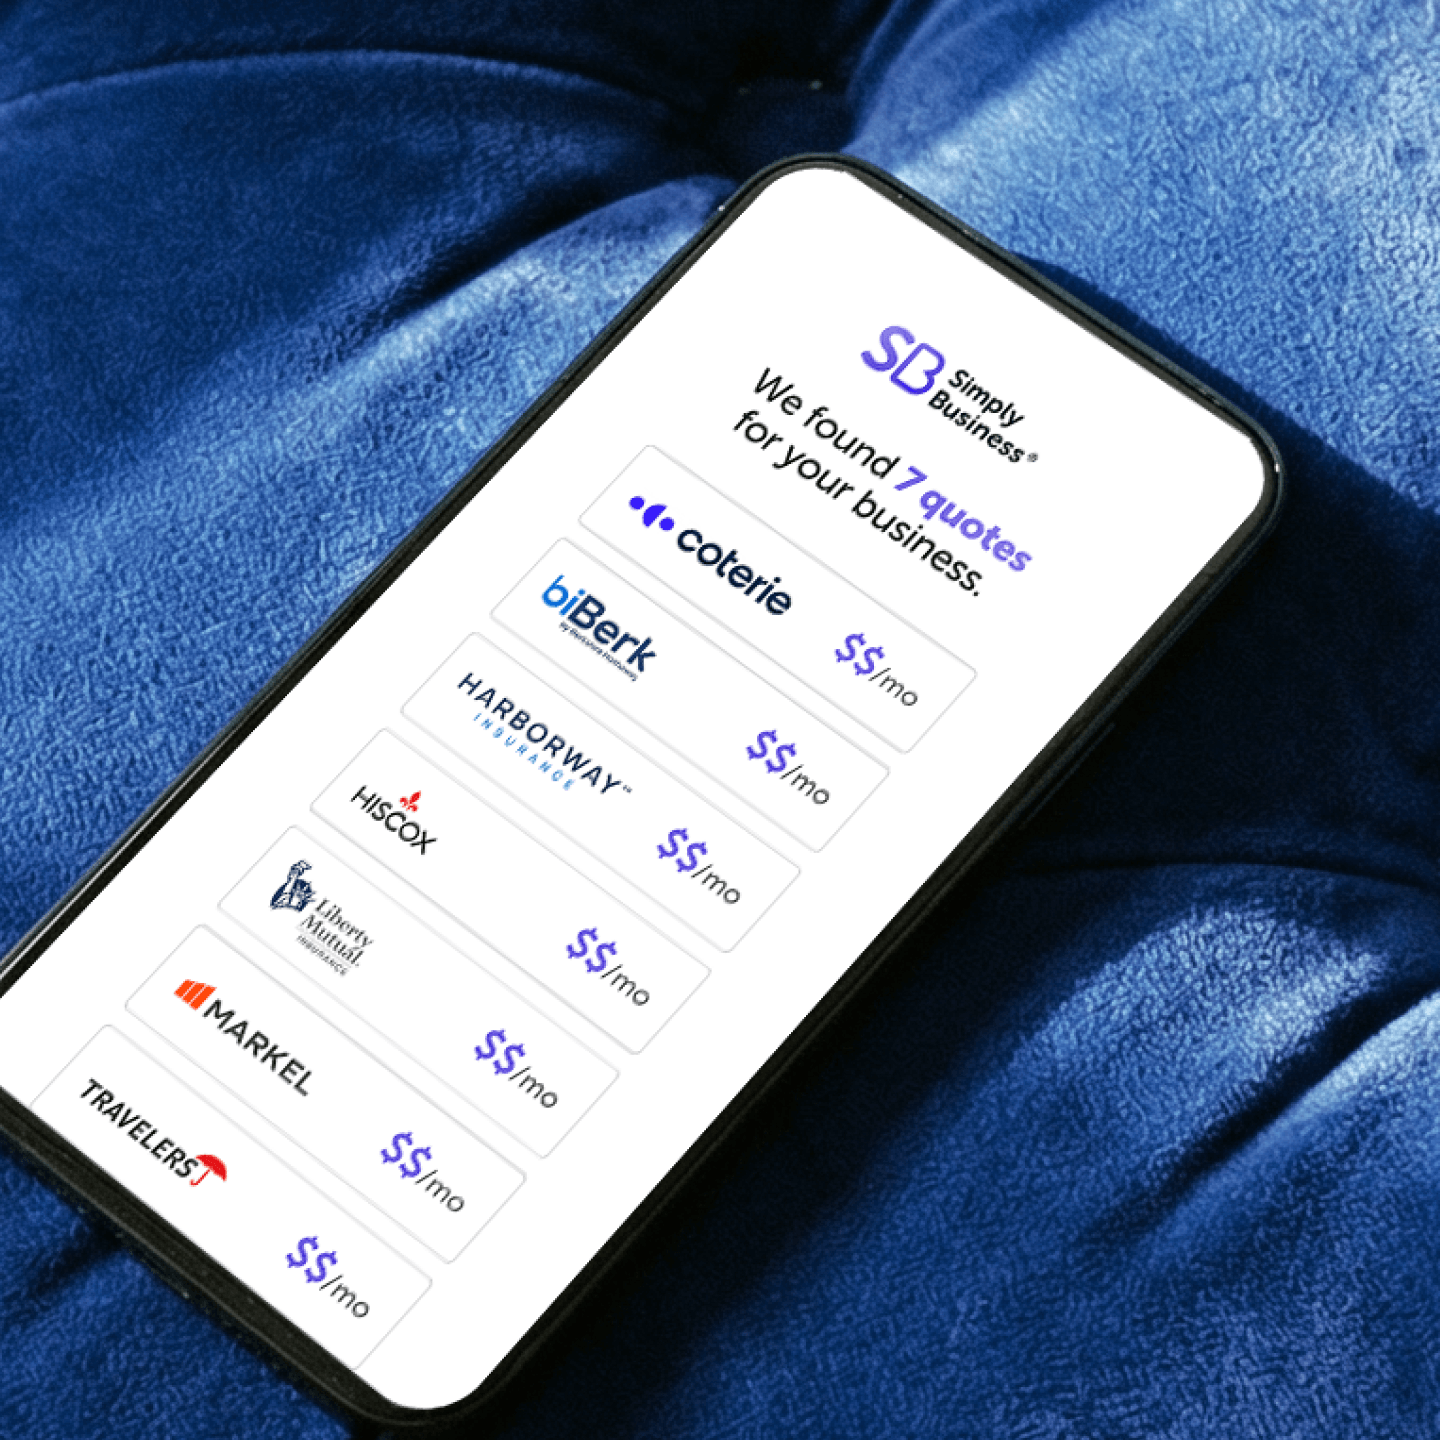
One application, multiple quotes.
All in one place.
Essential Protection
From
$46
/month*
Can help cover claims of accidental damage to a customer’s property, such as dents to walls or floors.
What’s included:
General Liability
Coverage limits: $1M to $2M†

Get multiple quotes in less than 10 mins
Essential Protection
From
$46
/month*
Can help cover claims of accidental damage to a customer’s property, such as dents to walls or floors.
What’s included:
General Liability
Coverage limits: $1M to $2M†
Get multiple quotes in less than 10 mins
Would you rather pick and choose your coverage? Explore all options
Over 1 million customers worldwide.

Buy instantly online.

Written by
Why Do I Need Door and Window Installation Insurance?
By installing doors and windows, you’re responsible for putting on some of the most important finishing touches on a home or business. Just as doors and windows protect homes against the elements, business insurance can help you weather storms.
Below are some of the most common types of insurance policies that door and window installers carry to stay protected.
What Type of Door and Window Installation Insurance Do I Need?

General Liability
A foundational insurance coverage to help handle costs from third-party accidents, property damage, and bodily injury.
From
$46
/month*

Contractor’s Equipment and Small Tools Insurance
This coverage can financially protect equipment and inventory that’s in transport or stored offsite.
From
$20.83
/month‡

Business Owner’s Policy (BOP)
General liability, property insurance, and more all in one convenient package.
From
$33.75
/month*

Workers’ Comp
Coverage to help take care of employees who get sick or injured on the job. Most states require this coverage for small businesses with full- or part-time employees. It also can benefit business owners who don’t have employees.
From
$38.91
/month*
Business insurance —
a quick explainer
Learn more about policies for small businesses, what they cover, why you might need them, and how we can help – all in just 60 seconds.
Business insurance is often made up of different types of policies to cover different things, similar to how your health insurance can be made up of medical dental and vision coverage. Here are some of the ones small business owners need. General liability is kind of the Swiss army knife of insurance. It can do a lot, like help handle costs from third party accidents, property damage, bodily injury, and more. Nobody’s perfect, right? That’s what professional liability is for. It could come in handy in the event of honest mistakes or claims of negligence. Workers’ comp can protect your business and help take care of employees who get sick or injured on the job. Small businesses are big targets for cyber criminals. Cyber Insurance can help cover costs associated with stolen customer data, cyber attacks, breaches, and fraud. BOP or a business owners policy combines different types of coverages like general liability and commercial property insurance. Putting them together for you is where we come in. You tell us a bit about your business online or on the phone, and we customize the coverage options for what you do and what you need. It’s your business, it should be your insurance as well. That’s why we’re here.
What Type of Insurance Do Door and Window Installers Need?
Your customers pay you to be knowledgeable about the ABC’s of windows and doors. You know — aprons, bay windows, and casements. You can stick to your day job, and we’ll keep learning everything there is to know about insurance. That way, we can give you the straight talk about what you may need and may not.
Here are the two types of insurance policies for you to consider.
General Liability Insurance
Are you the contractor that businesses call when they need help with a little bit of everything? If so, then you’re a lot like general liability insurance. This type of policy typically covers costs associated with third-party accidents, damages to property, and bodily injury to a third party. For reference, a “third party” refers to your customers and vendors.
The beauty of GL insurance is that it could potentially save you a ton of money in case of an accident. Did you know that the average customer injury or damage claim — something that general liability insurance covers — is a whopping $30,000?
How could you possibly rack up a bill that high? Just imagine that you’re installing a window on the second floor of a home. You accidentally lose your grip on the window, and it falls on the customer below. They have to be taken to the hospital, and you get sued for damages.
Without insurance, you’d need to pay for those injuries. Nobody wants to cough up $30,000 to pay for a lawsuit, which is where insurance comes in handy. If you had a door and window installation insurance plan, it could help cover that hefty bill.
To recap, here’s what general liability insurance usually can cover:
- Bodily injury to another person
- Third-party property damage
- Personal and advertising injury
- Medical expenses
- And more
Now check out what general liability insurance usually doesn’t cover:
- Damage to your own property
- Professional services
- Workers compensation or injury to your employees
- Damage to your work
- Motor vehicles while in business use
- Expected or intentional injury or damage
- And more
Workers Compensation Insurance
You started with a dream and hard work, and now you have employees. Congratulations! Having a team means you can help more customers, but it also comes with more responsibilities. In most states, you’ll be required to carry workers compensation insurance if you have employees.
You can start by checking your state’s laws here.
A workers comp policy can cover costs associated with an employee’s injury or illness while they’re working for you. The average work injury cost is $41,000, which means that having a policy in place could ensure that your employee gets the help they need, without your having to foot the bills.
In general, workers compensation insurance can cover:
- Medical payments
- Lost wages
- Rehabilitation expenses
- Death benefits
Why Should I Get Door and Window Installation Insurance?
Installing doors and windows is second nature for you. While you always do your best work, there’s no such thing as a business without risk. Rather than worrying about what could happen, you can buy peace of mind with business insurance.
Let’s look at some stats to give you context. Nearly half of small business owners polled reported being threatened with or involved in a civil lawsuit. You can take a gamble, but only if you’re prepared to pay out of pocket if you lose the bet.
Just take a look at the most common incidents that can happen to small business owners, including how much they cost on average:
- Reputational Harm — $50,000
- Client Injury or Damage — $30,000
- Client Slip and Fall — $20,000
Only you know the full extent of the hard work you’ve invested in your business to get to where you are today. That means you can appreciate just how much your business means to you and how tough it would be to see it set back by an accident. Consider getting a business insurance policy today so you can rest easy knowing that you’re covered.
Let’s shake off all that heavy stuff, shall we? Business insurance is also there for you on your best days. When you get covered through Simply Business, you can request a certificate of insurance (COI). Then, you can use that proof of insurance to rent business space or build trust with potential customers and employees.
While having business insurance can have a serious impact on your business, getting covered doesn’t have to be difficult. Here at Simply Business, we make it easy to get insured.

What Does Door and Window Installation Insurance Cost
Try our insurance calculator.
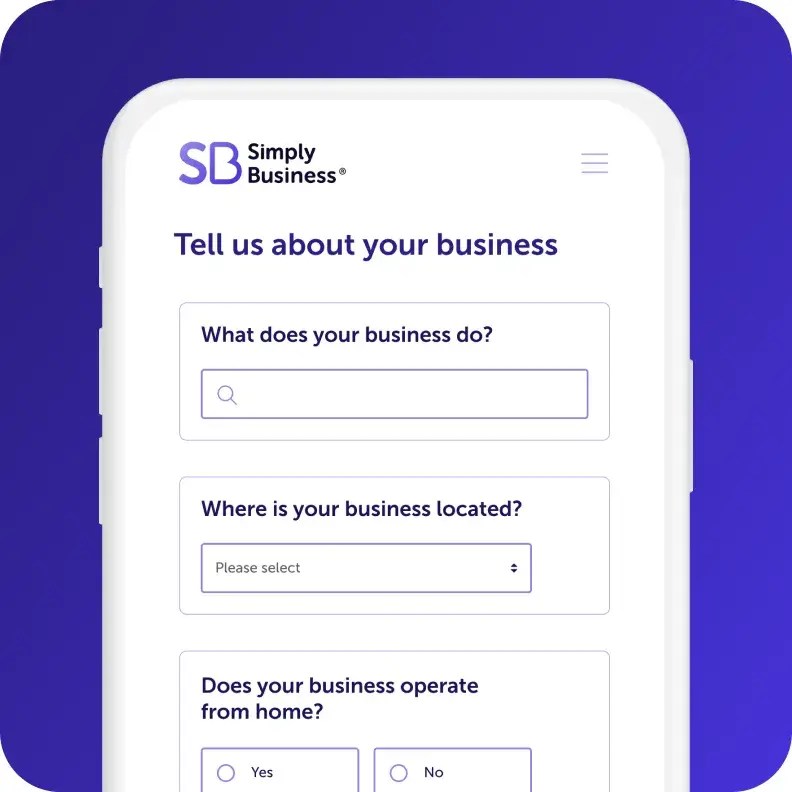
Get a quick estimate in just 3 steps.

Answers to More Door and Window Installation Insurance Coverage Questions
Each state sets laws about business insurance, so your coverage requirements depend on your location. Luckily, our quote process can help you determine your needs.
Here at Simply Business, we suggest considering business coverage, and since workers comp is required in most states if you have employees, we recommend that coverage as well. Some landlords may also require proof of insurance to rent business space.
Typically, you can deduct business insurance premiums from your business’s income tax filings. It’s always a good practice to consult a tax accountant if you have questions, though.
Insurance needs vary, even within the same profession. Your coverage depends on:
- The size of your business
- Your business location
- Your annual revenue and payroll
- And more
If you’re not sure what you need, our quote form recommends insurance plans for you, based on your answers.
If you have more questions, our licensed insurance agents are available and will be happy to assist you!
We’ve designed the insurance quote process to be easy, and it can be faster by having the following information on hand:
- Annual revenue estimates
- Payroll estimates
- Information on any previous claims
Insurance requirements for door and window installers vary by state. While workers comp is usually required if you have employees, you may not need proof of general liability insurance to run your business.
It takes just ten minutes to complete our quote process, to find out what your state requires Your answers automatically narrow down your coverage recommendations.
The type of scenarios you’re covered in depend on the policies you carry. For example, a comprehensive plan with general liability and workers comp can cover:
- Bodily injury
- Accidents and damages
- Employee injuries
- Negligence or alleged negligence
- And more
Since each quote is customized to your needs, generally, your insurance premiums are based on:
- Payroll and revenue estimates
- The location of your business
- The specific services you offer
- And more
Want to see how much your door and window installation insurance may cost? Just click here and get free quotes from some of the top insurers in the country.

Why Small Businesses Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

Start your quote
Answer a few questions about
your business in one form.

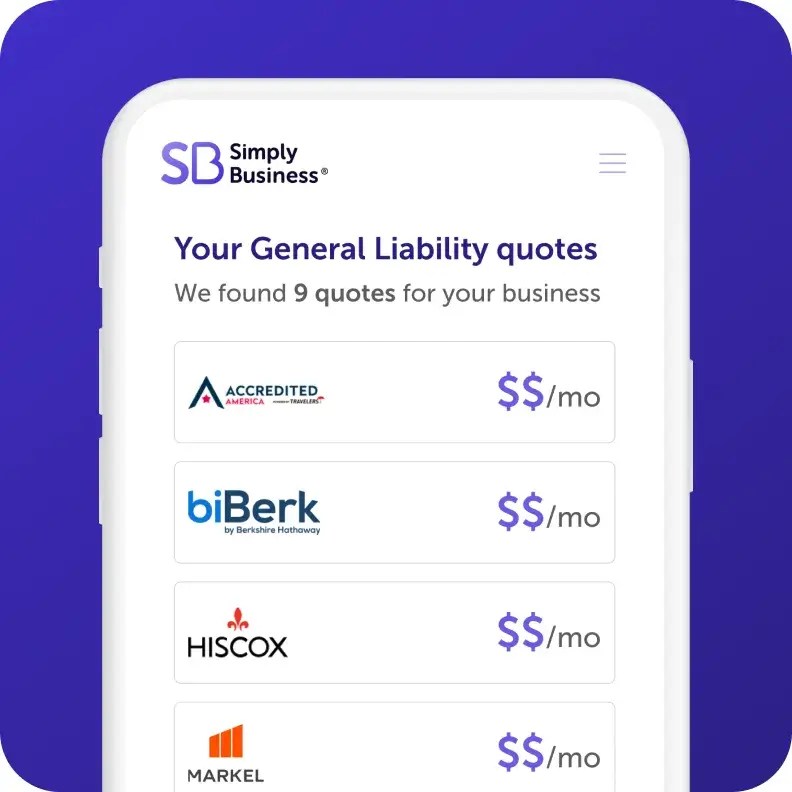
Review quotes
Compare quotes side by side from top-rated insurers and customize your coverage.

Get protected in minutes
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.

Written by
Our +1 million customers are big fans. And you will be too.

I went online, looked around, and found Simply Business. The process was so seamless. I got my certificate within minutes. It was just phenomenal.
Karen
Owner of Tangaza Bath & Body Studio LLC
With Simply Business I know I can look at different carriers, but also see all my stuff in the same place… a lot of [insurance] providers don’t offer a variety of coverage, all in one place.
Jef
Owner of Bunker83 LLC
It wasn’t overwhelming to figure out what was covered and what wasn’t covered. And the cost was competitive.

Kim
Owner of Room to Breathe Professional Organizing
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information
9-minute read
A General Liability Insurance Guide for Small Business
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.
† Limits may vary by state and nature of your business.
‡ Displayed price is based on the lowest available coverage limit for Equipment and Small Tools policies.
Page last updated: