Nutritionist insurance
One application, multiple quotes.
All in one place.
Essential Coverage
From
$25.83
/month*
Can provide coverage if a client claims there was a mistake in the professional services you provided.
What’s included:
Professional Liability / Errors & Omissions
Coverage limits: $100K to $3M†

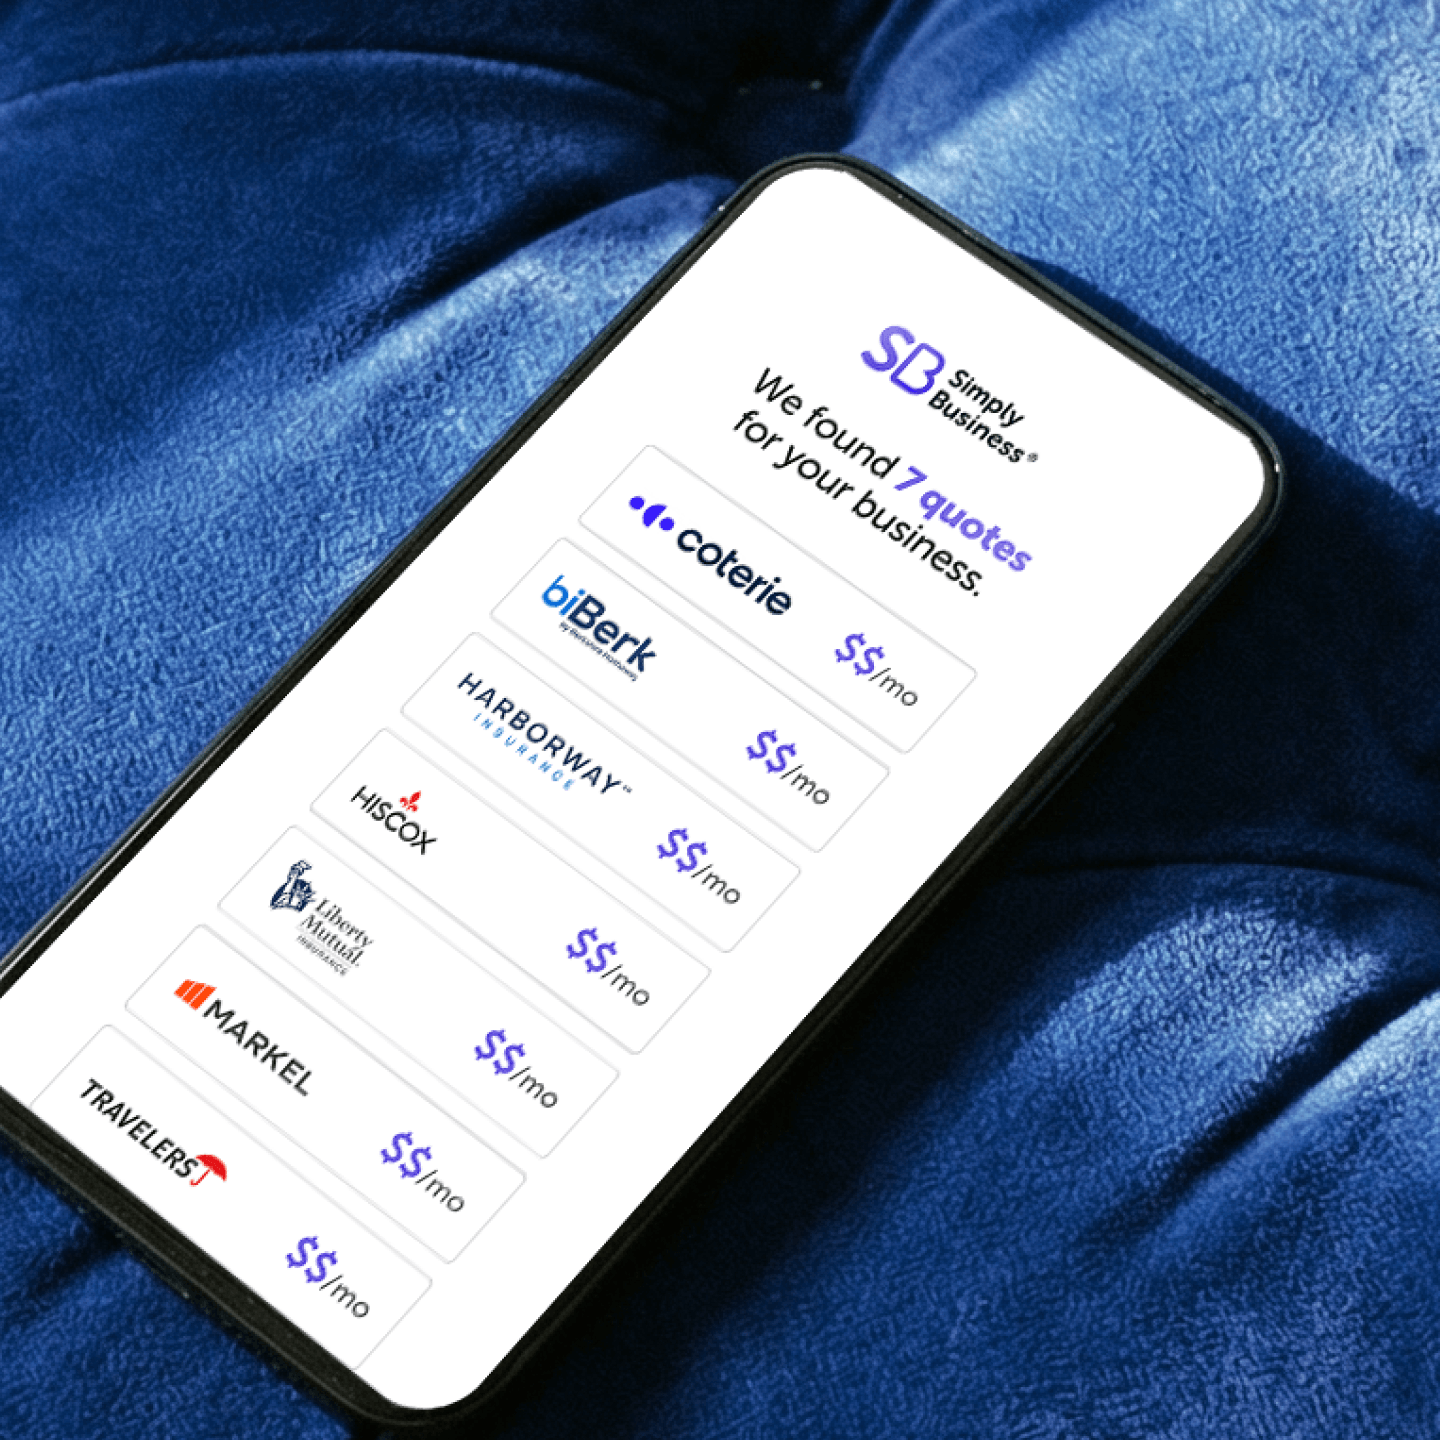
Get multiple quotes in less than 10 mins
Essential Coverage
From
$25.83
/month*
Can provide coverage if a client claims there was a mistake in the professional services you provided.
What’s included:
Professional Liability / Errors & Omissions
Coverage limits: $100K to $3M†
Get multiple quotes in less than 10 mins
Would you rather pick and choose your coverage? Explore all options
Over 1 million customers worldwide.

Buy instantly online.

Written by
Why Do I Need Nutritionist Insurance?
Good nutrition has the power to fight diseases and increase a person’s quality of life. There’s a reason you got into your profession—you believe in the importance of eating well. After all, food can have an incredible impact on a person’s health.
As you work with clients to change their eating habits, remember to protect your practice too. Nutritionists aren’t immune to lawsuits, and in fact, are more at risk than ever before. Just imagine if one of your clients has an allergic reaction, loses too much weight, or even chokes on food you recommend.
Below are some of the most common types of insurance policies that nutritionists carry to stay protected.
What Type of Nutritionist Insurance Do I Need?

From
$25.83
/month*

General Liability
A foundational insurance coverage to help handle costs from third-party accidents, property damage, and bodily injury.
From
$20.75
/month*

Equipment and Business Property
Also known as inland marine insurance, this coverage can financially protect equipment and inventory that’s in transport or stored offsite.
From
$20.83
/month‡

Business Owner’s Policy (BOP)
General liability, property insurance, and more all in one convenient package.
From
$33.75
/month*

Workers’ Comp
Coverage to help take care of employees who get sick or injured on the job. Most states require this coverage for small businesses with full- or part-time employees. It also can benefit business owners who don’t have employees.
From
$38.91
/month*
Business insurance —
a quick explainer
Learn more about policies for small businesses, what they cover, why you might need them, and how we can help – all in just 60 seconds.
Business insurance is often made up of different types of policies to cover different things, similar to how your health insurance can be made up of medical dental and vision coverage. Here are some of the ones small business owners need. General liability is kind of the Swiss army knife of insurance. It can do a lot, like help handle costs from third party accidents, property damage, bodily injury, and more. Nobody’s perfect, right? That’s what professional liability is for. It could come in handy in the event of honest mistakes or claims of negligence. Workers’ comp can protect your business and help take care of employees who get sick or injured on the job. Small businesses are big targets for cyber criminals. Cyber Insurance can help cover costs associated with stolen customer data, cyber attacks, breaches, and fraud. BOP or a business owners policy combines different types of coverages like general liability and commercial property insurance. Putting them together for you is where we come in. You tell us a bit about your business online or on the phone, and we customize the coverage options for what you do and what you need. It’s your business, it should be your insurance as well. That’s why we’re here.
What Type of Insurance Do I Need for My Dietitian Practice?
As a self-employed nutritionist, you need affordable liability insurance. In your field, anything can happen. Your recommendations can influence weight, food allergies, digestion, and can even help prevent diseases. But what happens if something goes wrong? Just imagine if one of your clients has a bad reaction to food, chokes, gets sick, or worse.
You can easily get blamed for negligence and have to pay the consequences. To help protect yourself, we recommend you get these policies:
Professional Liability Insurance
Food has the power to heal or hurt people. As a result, there’s a lot of risk in what you do. A client can easily blame you for an unexpected illness or emergency. Even if it wasn’t your fault, you may have to protect yourself from a lawsuit.
If you have professional liability insurance (PL), your policy can help protect you financially. It may also cover some or all of the costs of hiring a lawyer or obtaining evidence. If you have an employee working for you, it may help cover them too.
Let’s look at an example. Imagine a patient of yours has a severe allergic reaction to the foods you recommended in a new diet plan. As a result, your patient is rushed to the emergency room for immediate treatment. After the incident, you’re accused of negligence in your care and sued for damages.
If you have professional liability insurance, your policy can help protect you. If can cover some or all of the costs of hiring a lawyer and the cost of medical bills up to your policy’s limit. With coverage, you’re less likely to have to pay for damages out of your own pocket.
Here’s the reality—a lawsuit can happen to anyone, including nutritionists. That’s why it’s so important to secure PL insurance as soon as possible. It can help cover the costs associated with:
- Negligence or alleged negligence
- Obtaining a defense lawyer
- Omissions or alleged omissions
- Claims and damages
- And more
However, PL insurance usually doesn’t cover:
- Intentional acts and omissions
- Property damage
- Medical expenses
- Bodily injury
- And more
Commercial General Liability Insurance
Where do you meet with clients? Whether you have a home office, or you rent or own space, you need commercial general liability insurance (GL insurance). This policy can help cover costs if there’s an accident or damage to your workspace.
Accidents can happen anywhere and at any time, and you have to be especially careful if a client meets you at your office. At Simply Business, we recommend all that all self-employed dietitians get GL insurance. It can help cover costly medical bills and injury claims, which according to a recent industry benchmark study can average about $45,000! Just imagine paying that amount on your own. For many dietitians, it’s enough to put their practices under water.
Here’s an example of how GL insurance works. Let’s say a client visits your office to discuss a new diet plan you created. During his visit, a piece of your ceiling falls down and hits him on the head, severely injuring him. As a result, your client is rushed to the hospital and treated for a head injury. Shortly thereafter, he sues you for the costs of his medical bills and loss of work.
Fortunately, if you have general liability insurance, it can help cover the costs associated with:
- Bodily injury to another person
- Third-party property damage
- Personal and advertising injury
- Medical expenses
- And more
It’s important to know that most general liability insurance policies don’t cover:
- Damage to your own personal property
- Professional services
- Workers compensation or injury to your employees
- Damage to your work
- Automobiles while in business use
- Expected or intentional injury or damage
- And more
Workers Compensation Insurance
If your practice is quickly growing, chances are, you’ve hired someone to help you. Even if you only have one part-time or full-time employee, you need to consider getting workers compensation insurance. It can help cover costs if an employee is injured or sick on the job.
Depending on where you live, you may also be required by law to get workers compensation insurance. That’s because the law is trying to protect you from some pretty expensive claims, averaging about $41,000 each! Plus, work injuries are fairly common in the United States. In fact in 2018, Americans reported a total of $170.8 billion in workers compensation claims. That’s a huge chunk of change.
But here’s the good news. If you have a workers compensation policy, you don’t have to worry. You policy can help cover costs associated with:
- Medical payments
- Lost wages
- Rehabilitation expenses
- Death benefits
- And more
Why Should I Get Nutritionist Liability Insurance?
As a nutritionist, you’re at risk for getting sued. Whether you work with patients in a healthcare setting, the general public, or with corporate clients, anyone can accuse you of negligence. It doesn’t matter if your clients are high-risk patients or healthy athletes, anyone can have a bad reaction to food or get injured while visiting you.
If you don’t have liability insurance, you’re taking a huge financial risk. Maybe you’re just starting your practice and want to keep costs down until you grow your client base. Or maybe you don’t think someone would actually sue a nutritionist.
Unfortunately, 43% of small business owners say they’ve been sued or have dealt with a threatened lawsuit. It’s more common than you may think. Just one mistake or an unfortunate accident can put your practice—and everything you’ve built—at risk. Trust us, the cost of getting a policy is worth it, especially in today’s climate where lawsuits are common.
Just imagine if one of these claims is brought against you. Could you cover the costs all on your own?
- Reputational Harm — $50,000
- Client Injury or Damage — $30,000
- Client Slip and Fall — $20,000
If you have liability insurance, you can feel more relaxed. If an unexpected incident happens, you can enjoy peace of mind knowing your business is protected.
At Simply Business, we don’t want you to worry. After all, you should be focused on helping your clients change their diets and lifestyles. Leave it to us to help you find coverage that’s affordable and fully covers your practice.
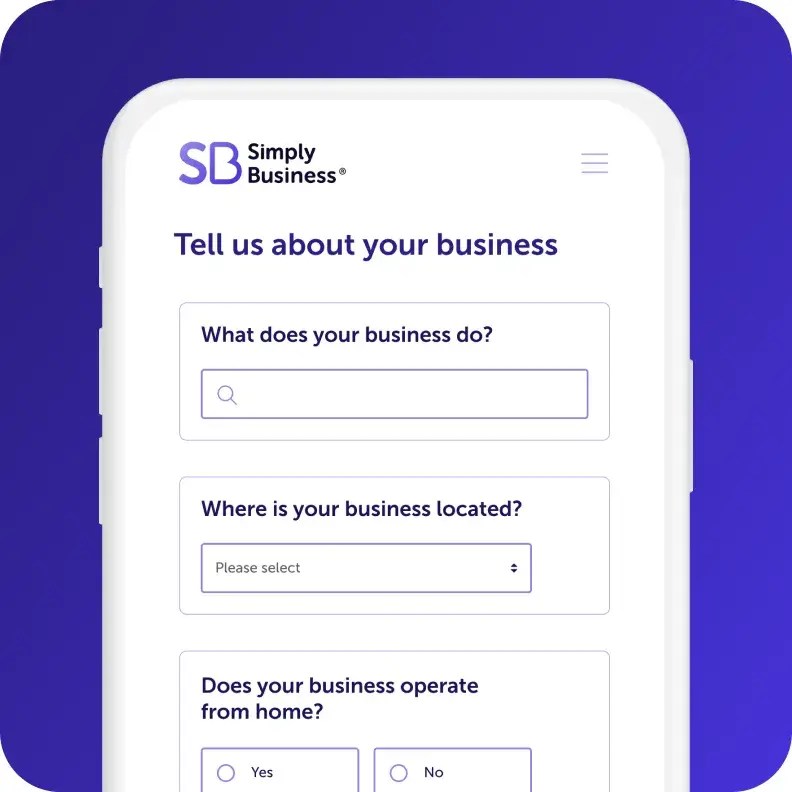
Are you ready to get a policy today? All you have to do is go to our online quote form. We’ll ask you a few, quick questions about your business and then recommend liability policies that may meet your needs. If you need a certificate of insurance (COI), we can help you with that too. We can prepare one that you can share with clients and vendors.
If you’re ready to get started now, get your free quote today.

What Does Nutritionist Insurance Cost
Try our insurance calculator.
Get a quick estimate in just 3 steps.

Answers to More Nutritionist Insurance Coverage Questions
It can be required, but it depends on where you work. Every state operates a little differently.
Fortunately, when you purchase insurance through Simply Business, you don’t need to know your state’s laws. Our online quote form is designed to show you policies that work in the state where you work.
Good news, business insurance is usually a tax deductible expense. This means you can help lower your tax deductible income just by purchasing liability insurance.
If you’re wondering how this works, we recommend talking to an accountant or another tax professional. They can help you deduct expenses and answer questions about your taxes.
There’s no one-size-fits-all answer here. Every dietitian has different insurance needs. It really depends on a few factors, including your practice’s:
- Size
- Location
- Annual revenue and payroll
- Much more
Fortunately, you don’t need to know how much liability insurance you need. Our online quote form is designed to recommend policies that fully cover you. That’s why we ask you questions about your work first. Then we show you insurance that can meet your needs.
If you have questions along the way, no problem. You can always contact one of our licensed insurance agents. They’re readily available to help answer your questions and help you understand how a policy works.
At Simply Business, we want to help you get insurance easily and quickly. To help make the process go as smoothly as possible, we recommend that you collect the following information ahead of time:
- Annual revenue estimates
- Payroll estimates
- Information on any previous claims
We may ask you to reference these details while you’re getting your online quote.
It can. The good news is that you don’t need to know all the laws, especially across states. They can greatly vary. Our online quote form is designed to show you policies that only work in your state.
We think most nutritionists should fully cover their practices. Full coverage usually includes a combination of professional liability, general liability, and workers compensation policies, if you have employees.
Together, combined coverage can help protect you from claims associated with:
- Bodily injury
- Accidents and damages
- Employee injuries
- Negligence or alleged negligence
- And more
The cost of liability insurance can vary. It really depends on what your practice needs. That’s why our online quote tool can recommend affordable coverage based on your practice’s:
- Payroll and revenue estimates
- Location
- Services
- And more
If you’d like to know what dietitian liability insurance may cost you, go to our online quote tool today. Just answer a few quick questions about your work, and we can recommend affordable policies in just 10 minutes or less.

Why Small Businesses Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

Start your quote
Answer a few questions about
your business in one form.

Review quotes
Compare quotes side by side from top-rated insurers and customize your coverage.

Get protected in minutes
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.

Written by
Our +1 million customers are big fans. And you will be too.

I went online, looked around, and found Simply Business. The process was so seamless. I got my certificate within minutes. It was just phenomenal.
Karen
Owner of Tangaza Bath & Body Studio LLC
With Simply Business I know I can look at different carriers, but also see all my stuff in the same place… a lot of [insurance] providers don’t offer a variety of coverage, all in one place.
Jef
Owner of Bunker83 LLC
It wasn’t overwhelming to figure out what was covered and what wasn’t covered. And the cost was competitive.

Kim
Owner of Room to Breathe Professional Organizing
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.
† Limits may vary by state and nature of your business.
‡ Displayed price is based on the lowest available coverage limit for Equipment and Small Tools policies.
Page last updated: