Appliance repair insurance
One application, multiple quotes. All in one place.
Essential Protection
From
$41.67
/month*
Could help cover claims against your business for property damage and injuries to others.
What’s included:
General Liability
Coverage limits: $1M to $2M†

Get multiple quotes in less than 10 mins
Essential Protection
From
$41.67
/month*
Could help cover claims against your business for property damage and injuries to others.
What’s included:
General Liability
Coverage limits: $1M to $2M†
Get multiple quotes in less than 10 mins
Would you rather pick and choose your coverage? Explore all options
Over 1 million customers worldwide.

Buy instantly online.

Written by
Why Do Appliance Technicians Need Insurance?
Appliance repair and installation is skilled, physical work, and that combination comes with real financial exposure. According to the National Safety Council, the average workers’ compensation claim from a workplace slip or fall now runs over $54,000.¹
Whether you’re installing a dishwasher in a single-family home, troubleshooting a fridge in a high-rise condo, or hauling a commercial range into a restaurant kitchen, one accident — a flooded kitchen, a stolen tool kit, or an injured crew member — can cost more out of pocket than most small businesses can absorb.
Below are some of the most common types of insurance policies that appliance techs carry to stay protected.
¹ 2022-2023 slip-and-fall Workers’ Compensation claim data cited by the National Safety Council (NSC)and sourced from National Council on Compensation Insurance.
What Type of Insurance Does An Appliance Technician Typically Need?

General Liability
A foundational insurance coverage to help handle costs from third-party accidents, property damage, and bodily injury.
From
$41.67
/month*

Business Owner’s Policy (BOP)
General liability, property insurance, and more all in one convenient package.
From
$33.75
/month*

Contractor’s Equipment and Small Tools Insurance
Also known as inland marine insurance, this coverage can financially protect equipment and inventory that’s in transport or stored offsite.
From
$20.83
/month‡

Workers’ Comp
Coverage to help take care of employees who get sick or injured on the job. Most states require this coverage for small businesses with full- or part-time employees. It also can benefit business owners who don’t have employees.
From
$38.91
/month*
Business insurance —
a quick explainer
Learn more about policies for small businesses, what they cover, why you might need them, and how we can help – all in just 60 seconds.
Business insurance is often made up of different types of policies to cover different things, similar to how your health insurance can be made up of medical dental and vision coverage. Here are some of the ones small business owners need. General liability is kind of the Swiss army knife of insurance. It can do a lot, like help handle costs from third party accidents, property damage, bodily injury, and more. Nobody’s perfect, right? That’s what professional liability is for. It could come in handy in the event of honest mistakes or claims of negligence. Workers’ comp can protect your business and help take care of employees who get sick or injured on the job. Small businesses are big targets for cyber criminals. Cyber Insurance can help cover costs associated with stolen customer data, cyber attacks, breaches, and fraud. BOP or a business owners policy combines different types of coverages like general liability and commercial property insurance. Putting them together for you is where we come in. You tell us a bit about your business online or on the phone, and we customize the coverage options for what you do and what you need. It’s your business, it should be your insurance as well. That’s why we’re here.
What Does Appliance Installation and Repair Insurance Typically Cover?
From the first service call to the final test cycle, even a routine appliance job can involve heavy equipment, active utilities, and your customer’s cherished belongings. Here’s how appliance installation and repair insurance can help protect your business when things go sideways:
You’re tightening the supply line on a dishwasher install when the fitting cracks. Water hits the cabinets and floor before you can reach the shutoff valve and suddenly you’re looking at a soaked kitchen, ruined subfloor, and a homeowner on the phone with their own insurance. A standard general liability policy provides coverage for the cost of repair or replacement and protects you from other third-party property damage or bodily injury claims, up to the policy limits

Your phone rings at 2 a.m. By the time you get to the shop, the fire crew is already rolling up the hoses. The parts inventory you’d been building and the diagnostic equipment you rely on — all of it, gone. A business owner’s policy (BOP) typically bundles general liability, commercial property protection, and business interruption coverage to help pay for damages, repairs, and lost income so you can get back to work quickly.
Many appliance technicians choose a BOP because it offers more protection than a stand-alone general liability policy without costing much more — a great option if you’re established or planning to grow.
Your employee is lifting one end of a commercial refrigerator up a basement stair when their grip gives: one second they’re carrying — the next they’re on the ground, holding their lower back. The strain needs a doctor’s visit and three weeks off the job. Workers’ compensation insurance can help cover their medical bills and replace a portion of their wages as they recover.
Workers’ comp is often legally required and can protect your business from costly claims, as well as taking care of your crew if they get sick or injured on the job. Even if you operate solo, workers’ compensation insurance is highly recommended, because many health insurance policies do not cover work-related injuries.
You finish a morning service call and stop for lunch on the way to your next appointment. Twenty minutes later, you walk back to find your van’s rear window smashed and your tool bag, diagnostic kit, and cordless drills cleaned out. Contractor’s equipment and small tools coverage, also known as inland marine insurance, can help pay to replace or repair your stolen or damaged equipment while your locked vehicle is at a jobsite or in transit.
Who Needs Appliance Installation and Repair Insurance
Appliance repair and installation work covers a range of specialties, and most face similar risks. You may want to consider appliance installation and repair insurance if you’re a:
If you are a residential repair technician working inside occupied homes, where a slipped wrench or nicked water line can damage floors, cabinets, or finishes.
If you are a major appliance installer handling refrigerators, washers, dryers, and ranges, where heavy lifting and tight spaces raise the odds of a work-related injury or property damage.
If you are a home warranty network contractor dispatched through companies like American Home Shield, Choice, or 2-10, which typically require a current certificate of insurance before assigning work.
If you are a big-box installation subcontractor delivering and installing for major retailer programs.
If you are a commercial kitchen and restaurant equipment specialist installing ranges, walk-ins, or commercial dishwashers, where a single mistake can lead to costly property damage.
If you are a refrigeration or specialty technician working with complex electrical components and high-value equipment in residential and light-commercial settings.
Whatever your specialty, if you work on client property, handle expensive tools and equipment, or employ a crew, insurance can help protect what you’ve built.
How Much Does Appliance Installation and Repair Insurance Cost?
Appliance installation and repair business insurance costs1 between $27 and $132 per month for core policies including general liability, business owner’s policy (BOP), workers’ compensation, and contractor’s tools & equipment coverage. Your final premium will depend on factors such as your location, the type of work you do, the number of employees you have, your annual revenue, and your claims history.
Median Monthly Costs1
| General liability | $107 |
| Contractor’s tools & equipment | $27 |
| Workers’ compensation | $132 |
| Business owner’s policy | $48 |
1 Pricing based on general liability, contractor’s tools & equipment, BOP and WC policies purchased from Simply Business by customers identifying as “appliance and accessories installation and repair” between July 1, 2025 and December 31, 2025.

Try Our Appliance Installation and Repair Insurance Calculator
Get a quick estimate in just 3 steps.
Answers to More Appliance Installation and Repair Insurance Coverage Questions
Appliance installation and repair insurance is a collection of separate policies frequently bought by appliance technicians that can help protect your business from some of the most common risks of the trade — accidental damage to a customer’s home, worker injuries, and stolen or damaged tools.
Most states legally require workers’ compensation if you have employees, and many often mandate a contractor’s license with liability coverage for electrical, plumbing, or refrigerant work. Home warranty companies, property managers, and big-box retail installation programs can also ask for proof of insurance before they’ll dispatch a job. Check with your state licensing board and any networks you contract with for specific requirements.
Yes. COIs for most policies are available as soon as you purchase your coverage. With Simply Business, you can download and share your certificate of insurance instantly through your online account or right from your phone when a home warranty company or property manager needs proof before dispatching a job.
Home warranty companies typically require contractors to carry general liability insurance — and sometimes workers’ compensation — before they’ll dispatch a job. Many networks set their own coverage minimums and won’t add you to their rotation without a current certificate of insurance (COI) on file, so maintaining an active policy can be part of staying eligible for work.
Most warranty networks ask for a current COI listing the warranty company or property manager as a certificate holder so they have your coverage documentation on file. Some may also require that they be added as an additional insured on your General Liability policy. With Simply Business, you can instantly pull your COI up on your phone the moment a network coordinator asks for it.
An additional insured is another party — usually a home warranty company, property manager, or general contractor — added to your General Liability policy. Many networks require that you add them as an additional insured to your policy before they’ll dispatch you to a job, because it extends your liability coverage to protect them if a customer files a claim related to your work.
Most states don’t require workers’ compensation for sole proprietors. But even when it’s not legally mandated, we recommend workers’ comp insurance because many health insurance policies don’t cover work-related injuries. And some general contractors and home warranty networks can ask subcontractors to carry their own workers’ comp, even if they’re solo. Requirements vary, so it’s important to check your state requirements and the contracts you sign.
Yes, in most cases. General liability is designed to cover third-party property damage — meaning damage to a customer’s home or belongings caused by your work. If a water line leaks during a dishwasher install and floods the kitchen, or you scratch a hardwood floor sliding a refrigerator into place, your General Liability policy can help cover repair or replacement costs and any related legal fees.
Possibly. General liability policies often include “completed operations” coverage, which can apply to property damage or injury claims that arise after a job is finished, for example, a water connection that fails two weeks after a dishwasher install and floods the kitchen below. Coverage depends on policy terms and whether the policy was active at the time the work was completed.
Sometimes, but not always. Standard general liability policies typically don’t cover damage to the appliance you’re installing while it’s in your care — that’s considered “property in your care, custody, or control,” which is often excluded. Installation floater coverage or an inland marine endorsement can help fill that gap, covering accidental damage to a customer’s appliance while you’re working on it or transporting it.
Commercial work usually requires higher coverage limits and may need additional endorsements. If your work involves gas connections, refrigerants, or commercial-grade equipment, your policy may also need specific endorsements to match the increased risk.
Your insurance cost depends on several factors, including, but not limited to:
- The type of appliances you install and the services you provide
- Claims history and time in business
- Where your business is located
- Your annual revenue and payroll
- The value of your tools and equipment
- The number of employees or subcontractors you have
- The types of policies, coverage limits, and deductibles you choose
A few things worth checking before you buy:
- Are your tools and equipment covered at replacement cost or actual cash value?
- Does the policy cover gear in your service van and in transit, or only at a fixed location?
- Are you covered for damage to the appliance you’re installing while it’s in your care?
- If you contract through home warranty networks or big-box retailers, does the coverage meet their specific requirements?
- Are subcontractors covered under your policy, or do they need their own?
Our licensed agents can walk you through these questions — give us a call.

Why Small Businesses Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

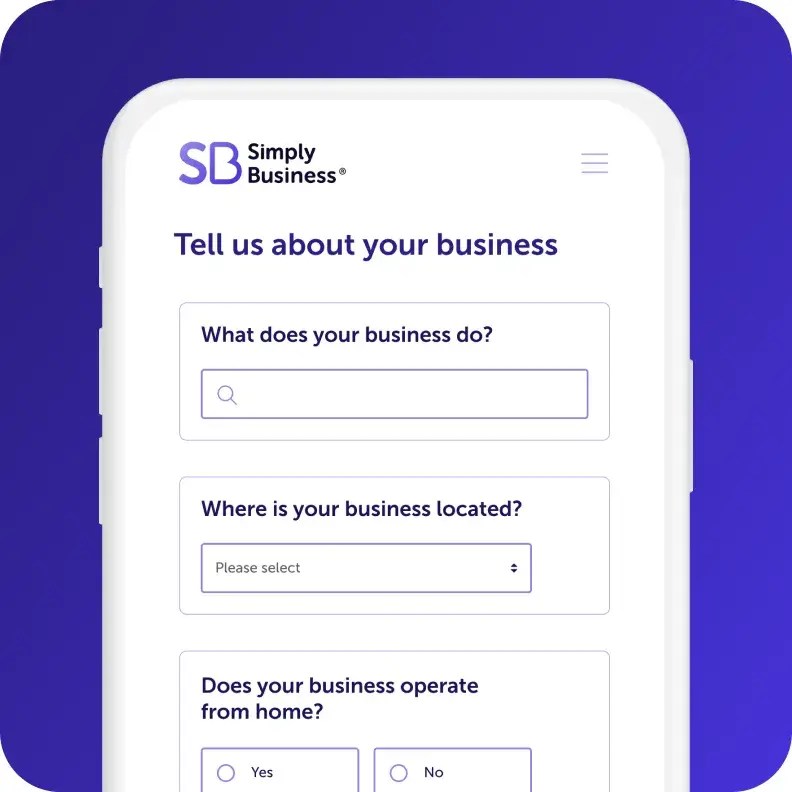
Start your quote
Answer a few questions about
your business in one form.

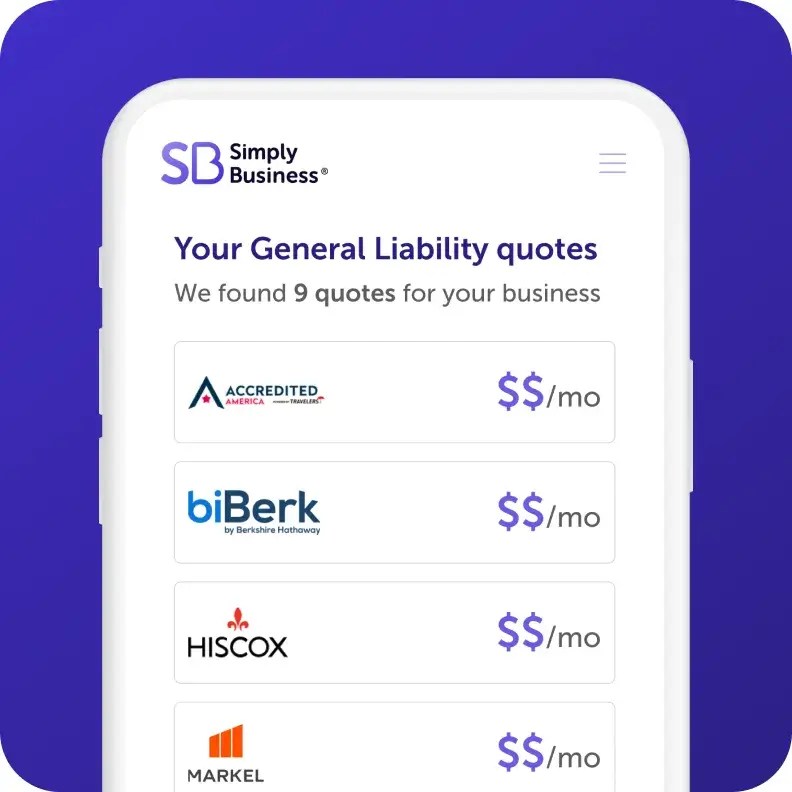
Review quotes
Compare quotes side by side from top-rated insurers and customize your coverage.

Get protected in minutes
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.

Written by
Our +1 million customers are big fans. And you will be too.
I went online, looked around, and found Simply Business. The process was so seamless. I got my certificate within minutes. It was just phenomenal.
Karen
Owner of Tangaza Bath & Body Studio LLC
With Simply Business I know I can look at different carriers, but also see all my stuff in the same place… a lot of [insurance] providers don’t offer a variety of coverage, all in one place.
Jef
Owner of Bunker83 LLC
It wasn’t overwhelming to figure out what was covered and what wasn’t covered. And the cost was competitive.

Kim
Owner of Room to Breathe Professional Organizing
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information

*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.
† Limits may vary by state and nature of your business.
‡ Displayed price is based on the lowest available coverage limit for Equipment and Small Tools policies.
Page last updated: