Small Business Insurance in Delaware

Get a price estimate in just three steps
Rates as low as $20.75/month*
Get a price estimate in just three steps
Rates as low as $20.75/month*
Over 1 million customers worldwide.

Buy instantly online.

Written by
Delaware Small Business Insurance
Delaware is home to over 110,000 small businesses, which make up nearly 99% of all businesses in the state and employ nearly 215,000 people. They work across a range of sectors, from construction and coastal hospitality to the financial and legal services concentrated in and around Wilmington.
Delaware business insurance requirements depend on the work you do, the size of your workforce, and where you operate, among other factors. Workers’ compensation is set by state law. Several licensed trades carry their own coverage minimums, and landlords and clients often ask for proof of insurance before you can sign a commercial lease or start a job.
Knowing which rules apply to you can help you get the business insurance that’s right for you.
Is Business Insurance Required in Delaware?
Delaware requires workers’ compensation insurance for employers with one or more employees. And state law requires that the owner of any vehicle registered in Delaware carry insurance on it before anyone operates it.
General liability and professional liability insurance aren’t mandated statewide for most businesses. Certain licensed trades (pesticide applicators, electricians, and home inspectors) are the exception. Outside of licensing, commercial landlords and clients commonly ask for proof of coverage before you can acquire a Delaware business license, sign a lease, or start a contract.
When an employee is hurt on the job or develops a work-related illness, workers’ compensation insurance helps pay for their treatment, part of the wages they lose while recovering, and rehabilitation costs. It may also pay benefits to the family member of a worker who dies from a workplace injury.
Employers with one or more full- or part-time employees in Delaware generally need workers’ comp insurance. A few exceptions to this rule include farm workers or independent contractors, who typically aren’t classified as employees. In the construction industry, workers are presumed to be employees by default under the Delaware Workplace Fraud Act, requiring employers to meet rigorous statutory thresholds to classify them as independent contractors and be exempt from workers’ compensation requirements.
There are ways to potentially lower workers’ compensation premiums through the Workplace Safety Program, which allows businesses to earn insurance discounts if they follow safe workplace rules.
General liability insurance covers third-party bodily injury, property damage, and medical expenses claims. Delaware doesn’t require GL coverage for most businesses, though commercial landlords and clients often ask for proof of coverage before you can sign a lease or begin working.
In Delaware, some licensed trades have their own requirements. For example, pesticide applicators need a policy with at least $300,000 for bodily injury or death and $100,000 for property damage. Electricians need proof of at least $300,000 in GL coverage before the Board will issue a license. Home inspectors need at least $250,000 in liability coverage. For electricians and home inspectors, an employer’s policy can satisfy the requirement as long as you’re named on the policy.
If you’re a general contractor in Delaware, we have a complete guide to getting licensed and insured.
Professional liability insurance can help when a client alleges your work or advice caused them harm. It typically covers negligence claims, legal defense costs, and related expenses. You don’t have to do anything wrong for a client for them to claim you were negligent, and even innocent business owners can face legal bills defending a case in court.
Delaware doesn’t require professional liability coverage for most businesses. Home inspectors are the exception, and they need at least $50,000 in errors and omissions insurance on top of liability coverage, which they or their employer can carry.
Accountants, real estate agents, and consultants commonly carry E&O coverage as well, and clients sometimes ask for proof of the coverage before signing a contract.
Most personal auto policies exclude business use, which means an accident on the clock can come back to the business owner directly. Commercial auto coverage is for vehicles that are directly involved in work, like delivery vans and equipment haulers.
Delaware requires the owner of any registered vehicle to carry insurance on it. That requirement extends to all vehicles. The state sets minimum limits of $25,000 per person for bodily injury, $50,000 per accident for bodily injury, and $10,000 for property damage. Delaware also requires personal injury protection of at least $15,000 per person and $30,000 per accident.
As of the date when this article is published, Simply Business doesn’t offer commercial auto insurance, but our licensed insurance agents can help you find providers who do.
Get free Delaware business insurance quotes in 10 minutes or less.
Simply Business provides customized coverage options from top-rated small business insurers — all in just 10 minutes. We do all the leg work so you can sit back, compare quotes, and save.
How Much Does Business Insurance Cost in Delaware?
What you pay for business insurance in Delaware comes down to the specifics about your operation, as well as other factors such as where your business is located, how many employees you have, and other details about your business. Two businesses on the same street can wind up paying much different rates for their policies.
Here are the median monthly cost ranges for common policies based on purchases by Simply Business customers in Delaware:
Median Monthly Costs1
| General liability | $41 |
| Professional liability | $41 |
| Workers’ compensation | $100 |
| Business owner’s policy | $47 |
1Data from Simply Business customers located in Delaware who purchased at least one or a combination of BOP, general liability, professional liability, and workers’ compensation policies from July 1, 2025 to December 31, 2025. The median costs shown are for illustrative purposes only; actual premiums vary by state, coverage limits, and individual business risk, among other factors.
Several things can affect how much you pay for insurance, including:
- Payroll: Workers’ comp premiums track what you pay your staff and how many people you employ, so a growing crew may increase costs.
- Industry risk: A roofing crew working at height and a bookkeeper working at a desk face different risks, so pricing typically follows the increased risk.
- Location: A shop in Rehoboth Beach sits closer to coastal storm and flood risk than one inland near Dover, and property coverage prices may differ accordingly.
- Claims history: Carriers often view a record of past claims as telling an insurer what to expect, whereas a clean record often works in your favor.
State-Specific Risks for Businesses in Delaware
Small businesses operating in Delaware face some unique risks shaped by the state’s coastline, its river corridors, and its data notification law.

Coastal Storms and Nor’easters
Nor’easters and coastal storms bring heavy rain, damaging winds, and flooding to beach towns such as Rehoboth Beach, Dewey Beach, and Bethany Beach. Commercial property coverage typically pays for wind and storm damage to your building and its contents, and business interruption coverage can help replace income you lose while you’re closed down for repairs.

Flooding
However, flooding can impact areas beyond beaches. Wilmington and northern New Castle County have flooded when local rivers rose, and Delaware City also has experienced storm surges. Standard commercial property and business owner’s policies (BOP) exclude flood damage, so businesses in a flood-prone area may want a separate policy through the National Flood Insurance Program or a private insurer

Data Breach Notification
Delaware businesses that own or license personal information must notify affected residents without “unreasonable delay” and no later than 60 days after determining a breach happened. State law also requires businesses to maintain reasonable procedures to protect that information
Cyber liability insurance in Delaware can help with the cost of meeting that 60-day deadline, from notifying affected residents to legal support and getting systems back online.

Delaware LLC Incorporation vs. Operating State
Delaware is a common place to incorporate a business, including companies that operate outside the state. Insurance requirements generally follow where a business is actually situated, where it provides services, and where it hires employees, meaning that a company formed in Delaware but operating in another state usually follows that state’s coverage rules.
However, state law requires every entity formed in Delaware to maintain a registered agent in the state, whether or not the owners live or operate in Delaware.
Who Needs Delaware Small Business Insurance?
Best Delaware Business Insurance for Your Industry
Insurance needs to change from one industry to the next. Here’s what Delaware small businesses in a few common sectors tend to look at.
Construction crews work on active jobsites with heavy equipment, and the work can damage property that belongs to someone else. GL helps cover these claims, and workers’ compensation requirements apply once you have your first employee, and licensed trades may carry their own liability minimums.
Contractors near the coast or Delaware’s rivers may face weather risk on top of jobsite exposure. Commercial property coverage typically covers wind damage to your building, while inland marine coverage protects your damaged tools. Business interruption coverage can help replace income while a site is closed. That being said, commercial property policies often exclude flood damage, so a separate policy may be worth a look.
Delaware’s beach towns draw summer crowds, and the bars, restaurants, and lodging businesses in these locations deal with heavy foot traffic in a short season. A business owner’s policy in Delaware typically packages commercial property and general liability coverage together at a less expensive price than if a business were to buy each policy separately, which is why it’s a common starting point for these businesses.
Standard general liability policies typically exclude liquor liability for businesses that sell or serve alcohol. Liquor liability coverage may be included in your policy, depending on your carrier, whether you hold an active Delaware alcohol license, and where you operate.
How to get a Certificate of Insurance in Delaware
A certificate of insurance (COI) is proof that your policy is active during the policy period, showing your coverage limits and anyone named as an additional insured. Delaware businesses are often asked for one by a landlord, a licensing board at application time, or a client before a project.
After your policy is in place, you can typically download a COI from your insurer’s online portal within minutes. You also can request a version naming a specific landlord, client, or project owner as an additional insured.
Answers to More Questions About Delaware Small Business Insurance
Delaware requires workers’ comp once you have one or more employees. Farm workers and independent contractors may be exempt from workers’ compensation requirements under the statute in certain circumstances, but an employer may still choose to provide coverage.
Incorporating in Delaware doesn’t create insurance obligations by itself. Requirements generally follow where you work, hire, and serve customers, so a company formed in Delaware but operating elsewhere usually follows that state’s rules.
Delaware’s Workplace Safety Program is a premium discount program run by the Insurance Commissioner’s Office. Businesses with at least three years of continuous workers’ compensation coverage that have paid at least $5,000 in premium over the last three years are eligible, and an inspection determines whether you qualify. There’s no penalty for applying and not qualifying.
Storm and wind damage is often covered by commercial property insurance, but damage caused by flood is not. Businesses in flood-prone areas of Delaware may want a separate policy through the National Flood Insurance Program or a private insurer.
Our Delaware customers are big fans. And you will be too.
It was fast, very easy to do, and I didn’t have to wait for coverage.
Deborah D.
Housekeeping
The representative was wonderful. Super helpful and ultimately helped me make the best decision.
Ryan S
Restaurant owner
Very helpful and efficient getting insurance for my business.
Jason D.
Carpentry
Additional Information and State Resources for Delaware Small Business Owners

Written by

Why Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

Start your quote
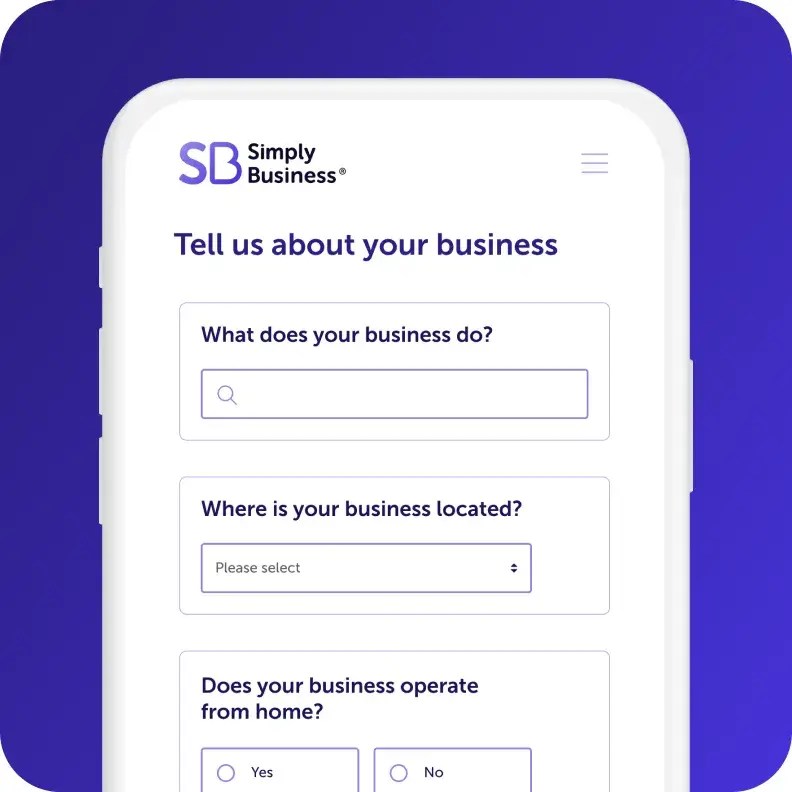
Answer a few questions about
your business in one form.

Review quotes
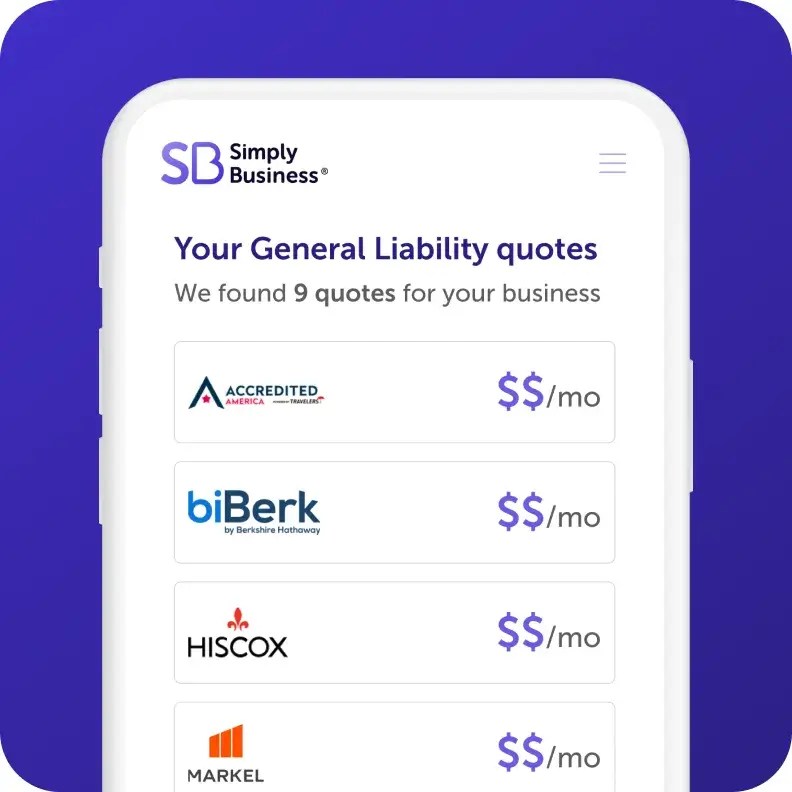
Compare quotes side by side from top-rated insurers and customize your coverage.

Get protected in minutes
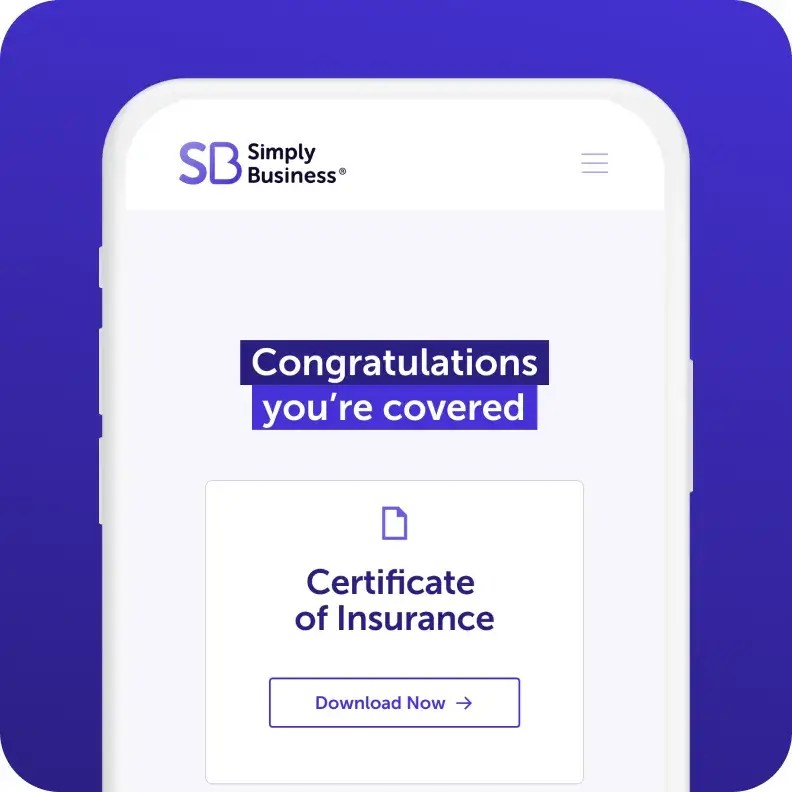
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.