Small Business Insurance in Illinois

Get a price estimate in just three steps
Rates as low as $20.75/month*
Get a price estimate in just three steps
Rates as low as $20.75/month*

Over 1 million customers worldwide.

Buy instantly online.

Written by
Illinois Small Business Insurance
Across Illinois, small business comes in just about every form — from Elgin contractors and Rockford manufacturers to the local shops of Springfield, Peoria, and the Quad Cities.
But no matter where you operate, doing business in the Prairie State means planning for a challenging mix of risks. Tornadoes and summer derechos sweep through the region, rivers like the Illinois and Mississippi flood towns along their banks, and workers’ comp is typically mandatory from your very first employee for most businesses, with steep penalties for non-compliance.
In this Illinois business insurance guide, we’ll unpack what coverages are typically required, the policies clients usually expect, and what they often cost so you can get covered with confidence.
What Types of Small Business Insurance Are Required in Illinois?
Illinois’s insurance requirements depend on your industry, workforce, and business operations.
Here’s a breakdown of the coverages you’ll most likely need:
Workers’ compensation can help cover medical bills, rehabilitation costs, and time away from work if an employee suffers a job-related illness or injury.
In Illinois, the rule is strict: almost any business with employees must carry workers’ comp, and coverage is required from your very first hire — whether they’re full-time, part-time, or even family. The Illinois Workers’ Compensation Commission (IWCC) enforces this mandate under the Illinois Workers’ Compensation Act, and employers who knowingly fail to provide Workers’ Comp can face heavy fines — up to $500 for every day of non-compliance, with a minimum fine of $10,000.
Sole proprietors, partners, corporate officers, and LLC members can often choose to exempt themselves from covering their own roles under the policy, but they still need to have coverage for their employees. And if you hire subcontractors who don’t carry their own Workers’ Comp coverage, you could be held responsible for their claims. That’s why it’s a good idea to require subcontractors to carry their own workers comp insurance and request a Certificate of Insurance proving coverage before anyone sets foot on your job site.
General liability insurance typically helps protect your small business against third-party claims, such as property damage and bodily injury. If a customer slips on your shop floor or your crew accidentally damages a client’s property on the job, General liability is designed to help cover those expenses.
While Illinois state law doesn’t require general liability for most small businesses, you may need it to obtain a license. For example, Illinois roofing contractors must carry general liability to maintain their IDFPR license (225 ILCS 335/3). And local municipalities like Chicago often require specific coverage minimums before issuing building or contractor approvals.
Beyond licensing and local permits, landlords often want proof of general liability coverage before approving a commercial lease, and clients routinely require coverage for their contracts.
A BOP typically bundles general liability, commercial property protection, and business interruption coverage to help pay for damages, repairs, and lost income so you can get back to work quickly.
Illinois doesn’t require that businesses carry a BOP, but for retail shops, restaurants, and other businesses with a location and equipment to protect, bundling property and liability coverage can be a cost-effective way to protect against everyday risks — from kitchen fires and theft to severe weather like summer derechos.
Just know the limits: a standard BOP usually won’t cover flood damage from rising water, a real gap in coverage in river towns and low-lying parts of Chicago. Businesses in those areas can add a separate commercial flood policy to stay covered.
Professional liability insurance, also known as errors and omissions (E&O) coverage, helps protect you from claims of negligence, missed deadlines, and errors or omissions in the work you deliver. It can also help cover legal defense costs, settlements, and judgments if a client files a formal legal claim against you, up to your policy limits.
While Illinois doesn’t require E&O by law, it can be essential coverage — one disputed deliverable or missed detail can turn into a claim that can cost you far more than years of premiums. And many employers in Chicago’s robust professional and financial-services sector won’t start a project without it.
If your business owns or operates vehicles, your personal auto policy typically won’t cover accidents that happen during business use. A separate commercial auto policy covers business driving, including heading to job sites, making deliveries, visiting clients, or hauling equipment.
Any vehicle your business owns and registers in Illinois must carry liability coverage, and the state sets the minimum limits based on the size of your vehicle and what you transport. You can confirm these current amounts through the Illinois Secretary of State, which handles vehicle registration and insurance verification.
As of the date of this article, Simply Business doesn’t offer commercial auto insurance in Illinois, but our licensed insurance agents can help you find trusted providers that do.
Get free Illinois business insurance quotes in 10 minutes or less.
Simply Business provides customized coverage options from top-rated small business insurers — all in just 10 minutes. We do all the leg work so you can sit back, compare quotes, and save.
How Much Does Business Insurance Cost in Illinois?
Here are the median monthly costs1 for common small business insurance policies in Illinois:
Median Monthly Costs1
| General liability | $41 |
| Professional liability | $41 |
| Workers’ compensation | $100 |
| Business owner’s policy | $47 |
1Data from Simply Business customers specializing in Illinois who purchased at least one or a combination of general liability, professional liability, BOP, or workers’ compensation policies from July 1, 2025 to December 31, 2025. Reflected price tiers may not include purchase of all available policies under general contractor insurance.
The cost of business insurance in Illinois depends on several factors, and pricing can vary from one business to the next.
Some factors that affect your premium include, but are not limited to:
- Payroll and employee count: Workers’ comp is tied to your total payroll, so a larger team usually means a higher premium.
- Industry risk: A roofing crew in Belleville carries a very different risk profile than an accountant working from a suburban office in Schaumburg, and premiums reflect that.
- Location: Businesses in the Chicago metro area often pay more for property coverage than those downstate, where costs and some risks can run lower.
- Claims history: A clean record helps; past claims can push your rate up at renewal. Opting for a higher deductible can also lower your premium.
- Severe weather exposure: Tornadoes, hail, and severe storms reach much of Illinois, and areas with heavier exposure — or a history of storm claims — can see that reflected in property premiums.
State-Specific Risks for Businesses in Illinois
In Illinois, your risk profile depends on where and how you operate. Severe storms, river flooding, urban crime, and data breach rules all create exposures that standard policies don’t always cover.
Here’s what to watch and how the right coverage helps.

Tornadoes & Severe Weather
Central and Southern Illinois sit in one of the country’s most active severe-weather corridors. Tornadoes, damaging hail, and summer derechos can tear off roofs, shatter windows, and shut a business down for days or weeks. Commercial Property and Business Interruption coverage — often bundled in a BOP — can help pay to repair the damage and replace lost income while you rebuild.

Flooding
Flooding is a serious, recurring risk in Illinois, especially in the towns along the Illinois and Mississippi Rivers and in low-lying parts of the Chicago area. But standard Commercial Property and BOP policies typically exclude flood damage from rising water. To be covered, you’ll need a separate policy through the National Flood Insurance Program (NFIP) or a private insurer.

Chicago Urban Risk — Theft & Vandalism
For businesses in Chicago and other dense urban areas, theft, break-ins, and vandalism are real and costly exposures. Commercial Property coverage can help repair a smashed storefront or replace stolen equipment and inventory. Just keep in mind that standard property coverage stops at your doorstep. If your crew travels with high-value tools, equipment, or electronics, adding Inland Marine can help protect your gear while on the go and at job sites.

Data Breach
If your business handles customer data and suffers a data breach, Illinois’s Personal Information Protection Act requires you to notify affected residents without unreasonable delay. And if a breach impacts more than 500 Illinois residents, you must also notify the Illinois Attorney General, and violations are enforced under the state’s Consumer Fraud Act. Cyber Liability insurance can help cover notification, credit monitoring, and the cost of responding to regulators.
Who Needs Illinois Small Business Insurance?
Illinois Business Insurance Best Suited for Your Industry
Every industry carries its own risks, and Illinois’s diverse economy means no two coverage needs look alike. Here’s where the state’s biggest sectors tend to focus.
From Chicago high-rises to downstate road crews, the best Illinois construction policies protect your crew, tools, and bottom line against high-risk job site hazards.
A strong policy foundation starts with high-limit General Liability for property damage and Workers’ Compensation to cover work-related injuries. Carrying these policies can also satisfy state licensing requirements and local permit standards so you can win bids without compliance delays. And adding Inland Marine can help protect your equipment, tools, and building materials on-the-go or at a jobsite.
For many Illinois retail shops and restaurants, a Business Owner’s Policy is the foundation of their protection — it typically bundles Commercial Property, General Liability, and Business Interruption coverage so a fire, theft, or customer injury doesn’t put you out of business.
Restaurants and bars that serve alcohol have an extra layer of risk to weigh: under the Illinois Dram Shop Act (235 ILCS 5/6-21), a business can be held liable when a patron it served causes harm. Because of this exposure, the state of Illinois and local municipalities strictly require proof of liquor liability (dram shop) coverage to secure and maintain your liquor license.
Chicago is a national hub for finance and tech, and professional-services firms operate across the state. For consultants, IT providers, accountants, and financial firms, Professional Liability (E&O) insurance can help protect against claims that your work caused a client financial harm or financial loss. And because Illinois’s Personal Information Protection Act sets strict obligations around customer data, Cyber Liability coverage can serve as a smart safety net for anyone holding sensitive client or financial information.
How to get a Certificate of Insurance in Illinois
A certificate of insurance (COI) is a document that shows your business has active coverage, along with the policy type(s), limits, and your insurer(s). Massachusetts clients, landlords, and licensing boards commonly ask for one before you take on a project, move into a leased space, or renew a license.
With an active Simply Business policy, you can pull your COI from your account, list clients as additional insureds, and download it whenever you need it.
FAQs About Illinois Business Insurance
Illinois doesn’t require general liability by law for most businesses, including LLCs. In practice, though, landlords, clients, and local permitting offices often ask for proof of coverage before you can sign a lease, pull a permit, or win a contract — and some state-licensed trades, like plumbing, must carry it to be licensed.
It depends on the trade. State-licensed trades like roofing contractors must carry a general liability policy with a minimum of $250k for property damage and $500k for injury, while local municipalities like Chicago set their own minimums. Even when not mandated by law, general contractors and clients typically require proof of coverage before work begins.
Yes. For most businesses, Illinois requires workers’ compensation insurance from your very first employee — full-time, part-time, or family — under the Illinois Workers’ Compensation Act. While sole proprietors, partners, corporate officers, and LLC members can often choose to exempt themselves from covering their own roles, coverage for any workers you hire is strictly mandatory.
Significant. An employer that knowingly fails to provide employees with coverage can face heavy fines, and the Illinois Workers’ Compensation Commission can issue a stop-work order halting your operations. Corporate officers can be held personally liable in some circumstances, and an employer can be sued directly by an injured worker.
No. Standard commercial property and BOP policies typically exclude flood damage from rising water. To cover flooding — a real risk along the Illinois and Mississippi Rivers and in low-lying parts of the Chicago area — you’ll most likely need a separate policy through the NFIP or a private insurer.
Yes, if your business owns vehicles. Personal auto policies exclude business use, so a work-related accident could be denied without a dedicated commercial auto policy. Illinois-registered vehicles must carry liability coverage and uninsured motorist coverage at the state’s minimum limits.
The Illinois Department of Insurance regulates insurers and the insurance market statewide, while the Illinois Workers’ Compensation Commission oversees workers’ comp and the Illinois Secretary of State handles auto insurance verification for registered vehicles.
Usually, yes. The IRS and the Illinois Department of Revenue generally let businesses deduct insurance premiums as an ordinary and necessary business expense, as long as the coverage is for your trade or business. Check with a tax professional about your specific situation.
Our Illinois customers are big fans. And you will be too.
Very helpful and efficient getting insurance for my business.
Jason D.
Carpenter
The representative was wonderful. Super helpful and ultimately helped me make the best decision.
Ryan S.
Restaurant owner
Very easy to obtain with lots of options to add as far as what your business needs. The pricing was also better than all could offer.
Darrell I.
General contractor
Additional Information and State Resources for Illinois Small Business Owners
- Illinois Department of Insurance
- Illinois Workers’ Compensation Commission
- Illinois Secretary of State
- How to get a business license in Illinois
- Getting a contractor’s license in Illinois
* Citations and financial figures accurate as of the date this article was published.

Written by

Why Choose Simply Business
Small business insurance is what we do. Whether it’s covering you for accidents and errors, meeting workers’ comp requirements, or financially protecting your business from the unexpected, we can help find the coverage you need for your business.

Start your quote
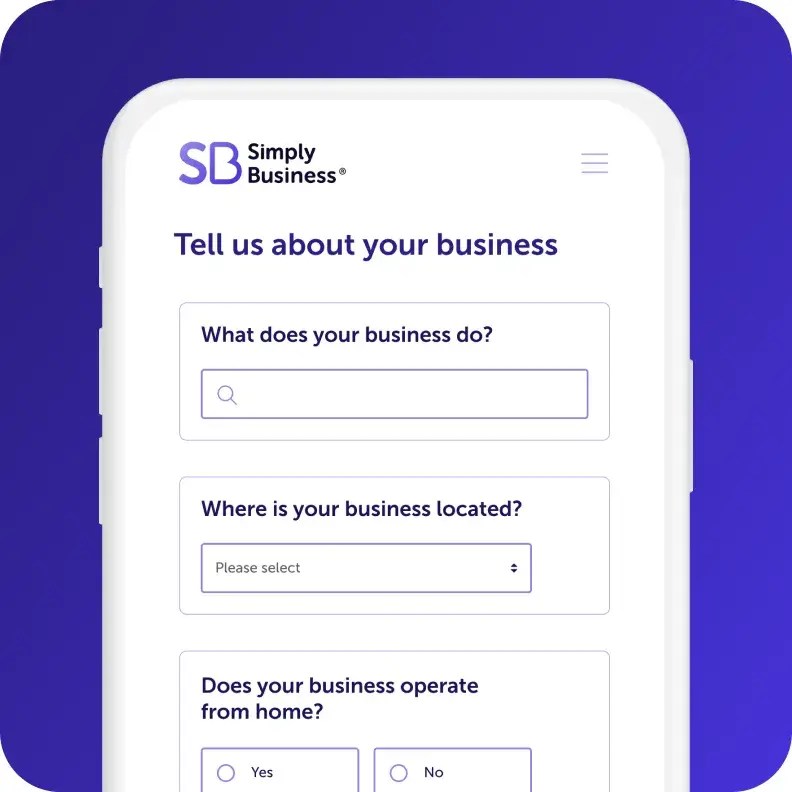
Answer a few questions about
your business in one form.

Review quotes
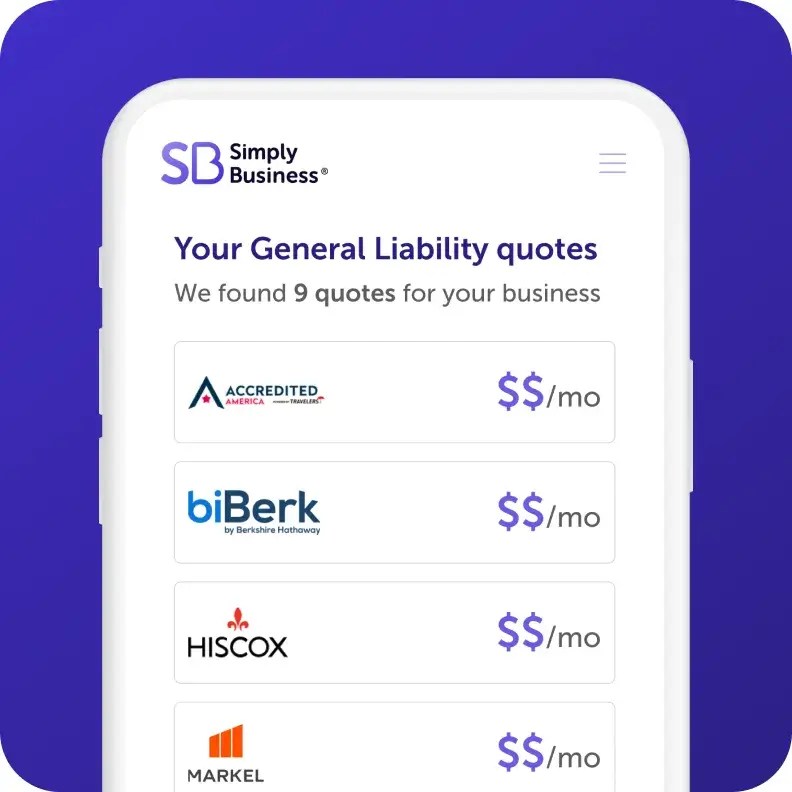
Compare quotes side by side from top-rated insurers and customize your coverage.

Get protected in minutes
Choose your policy, and get instant proof of insurance – all online, and all within 10 minutes.
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.
Page last updated: